
What Is Drawing Attention To NH Foods (TSE:2282)?
Fresh valuation work on NH Foods (TSE:2282) has put its free cash flow front and center, with discounted cash flow estimates implying a share value above the current market price.
Recent trading has been calmer for NH Foods, with the share price up 2.86% over the past month but still down 5.74% year to date. At the same time, the 1-year total shareholder return of 10.79% and 5-year total shareholder return of 76.57% point to longer term momentum that frames the current discounted cash flow valuation debate.
Compare NH Foods' valuation story with other potential opportunities by scanning our hand picked list of 14 high quality undervalued stocks that also pair cash generation with balance sheet strength.
NH Foods has a long track record and solid brands, yet the share price has only edged up recently. Is this still a quality business that the market is pricing too cautiously today?
Price-to-Earnings of 17.1x: Is it justified?
On earnings, NH Foods trades on a P/E of 17.1x, which leaves the share price at ¥2,084 looking slightly rich relative to the broader food sector but still below some peer valuation markers.
The P/E ratio compares what investors are willing to pay today for each unit of current profit. It acts as a shorthand for expectations around future earnings and business stability. For a mature food producer with long established brands and a full value chain from livestock to processed products, this measure often becomes a primary yardstick for how the market weighs reliability of cash generation against growth prospects.
NH Foods is flagged as good value against an estimated fair P/E of 19.9x. This implies the current multiple is below a level the market could conceivably move toward if earnings delivery stays consistent. At the same time, the stock is described as expensive versus the Japanese food industry average P/E of 16.4x. This points to investors assigning a premium compared with the sector even as the internal fair value work suggests some headroom within that premium.
Explore the SWS fair ratio for NH Foods.
Result: Preferred multiple of Price-to-Earnings of 17.1x (ABOUT RIGHT)
Still, rising input costs or weaker consumer demand for NH Foods' processed products could pressure earnings and challenge the idea that today’s P/E offers comfort.
Find out about the key risks to this NH Foods narrative.
Another View on NH Foods' Value
Price tells one story, cash flow tells another. While NH Foods looks only slightly pricey on a P/E of 17.1x, the SWS DCF model values the shares at ¥3,557.89 against the current ¥2,084. That gap points to a very different risk reward profile. Which signal do you consider more informative?
Look into how the SWS DCF model arrives at its fair value.
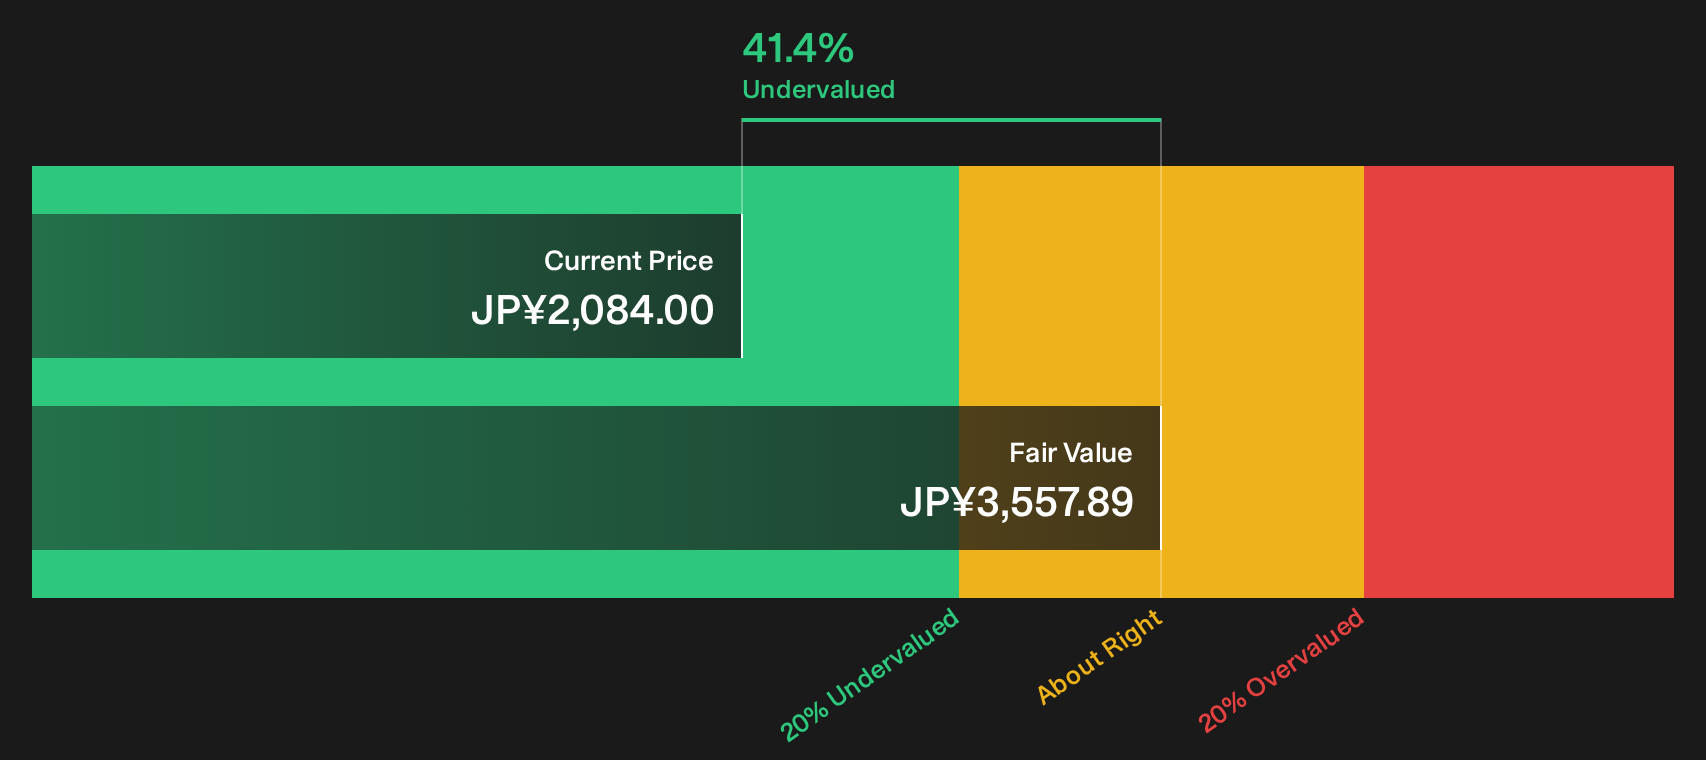
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NH Foods for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the optimism around NH Foods really holds up for you? Take a look at the key data points, weigh the trade offs, and then test that view against the 4 key rewards.
Looking for more investment ideas beyond NH Foods?
Do not stop with a single ticker when the broader market is full of opportunities that fit different risk levels and portfolio goals.
- Target potential mispricing by scanning a focused group of 14 high quality undervalued stocks that combine earnings power with supportive fundamentals.
- Strengthen portfolio resilience by filtering for a 21 resilient stocks with low risk scores that screens out weaker balance sheets and fragile cash flows.
- Get ahead of the crowd by reviewing 73 high quality undiscovered gems before they appear on every investor's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com