
How Class Action Lawsuit At Ensign Group Stock Has Changed Its Investment Story
- Robbins Geller Rudman & Dowd LLP has filed a securities class action against Ensign Group covering 2022 to mid 2026, citing allegations of systemic resident neglect, data manipulation, and misuse of Medicare and Medicaid funds that were surfaced in multiple investigative reports.
- The lawsuit directly challenges Ensign Group’s care delivery and reporting practices, raising questions about regulatory exposure, operating costs, and the resilience of its facility level business model.
- We will now look at how Ensign Group's investment narrative could be affected by the class action allegations around care standards.
Ensign Group Investment Narrative Recap
To own Ensign Group, you need to be comfortable with a facility heavy model built around Medicare and Medicaid reimbursement, steady referral flows and the gradual turnaround of lower occupancy properties. The short term bull case leans on keeping occupancy stable, staffing manageable and CMS quality metrics intact while new operations are integrated.
The class action puts that operating thesis under pressure because it targets exactly those levers, especially care standards, documentation and use of federal funds. In the near term, the biggest swing factor is how regulators, payors and referral partners respond. The key risk is higher compliance costs or constraints on reimbursement that weigh on margins.
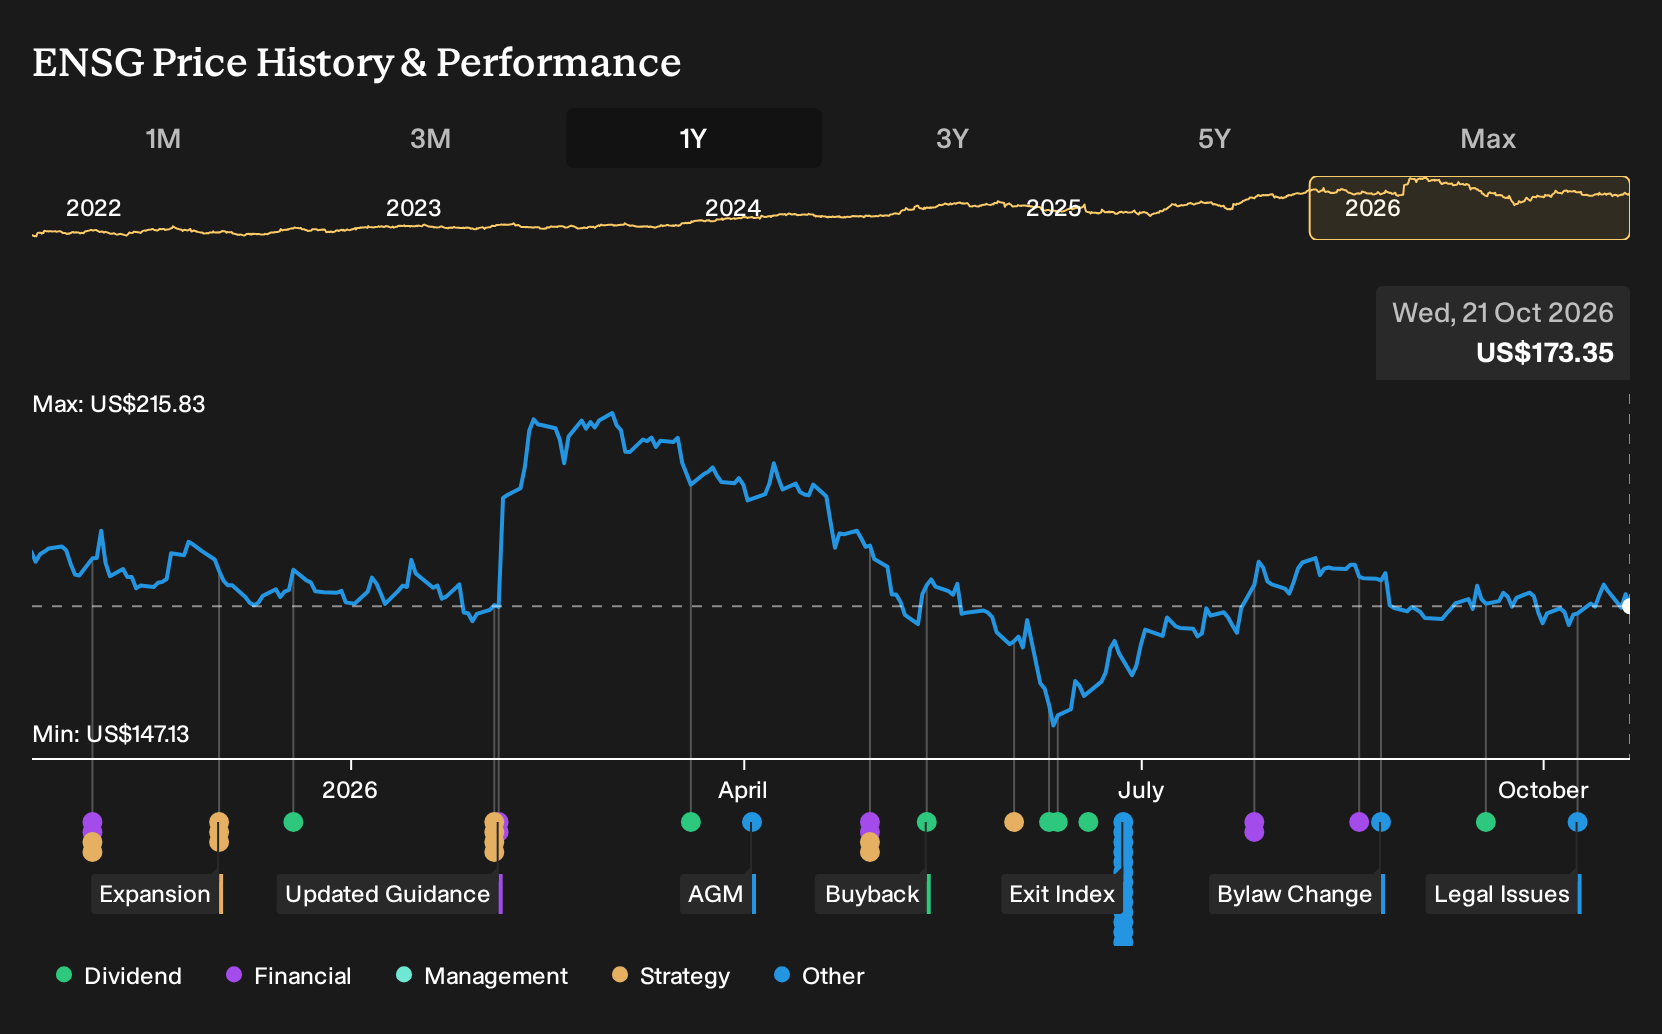
The October 2026 securities class action linked to investigative reports is the disclosure that ties most directly to this risk debate. Allegations touch on resident care, staffing hours, quality data and billing for high acuity patients, all of which sit inside Ensign Group’s core business model and its reliance on government pay programs.
For catalysts, watch whether reimbursement terms, CMS quality ratings or referral volumes change as this lawsuit progresses. Any shift here would feed through to occupancy, mix and the viability of turning around recently acquired facilities, as well as the rental coverage of assets sitting inside the Standard Bearer REIT structure.
Ensign Group's current analyst narrative points to revenue of US$7.5b and earnings of US$565.1m by 2029, based on a forecast 10.9% yearly revenue growth rate and an earnings increase of about US$186.4m from current earnings of US$378.7m.
Uncover why Ensign Group's fair value indicates a 27% potential upside to its current price, which could narrow quickly if sentiment stabilizes.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$199 and US$220, so retail opinions are already tight before the October 2026 lawsuit shock is factored in. With Ensign Group now facing legal scrutiny, reimbursement sensitivity, and heavy acquisition demands, you should expect sharply different views and explore several contrasting takes.
Explore 2 other Ensign Group fair value estimates, including one that suggests it could be worth just $198.98.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Ensign Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Ensign Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Ensign Group's overall financial health at a glance.
Looking for more investment ideas beyond Ensign Group?
If the Ensign Group story has prompted you to widen your watchlist, it can help to scan for other businesses that fit clear financial filters instead of reacting to headlines stock by stock.
- For investors hunting for quality at a discount, start by reviewing 30 high quality undervalued stocks that currently look mispriced relative to their fundamentals.
- If stability matters more to you than excitement, consider companies in the 30 resilient stocks with low risk scores that pair resilient balance sheets with lower risk scores.
- When you want strength on the balance sheet to be the foundation of your research, begin with a curated list of solid balance sheet and fundamentals (25 results) that already screen well on debt and liquidity metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com