
Amprius Technologies (AMPX) Could Be 64% Undervalued Following Its $75 Million Grant
Why Amprius Technologies Stock Is Back on Investors’ Radar
Amprius Technologies (AMPX) has drawn fresh attention after securing a $75 million Department of War grant, which signals government support for its battery technology and helps fund a planned ramp in cell production capacity.
Recent trading has been choppy. The share price is down 4.8% on the day and roughly 20.7% over the past month, while the 3-year total shareholder return of about 193% still signals a strong longer run for investors who stayed in.
That disconnect between a weaker year-to-date share price return of about 9.5% and a much stronger multi year total shareholder return helps explain why news like the Department of War grant, the universal shelf registration, and the upcoming Q3 2026 earnings call has put Amprius Technologies back under a spotlight as markets reassess both growth potential and execution risk.
Compare Amprius Technologies with a curated group of execution-focused battery and hardware plays by scanning the list of solid balance sheet and fundamentals (25 results), which may better support large contract cycles and capex ramps.
Bulls see Amprius Technologies as an execution story that is finally funded, while bears see a grant-fueled spike masking ongoing losses. Which side do the current earnings profile and valuation appear to support next?
Most Popular Narrative: 64% Undervalued
Against the last close at $7.91, the most followed valuation story for Amprius Technologies points to a fair value of about $22.13, which frames today’s pullback as a sharp discount rather than a ceiling.
The industry's increasing need for lightweight, high-energy-density battery solutions (for drones, electric aviation, and next-gen vehicles) enables Amprius to maintain premium pricing and outperform on gross and net margins due to its demonstrated product performance advantages, as evidenced by record energy density and recent customer wins (e.g., AALTO/Airbus and U.S. Army).
See why 108 investors see Amprius Technologies as 64% undervalued.
The most widely followed narrative uses a 9.21% discount rate and arrives at a fair value of $22.13 per share, compared with a market value of $7.91 and an implied 64.2% discount to that estimate. That gap reflects a view that forecast revenue expansion and a shift toward profitability are not fully reflected in the current share price.
Result: Fair Value of $22.13 (UNDERVALUED)
Still, the story breaks quickly if Amprius Technologies stumbles on scaling its silicon anode manufacturing, or if heavy reliance on aviation and drone customers causes sharp revenue swings.
Find out about the key risks to this Amprius Technologies narrative.
Another View: What Multiples Say About Amprius Technologies
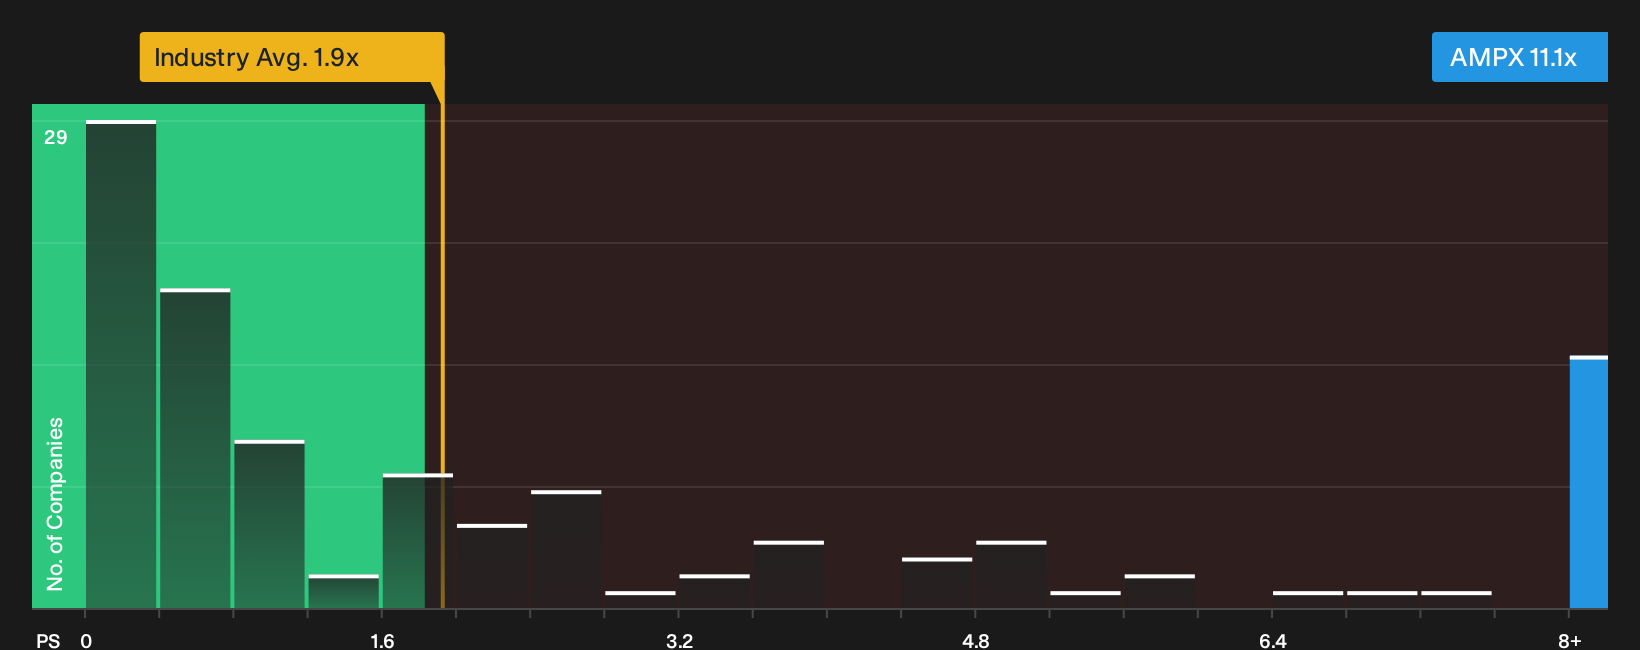
The DCF driven fair value story paints Amprius Technologies as heavily undervalued, yet the simpler snapshot using sales multiples looks far less forgiving. At a P/S of 10.6x, the stock is priced well above the US Electrical industry at 1.9x and above its own fair ratio of 4.2x.
That gap suggests investors are already paying up for a lot of future execution, while the DCF model argues there is still a wide margin of safety. Which lens do you trust more when expectations are this stretched?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Amprius Technologies can be useful if you act quickly and compare them with the company’s numbers yourself before sentiment shifts again. To see both sides laid out clearly, including the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Amprius Technologies?
If Amprius Technologies is on your watchlist, do not stop there. Broaden your opportunity set now so you are not relying on a single story.
- Target resilient compounders by scanning 30 resilient stocks with low risk scores. These aim to keep potential drawdowns in check while still giving you exposure to equity upside.
- Spot potential mispricings early by reviewing the 20 high quality undiscovered gems before wider attention drives heavier trading interest.
- Hunt for quality at a discount by working through the 30 high quality undervalued stocks and lining up candidates for your next deep dive.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com