
Richelieu Hardware (TSX:RCH) On Stronger Q3 Results Is The Stock Already Fully Valued
Richelieu Hardware (TSX:RCH) drew investor attention after reporting third quarter results on October 8, with sales of CA$562 million and net income of CA$29.24 million for the period ended August 31, 2026.
Richelieu Hardware’s earnings release landed as the share price has climbed 4.74% over the past month and 8.06% over 90 days, yet the year to date share price return has still declined 4.11%, while the 1 year total shareholder return sits at 2.18%, which may suggest improving momentum after a weaker stretch.
Scan how Richelieu Hardware compares with other industrials showing improving trends in sales and earnings by zeroing in on our hand picked list of solid balance sheet and fundamentals (7 results)
The recent rebound in Richelieu Hardware after stronger quarterly figures presents a clear decision point. Do you build on the move now, or wait for a potentially lower entry as the valuation picture becomes clearer?
Preferred P/E of 22.7x: Is it justified?
Richelieu Hardware trades on a P/E of 22.7x against a last close of CA$38.22, while earnings over the past 5 years have declined 15% per year, so the current valuation leans toward a richer side of the spectrum compared with its own profit history.
The P/E ratio links what investors pay per share to the profits the business currently generates. For a distributor and manufacturer like Richelieu Hardware, that earnings based yardstick is a quick way to see how much confidence the market is placing on steady cash generation and future profit resilience.
Management has delivered 9.2% earnings growth over the last year after several years of declining profits, and revenue is forecast to grow 5.5% per year. Yet the share price still carries a premium P/E relative to the Canadian Trade Distributors peer average of 13.6x. Against the broader North American Trade Distributors group, where the average multiple is 23.8x, the stock lines up closer. This suggests investors are pricing Richelieu Hardware more in line with regional peers than with its weaker recent long term earnings trend.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 22.7x (OVERVALUED).
Still, Richelieu Hardware relies heavily on cyclical construction and renovation demand, and any earnings disappointment at a 22.7x P/E could pressure the recent share price rebound.
Find out about the key risks to this Richelieu Hardware narrative.
Another view on Richelieu Hardware’s value
The SWS DCF model presents a different perspective compared with the 22.7x P/E. On that cash flow view, Richelieu Hardware at CA$38.22 is trading above an estimated value of CA$28.93, which frames the stock as overvalued and raises the question of how much optimism is already in the price.
Look into how the SWS DCF model arrives at its fair value.
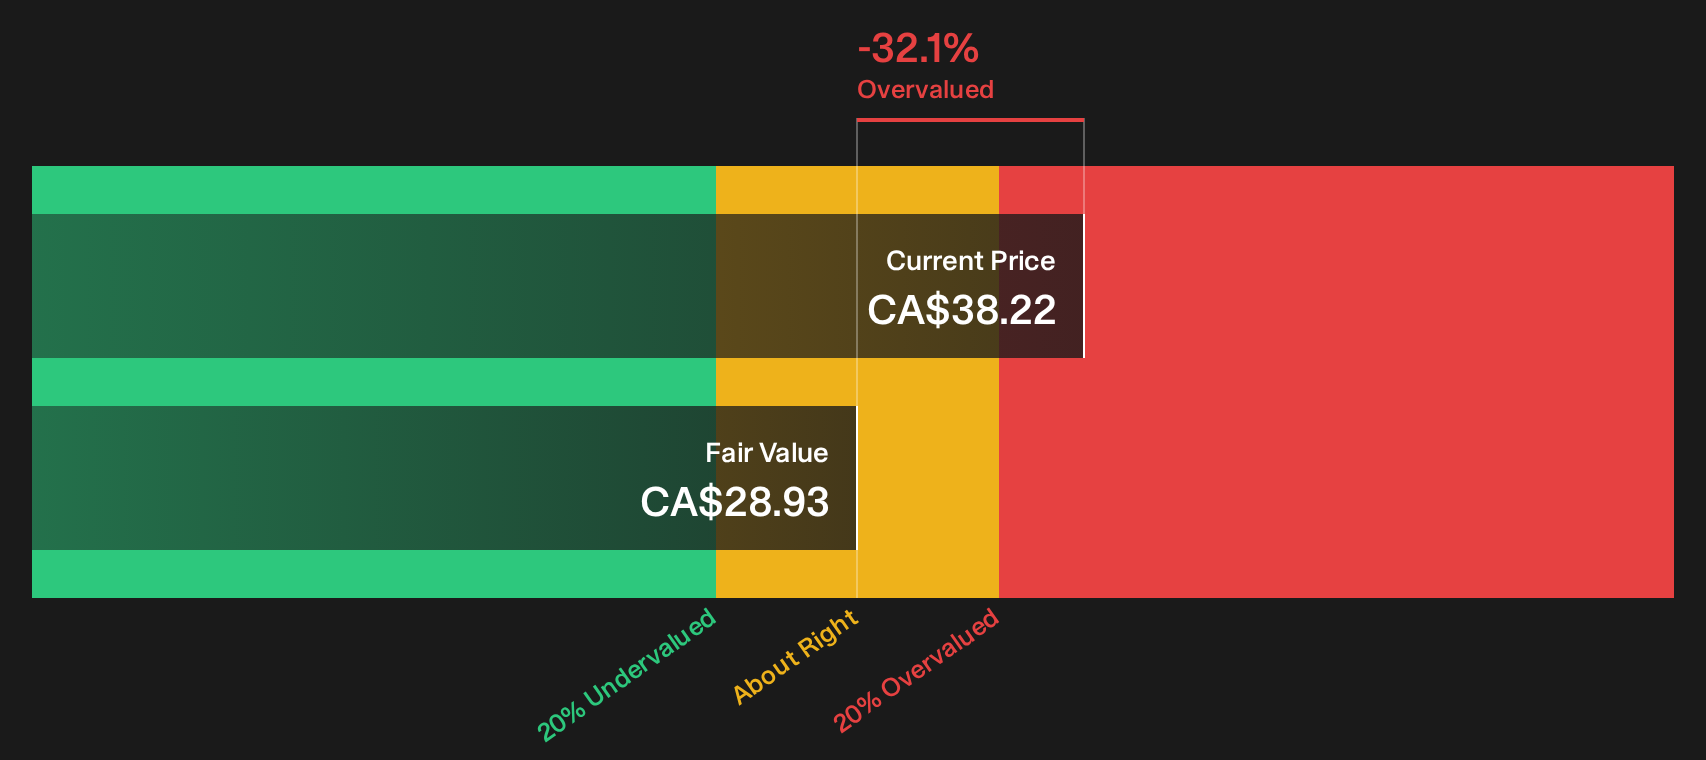
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Richelieu Hardware for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Richelieu Hardware so far. If you want a firm grip on the story, act promptly to review both the potential upside and the pressure points through the 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Richelieu Hardware?
If Richelieu Hardware feels fully priced to you, do not stop there. Broaden your watchlist and give yourself more options before the next move hits.
- Target resilience first by focusing on businesses with stronger finances using our 8 resilient stocks with low risk scores.
- Hunt for mispriced quality and see which candidates pass through the 3 high quality undervalued stocks.
- Stack potential income on top of capital growth goals by scanning the 3 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com