
Silicon Motion Technology (SIMO) Could Be 49% Below Fair Value Following Dividend Rise
Silicon Motion Technology (NasdaqGS:SIMO) has increased its annual cash dividend to US$2.30 per ADS, a 15% rise from 2025, signaling board confidence in the business after three years of strong financial performance.
The higher dividend comes after a sharp reset in Silicon Motion Technology’s share price. It has fallen about 34% over the past month and roughly 31% over 90 days, even though the year-to-date share price return is just over 100% and the 3-year total shareholder return is close to a 3x gain. This suggests that long-term holders have still seen strong value creation despite fading short-term momentum.
Scan other semiconductor income plays that are reacting to similar price swings and payout shifts with our hand picked 6 dividend fortresses.
The recent slide in Silicon Motion Technology’s share price now sits against strong multi year returns and a higher dividend. Is most of the easy upside already gone, or does the reset still leave meaningful value on the table?
Most Popular Narrative: 49% Undervalued
Against the last close of $187.96, the most followed narrative for Silicon Motion Technology anchors on a fair value of $369.70. This frames the recent pullback very differently compared with the near term price action.
The rapid expansion of high performance storage demand from AI, data centers, cloud computing, and edge computing is still fueling adoption of advanced NAND controller solutions. Silicon Motion Technology now points to PCIe Gen 5 and Gen 6 client and enterprise controllers as well as MonTitan enterprise SSD controllers as key levers for future revenue and earnings growth.
See why 63 investors see Silicon Motion Technology as 49% undervalued.
Result: Fair Value of $369.70 (UNDERVALUED)
Still, the Silicon Motion Technology story can break if tight NAND and DRAM supply continues to squeeze lower end devices and if insider selling persists against rich valuation assumptions.
Find out about the key risks to this Silicon Motion Technology narrative.
Another View: SWS DCF Model Flags Less Upside
While the Silicon Motion Technology narrative refers to a fair value of $369.70, the Simply Wall St DCF model points to a future cash flow value of $159.46 instead. That implies the recent $187.96 share price sits above this estimate, so which yardstick do you trust more for long term decisions?
Our DCF model rests on explicit cash flow assumptions, discount rates, and terminal values that can react quickly to slower growth or lower margins. Look into how the SWS DCF model arrives at its fair value.
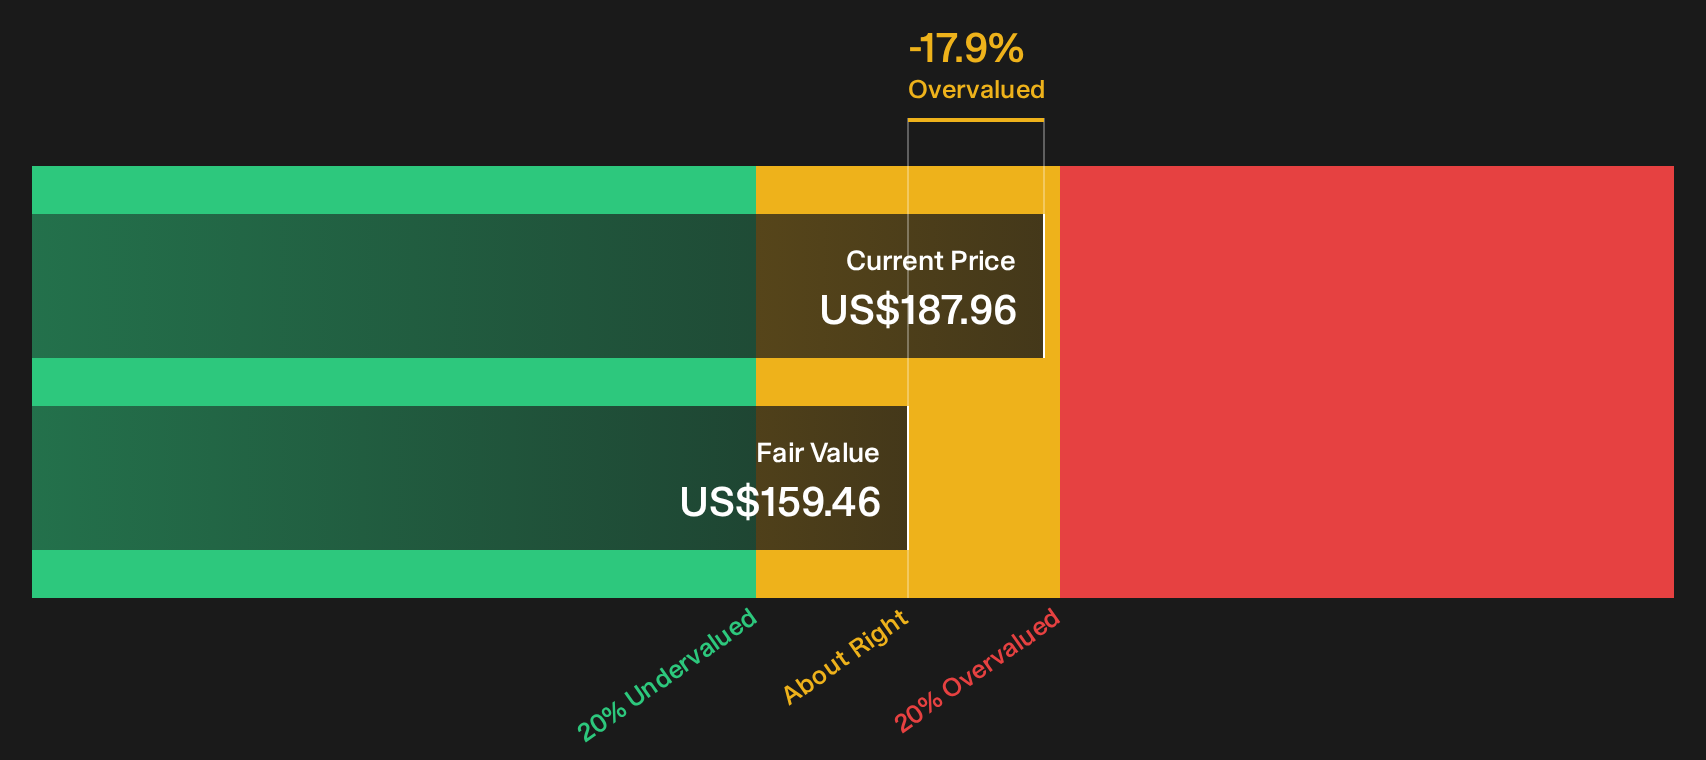
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Silicon Motion Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Silicon Motion Technology so far. Consider acting while sentiment is split and check the underlying numbers for yourself by reviewing the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Silicon Motion Technology?
You do not need to stop at Silicon Motion Technology. Broaden your watchlist with a few focused stock sets that match different goals and risk levels.
- Target sturdier balance sheets and steadier fundamentals by scanning the list of solid balance sheet and fundamentals (26 results) to help anchor a more resilient portfolio.
- Hunt for mispriced quality by reviewing the 30 high quality undervalued stocks that combine stronger fundamentals with what our models see as discounted share prices.
- Strengthen your income stream by checking the 6 dividend fortresses that combine higher yields with robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com