
Kimberly Clark (KMB) Stock May Still Look Reasonable Following Debt Deal
Kimberly-Clark shares have climbed in recent weeks, and the question now is whether that move still lines up with what its earnings can reasonably support. The stock has been active on both the news front and in trading, which puts the current valuation under a brighter spotlight.
- The share price is up 13.6% over the past month. This puts fresh pressure on the numbers to justify paying more for each dollar of Kimberly-Clark's earnings.
- Plans to acquire Kenvue, alongside a planned US$4.9b debt issue, could reshape future earnings power and interest costs. Both factors feed directly into how investors might think about the stock's earnings multiple.
- There is a second opinion on Kimberly-Clark worth weighing. See what analysts think Kimberly-Clark's shares could be worth.
For investors, the debate is whether Kimberly-Clark's current share price fairly reflects what the business is earning today and what those earnings suggest about value.
If you want more ideas that put earnings and valuation front and center, a focused stock screen is a useful second starting point alongside Kimberly-Clark's story. One option is something like 30 high quality undervalued stocks.
Is Kimberly-Clark a Bargain on Earnings?
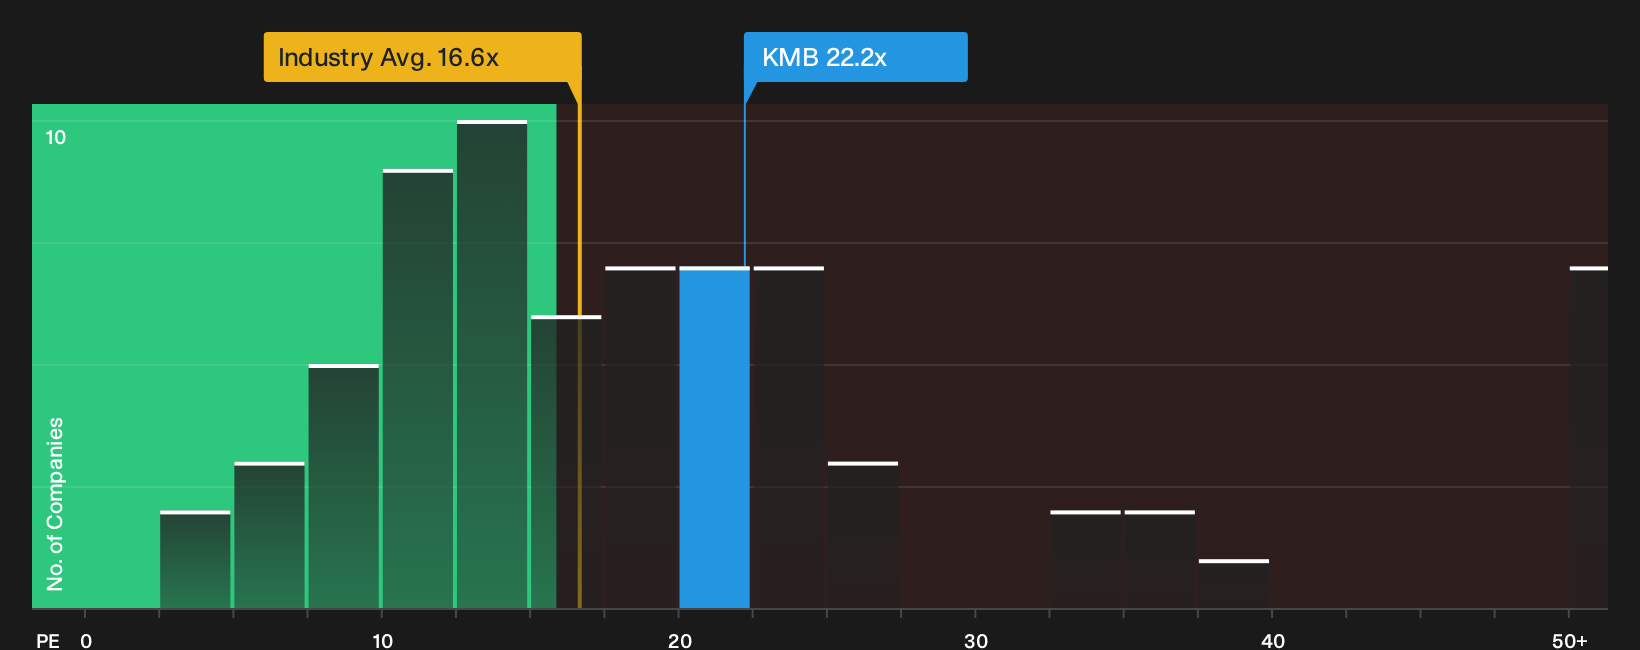
The P/E ratio fits Kimberly-Clark well because earnings are a key lens for large, mature consumer brands. On current figures, the stock trades at about 22.2x earnings. That compares to roughly 16.6x for the wider Household Products group and about 26.4x for direct peers, so the shares change hands above the broad sector but below similar-sized rivals.
The fair-value framework, which estimates the multiple you might expect given Kimberly-Clark's size, margins and risk profile, points to a higher P/E than where the stock trades today. Because the planned Kenvue acquisition and the US$4.9b debt funding have already sharpened market focus on earnings power, the current discount to this tailored benchmark suggests investors are still pricing in some caution rather than paying up for the full earnings outlook. Explore the numbers behind Kimberly-Clark's P/E valuation.
The Kimberly-Clark Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Kimberly-Clark pick up where the P/E puzzle leaves off by explaining which future paths for growth, margins and earnings would need to occur for today’s valuation to look stretched or conservative. Each scenario links a fair value estimate to a clear storyline about Kimberly-Clark's potential catalysts and key risks, enabling you to track over time which version of events appears to be taking shape on the Community page.
Community views on Kimberly-Clark are split between investors who see more potential in the earnings story and others who are wary of execution risk around Kenvue.
Bull case: roughly fairly valued
"Disciplined cost management remains central as Kimberly-Clark reports more than 6% gross productivity savings as a share of adjusted COGS and embeds AI enabled procurement..."
Discover why this Narrative puts Kimberly-Clark at roughly fairly valued.
Bear case: 25% overvalued
"Intensifying competition from private label and low-cost imports in core diaper markets could cap pricing power and limit revenue growth as consumers remain value focused..."
Explore why this Narrative puts Kimberly-Clark at 25% overvalued.
The open question for Kimberly-Clark that valuation alone does not answer
Price and earnings only tell part of the story for Kimberly-Clark, since separate checks have raised specific concerns that could change how you weigh everything you have just read. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com