
Flex Earnings Preview: What to Expect
With a market cap of $31.9 billion, Flex Ltd. (FLEX) is a global manufacturing and supply chain solutions provider operating across 30 countries, helping leading brands design, build, and manage products through advanced manufacturing, innovative technologies, and lifecycle services. In the AI era, the company is supporting the rapid expansion of data centers with advanced power and cooling technologies and scalable IT infrastructure solutions.
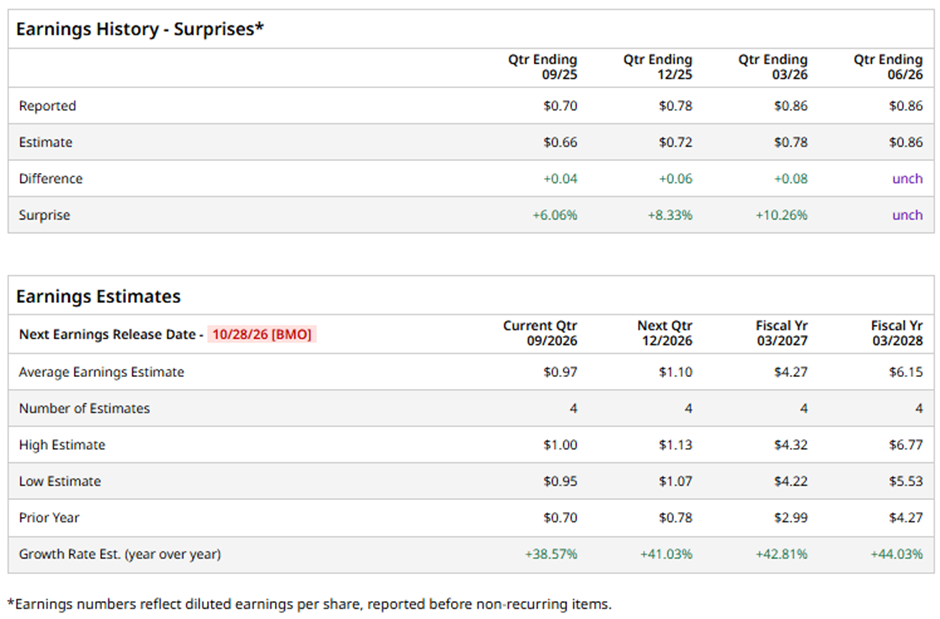
The Austin, Texas-based company is slated to announce its fiscal Q2 2027 results before the market opens on Wednesday, Oct. 28. Ahead of the event, analysts expect FLEX to report a profit of $0.97 per share, a 38.6% increase from $0.70 per share in the year-ago quarter. It has exceeded or met Wall Street's earnings expectations in each of the past four quarters.
For fiscal 2027, analysts forecast FLEX to post EPS of $4.27, a surge of 42.8% from $2.99 in fiscal 2026. In addition, EPS is anticipated to grow 44% year-over-year to $6.15 in fiscal 2028.
Shares of FLEX have increased 25% over the past 52 weeks, outpacing the broader S&P 500 Index's ($SPX) 14.4% gain . However, the stock has lagged behind the State Street Technology Select Sector SPDR ETF's (XLK) 27.7% return over the same period.
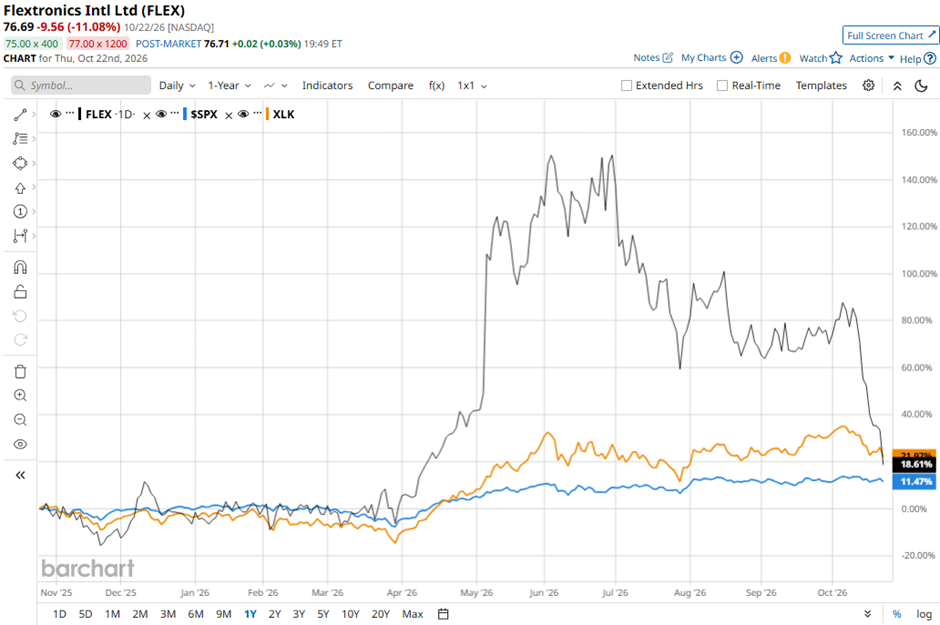
Flex shares tumbled 9.1% on Jul. 29 despite fiscal Q1 2027 results beating expectations, with adjusted EPS of $1 and revenue of $7.9 billion, representing year-over-year growth of approximately 24.8% and 14.3%, respectively. The sell-off was driven by fiscal 2027 guidance of $4.42 - $4.74 in EPS versus the $4.53 consensus and $33.70 billion - $35.20 billion in revenue versus the $33.41 billion consensus.
Investor concerns were compounded by a major leadership reshuffle linked to the planned separation of its Cloud and Power Infrastructure business in Q1 2027, creating uncertainty over execution and the strategic direction of the remaining company.
Analysts' consensus view on FLEX stock remains bullish, with a "Strong Buy" rating overall. Out of 12 analysts covering the stock, 10 recommend a "Strong Buy," one "Moderate Buy," and one gives a "Hold" rating. The average analyst price target is $157.82, suggesting a potential upside of 105.8% from current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.