
NIKE (NKE) Faces A Tough Turnaround, Is The Stock Fairly Valued?
Nike (NKE) is back in focus after fresh signals that its turnaround is proving difficult, with pressure on consumer demand, weakness in Greater China, and restructuring moves aimed at Converse and the digital business.
In the short term, NIKE shares have bounced, with a 1-day share price return of 2.10% and a 30-day share price return of 6.15%. However, momentum still looks weak given the 90-day share price decline of 8.11% and a 1-year total shareholder return that is down 43.19%.
Compare Nike's troubled turnaround with other consumer stocks that currently screen stronger on cash flow and balance sheet quality by reviewing the list of solid balance sheet and fundamentals (26 results).
Bulls see a bruised Nike with durable brands and cost cuts that could re-rate the shares. Bears see a premium tag on shrinking appeal and earnings. Which story does the current valuation back up?
Most Popular Narrative: 6.5% Undervalued
The most followed narrative on Nike compares a fair value of about $41.00 to the recent $38.32 share price, which points to modest undervaluation while still treating this as a turnaround rather than a growth story.
The core of the case is simple. At about $32, the market is paying roughly what Nike's stable-era earning power is worth with zero growth (about $32 a share). A buyer gets the brand's return to growth for free, but only if margins recover.
See why 34 investors see NIKE as 7% undervalued.
According to ANTONI0, the fair value relies on Nike gradually returning to the operating margins it earned in its more stable years rather than re-rating as a high growth compounder again. That view leans heavily on Nike's high quality earnings today, a current return on equity of 20.3%, and forecasts that return on equity could be 24.3% in three years, while still accepting relatively low forecast earnings and revenue growth compared with the wider US market.
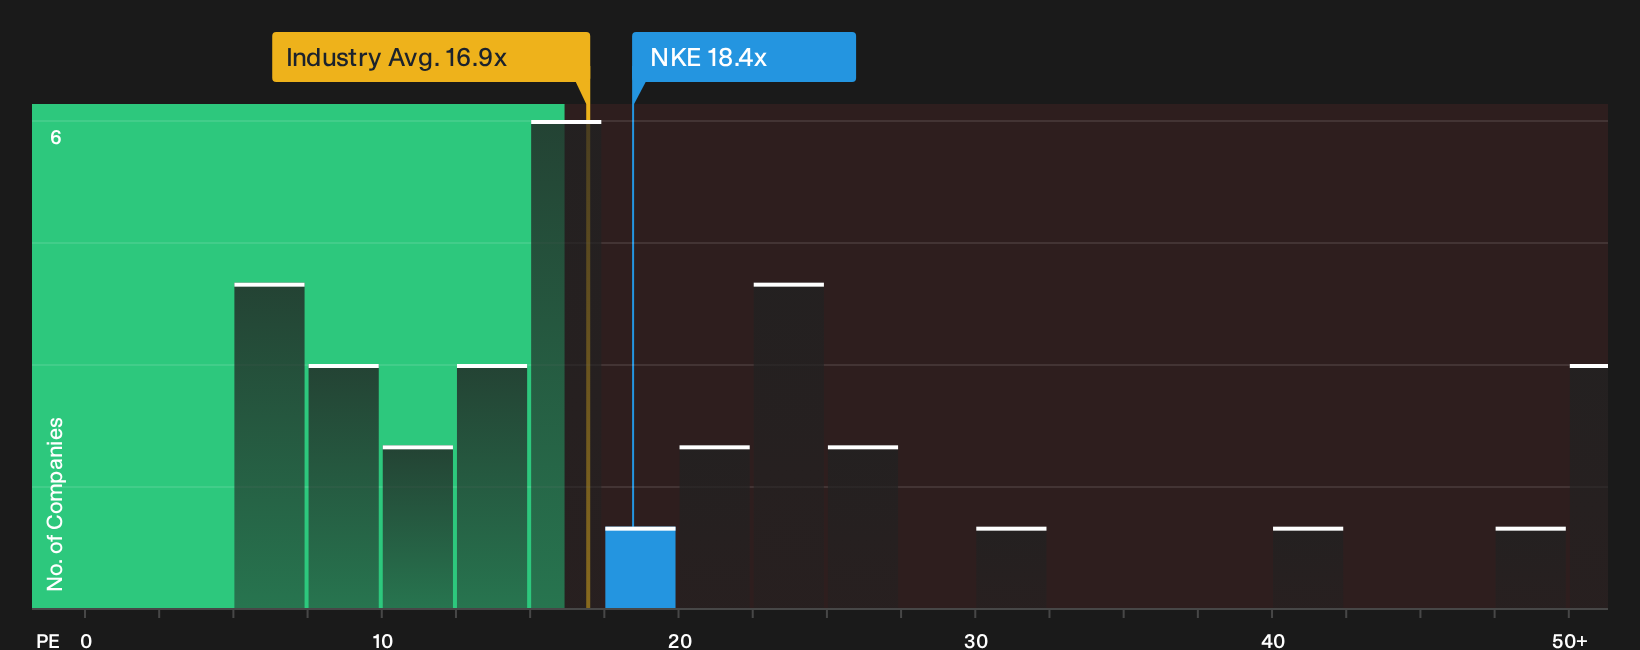
The narrative also squares an apparent contradiction in the data. On one side, Nike is trading 6.9% below the internal fair value estimate and below an SWS DCF value of $41.17. On the other, the stock changes hands at a P/E of 18.4x, which is higher than both the US Luxury industry average of 16.9x and the peer average of 15.2x, and slightly above an estimated fair P/E of 17.7x. In other words, the market is assigning a premium multiple to earnings that have fallen over five years and are forecast to grow slowly, yet that premium still leaves the shares modestly below intrinsic value on cash flow and earning power assumptions.
For readers weighing that tension, the key swing factors are clear in the data. Earnings have declined by 15.9% per year over the past five years, even though they grew 6.8% in the last year, and that recent growth is still behind the Luxury industry. Forecast earnings growth of 0.6% a year and revenue growth of 0.5% a year are both slower than the US market. Dividend yield is 4.28%, but payouts are not well covered by free cash flow, and analysts currently have a price target of $36.50, which sits below the last close. The narrative essentially asks whether high quality earnings, strong return on equity and an experienced board can offset a newer management team, higher CEO pay and slower growth to justify a modest discount to estimated fair value.
Result: Fair Value of $41.00 (UNDERVALUED)
Still, Nike’s story can break if Greater China keeps shrinking or if dividend payouts continue to exceed free cash flow and put pressure on the balance sheet.
Find out about the key risks to this NIKE narrative.
Another Take On NIKE's Valuation
The fair value work above leans on cash flows and earning power. Using a simple P/E check, NIKE looks less generous. The stock trades at 18.4x earnings, compared with 16.9x for the US Luxury group and 15.2x for peers, while the fair ratio is 17.7x. That richer tag on slower earnings and revenue forecasts raises a different question: Is the slight discount to intrinsic value worth paying up on the headline multiple?
See what the numbers say about this price with our valuation breakdown, then compare how it lines up with your own expectations for NIKE's turnaround path See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around NIKE's prospects are clear, so act while sentiment is this divided and weigh both sides yourself with the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Nike?
If NIKE’s mixed signals leave you cautious, keep building your watchlist with other opportunities that line up better with your risk appetite and return goals.
- Target resilient compounders that pair healthy balance sheets with disciplined capital allocation by scanning our 30 resilient stocks with low risk scores.
- Hunt for potential mispriced opportunities where fundamentals and valuation both look appealing by reviewing the 30 high quality undervalued stocks.
- Go after income ideas that aim for strong yields with solid backing by checking the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com