
Underdog Deal Could Alter The Investment Case For IG Group Holdings (LSE:IGG)
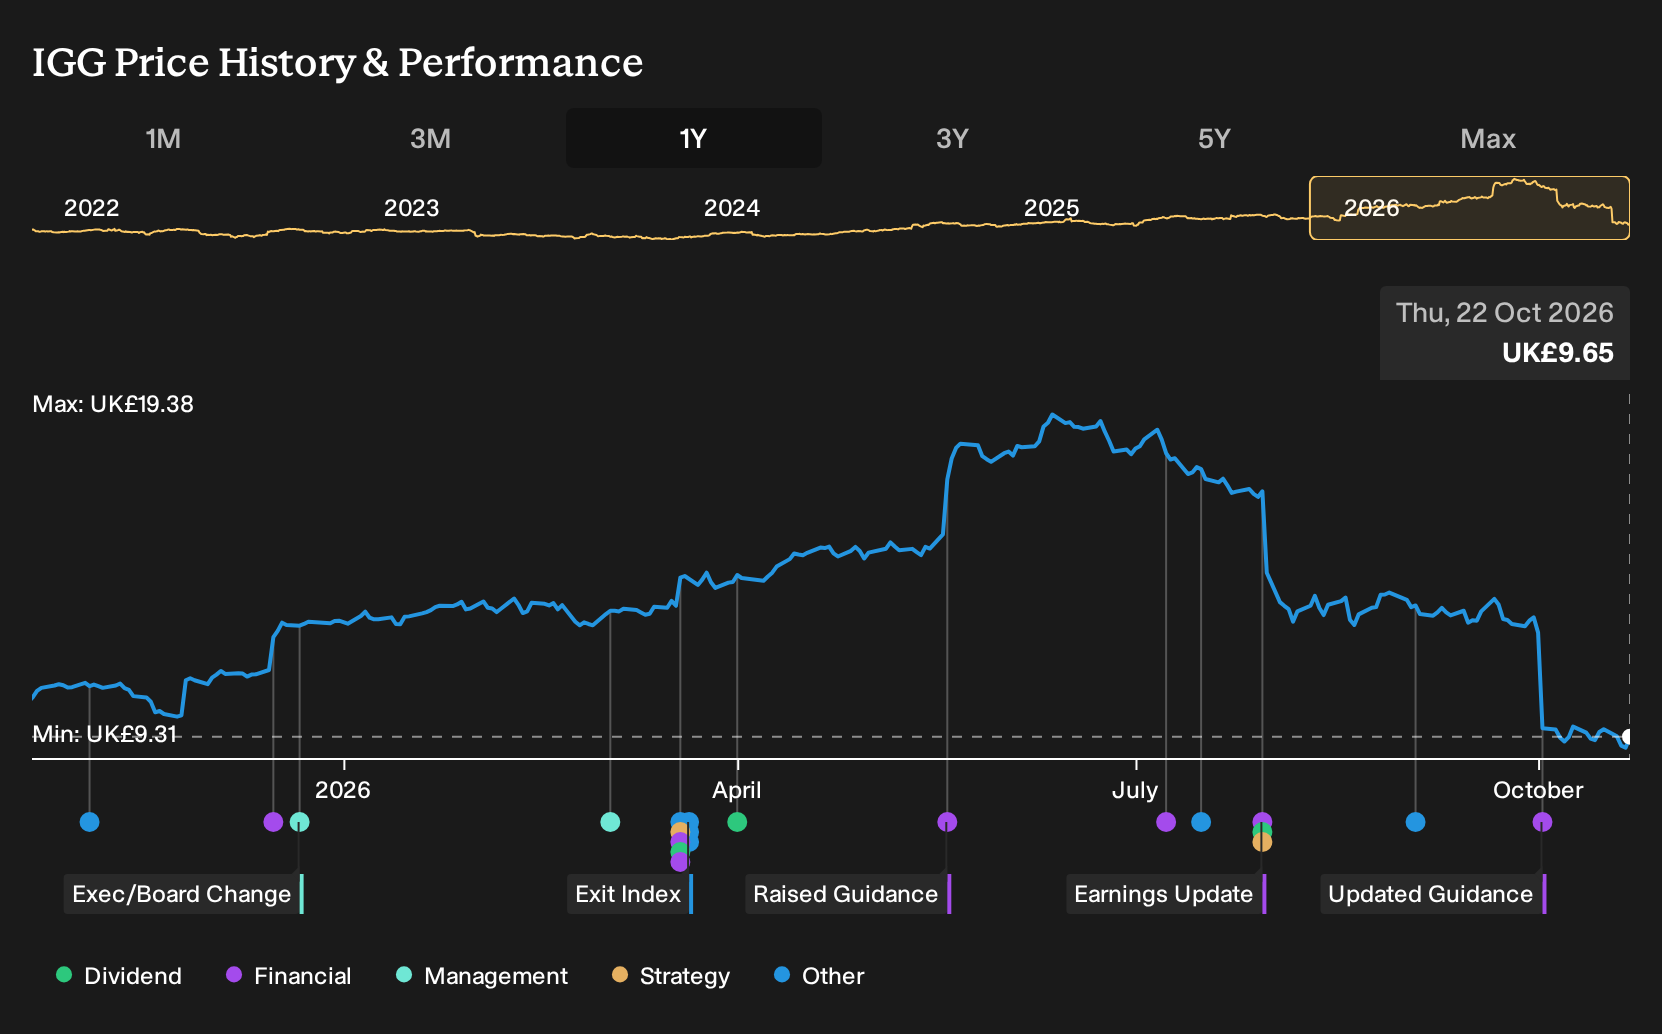
- IG Group Holdings outlined a plan to diversify beyond its U.K. focused over the counter trading business, including a proposed Underdog acquisition, expansion into prediction markets and broader trading products, and efficiency efforts such as roughly 30% workforce reductions in IG Consumer while keeping 2026 revenue and EBITDA margin guidance unchanged.
- The push to grow tastytrade and Underdog in the U.S., paired with cost cuts and product expansion, highlights IG Group’s attempt to rebalance its earnings mix toward a wider set of trading, investing and entertainment style activities.
- We will now see how IG Group Holdings’ investment narrative could shift as it leans on U.S. expansion through tastytrade and Underdog.
Benchmark IG Group Holdings’ push into trading and entertainment style investing against a curated set of resilient peers with the 4 resilient stocks with low risk scores that combines stronger balance sheets with lower risk scores.
IG Group Holdings Investment Narrative Recap
To own IG Group Holdings today, you need to believe the business can shift from a U.K. heavy over the counter engine to a broader mix built around tastytrade, Underdog and multi asset platforms, without losing its discipline on margins. The recent update, which keeps 2026 revenue and EBITDA margin guidance intact despite big changes in the operating model, suggests management sees that transition as manageable in the near term.
The key short term catalyst is whether U.S. expansion through tastytrade and the proposed Underdog deal can build on recent active customer and earnings momentum while cost cuts land cleanly. The biggest immediate risk sits in execution and regulation, especially if softer over the counter revenue retention persists or U.S. prediction market rules tighten further.
The proposed acquisition of Underdog, at a fixed upfront enterprise value of US$1.1b funded with both new equity and debt, is the clearest recent announcement tying directly into this shift for IG Group Holdings. It would push pro forma gross leverage close to 2x EBITDA and pause share buybacks until at least 2027, so investors are being asked to accept a more geared balance sheet in exchange for a bigger addressable market.
Operationally, the attraction is Underdog’s growth in net revenue to US$466m in the 12 months to June 2026 and its fully integrated FCM, DCM and DCO stack, which is already live and keeps more economics in house. The flip side is higher sensitivity to U.S. regulatory outcomes, including state level scrutiny that has already led to surrendered daily fantasy sports licences, and the risk that integration drags on margins if volumes do not scale as expected.
IG Group Holdings’ current analyst storyline points to revenues of £1.7b and earnings of £542.4m by 2029, built on 12.5% yearly revenue growth and an earnings increase of about £48.8m from £493.6m today.
Uncover how IG Group Holdings' fair value indicates a 58% potential upside to its current price, which could narrow quickly if sentiment swings back toward IG Group Holdings.
Exploring Other Perspectives
One alternate angle on IG Group Holdings focuses less on Underdog risk and more on how bullish analysts leaned into product breadth. They were modelling revenue of about £2.2b and earnings near £566.1m by 2029, before this update. That is a much more upbeat story, and today’s news may push forecasts in either direction.
Explore 4 other IG Group Holdings fair value estimates, including one that suggests as much as 107% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your IG Group Holdings research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for IG Group Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IG Group Holdings' overall financial health at a glance.
Looking For More IG Group Holdings Style Ideas?
If the IG Group Holdings story has you thinking about portfolio balance and fresh opportunities, it can help to line it up against other companies with different strengths. The Simply Wall St Screener lets you move from this single stock to a broader watchlist built around the traits you care about most, whether that is quality, resilience, or income.
- For investors who want steadier profiles and tighter risk controls, start by scanning a curated set of resilient companies through the 4 resilient stocks with low risk scores to see which ones best complement your existing holdings.
- If potential mispricing is what interests you, anchor your search around fundamentals and valuations using the 7 high quality undervalued stocks and see which candidates look worth a closer read.
- For those who care most about dependable income, filter for higher yielding payouts with the 4 dividend fortresses and build a shortlist that fits your approach to cash flow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com