
Waste Management (WM) Could Be 6% Undervalued On Earnings Growth Hopes
Upcoming earnings put Waste Management in focus
Investor attention has zeroed in on Waste Management (WM) ahead of its upcoming quarterly report, with expectations for earnings of $2.18 per share and projected revenue of $6.8 billion.
Analysts also expect stronger net operating contributions from the Renewable Energy and Recycling Processing and Sales units. This places additional emphasis on how these segments shape the story for the wider business.
Recent trading has been strong for Waste Management, with a 1-day share price return of 4.15% and a 30-day share price gain of 15.13% taking the stock to $239.10. That short-term momentum sits alongside a 1-year total shareholder return of 12.49% and a 5-year total shareholder return of 64.27%. This indicates that investors have been rewarded over time, while expectations around the upcoming earnings and segment performance continue to shape sentiment.
Scan beyond Waste Management and see how other potential earnings movers line up on quality and momentum using our hand picked 30 high quality undervalued stocks as a comparison set.
After a sharp move that has pushed Waste Management close to analyst targets, the real puzzle now is whether investors still have meaningful upside ahead or if most of the easy gains are already in the rear view mirror.
Most Popular Narrative: 6% Undervalued
On Simply Wall St, the prevailing narrative pegs Waste Management’s fair value at $253.84, a shade above the last close at $239.10. This frames upcoming earnings against a market that already prices in a lot of good news but not the full narrative fair value.
The main thing that has to go right is that Waste Management turns its large investments in healthcare solutions, recycling automation and renewable natural gas into sustained cross sell, synergy capture and free cash flow conversion now that major capex is largely complete.
The current valuation implies the share price does not fully reflect a business that is growing operating EBITDA, expanding margins, lifting free cash flow conversion toward the high 40s% to low 50s% range and benefiting from scarce disposal and energy assets.
See why 94 investors see Waste Management as 6% undervalued.
Result: Fair Value of $253.84 (UNDERVALUED)
Still, the Waste Management story can change quickly if renewable fuel tax credits fade, while volumes in core Collection and Disposal remain under pressure.
Find out about the key risks to this Waste Management narrative.
Another view on Waste Management’s valuation
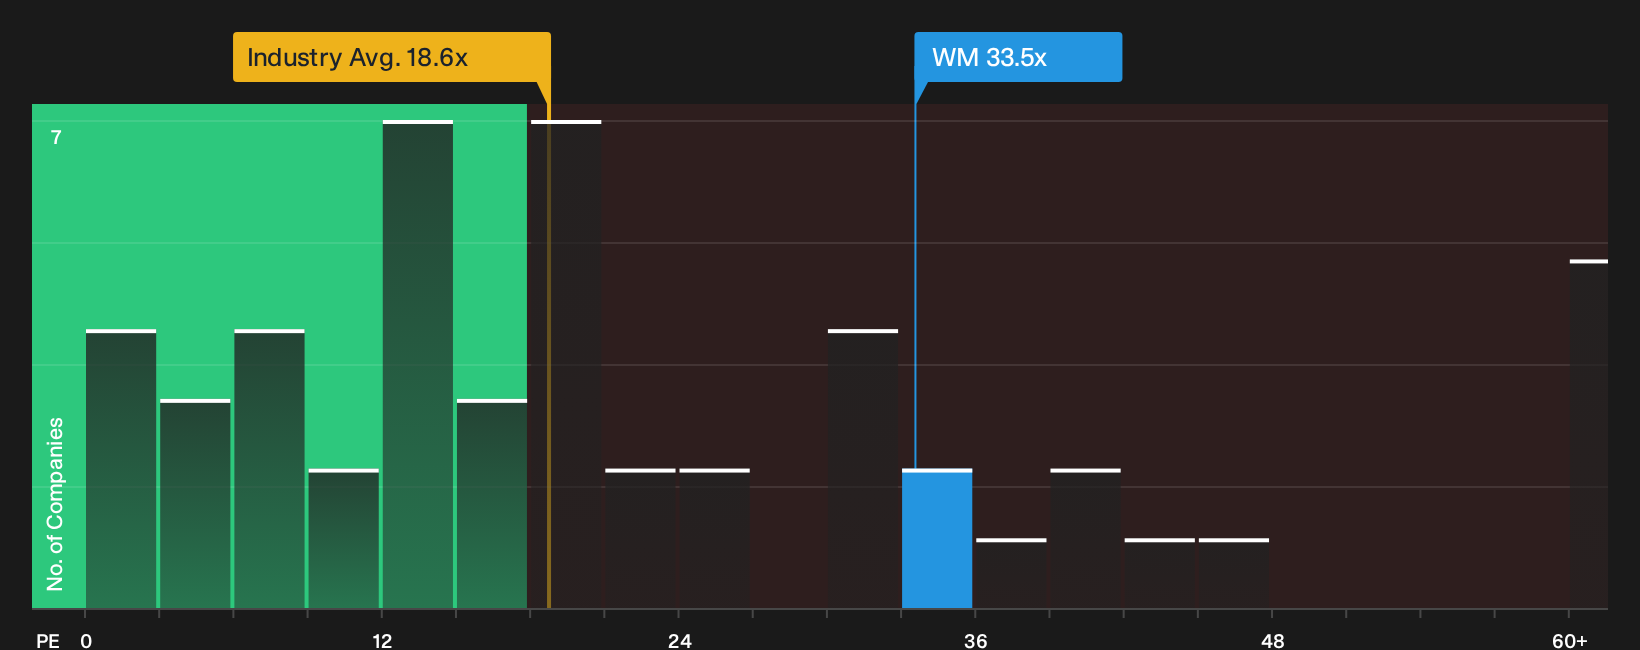
The story changes once price is compared with earnings. Waste Management trades on a P/E of 33.5x, while the US Commercial Services industry sits at 18.6x and the fair ratio is 26.9x. That gap points to richer pricing and raises a simple question: How comfortable are you paying up for quality here?
To see how that earnings multiple stacks up in more detail, including where it sits against peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Waste Management setup feels finely balanced between optimism and caution, treat that as your cue to test the numbers yourself and move fast on your own view using 4 key rewards and 1 important warning sign
Looking for more Waste Management style investment ideas?
If Waste Management has you thinking about what else might fit your portfolio, do not stop here. Broader ideas often show up where most investors are not looking.
- Target dependable income streams by reviewing a focused list of potential high yield payers through the 6 dividend fortresses.
- Hunt for businesses with strong balance sheets and steady fundamentals using the list of solid balance sheet and fundamentals (26 results) before they draw wider attention.
- Spot potential future leaders that still fly under the radar by scanning the 20 high quality undiscovered gems right now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com