
What Has Changed For Real Matters Since Its 58% Fall
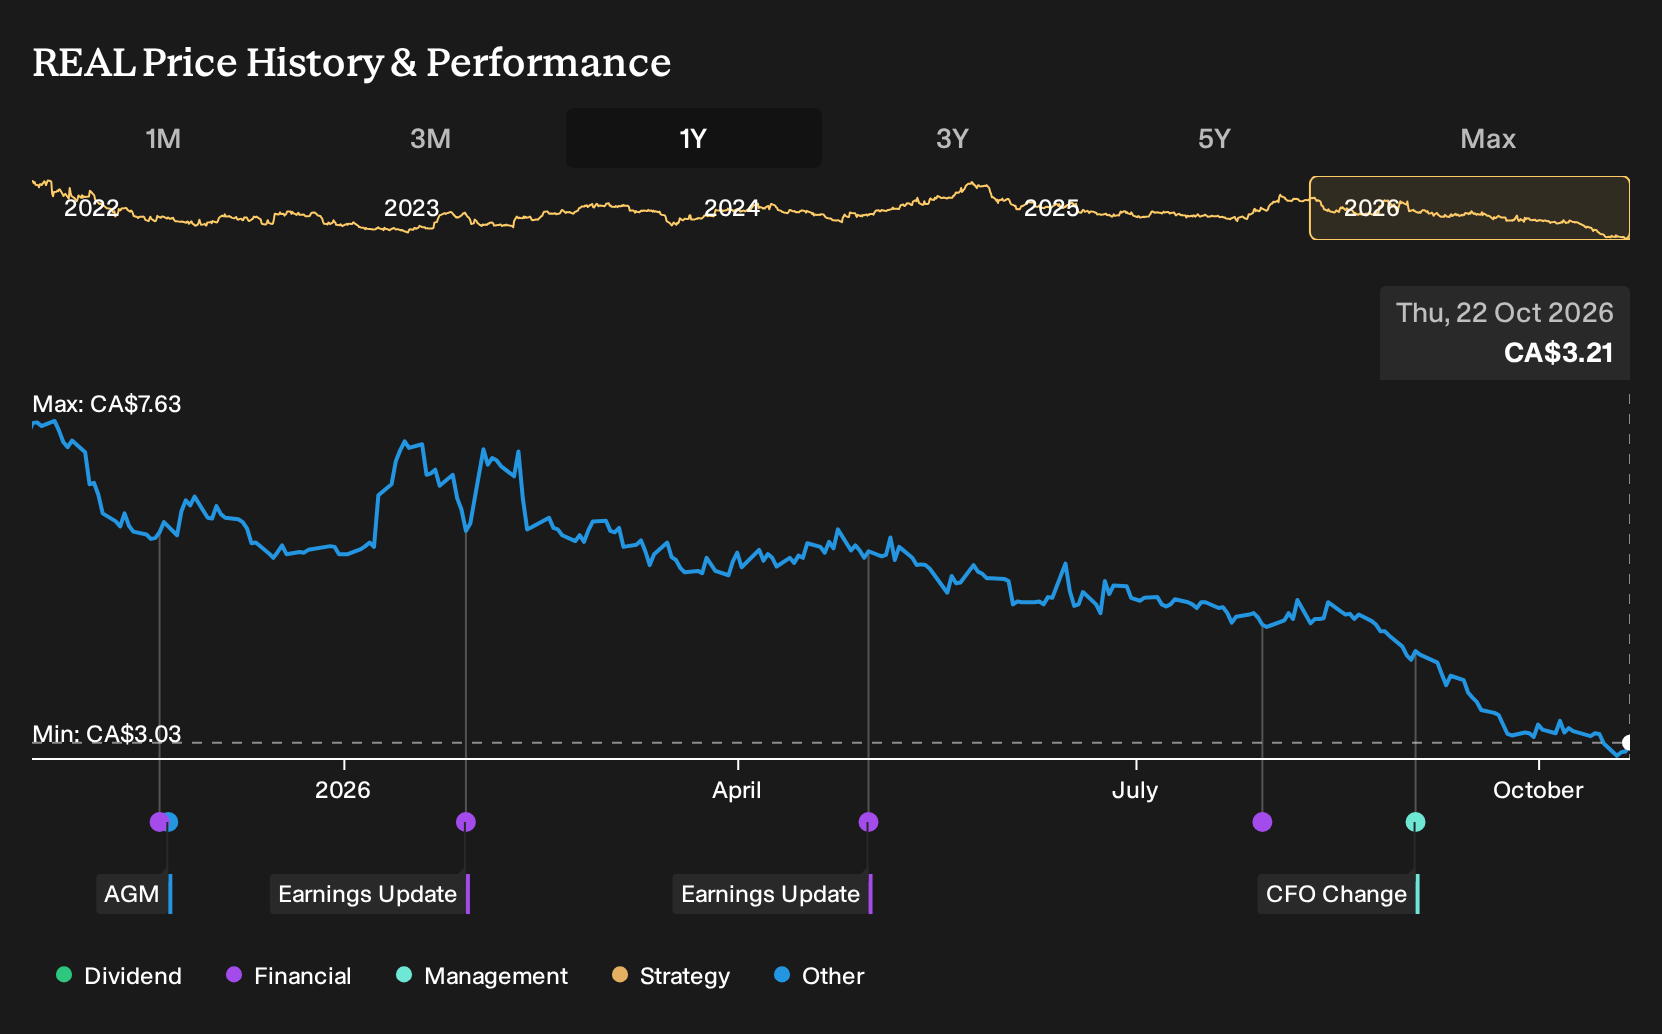
If you had scanned Real Matters in late 2025 and decided to sit it out, that choice would have spared you a heavy hit. Holding Real Matters over the past year would have meant a 57.8% loss, including dividends. Since then, quarterly revenue and profit information has arrived, along with a scheduled Q3 2026 results release, giving fresh data to interpret. What early warning or fragile assumption in the original bullish and cautious cases could you have stress tested before any of that played out?
The easy part of this move is behind Real Matters. Zero in on 3 high quality undervalued stocks for companies trading below our estimates.
The Two Real Matters Stories Investors Were Choosing Between
The shares cost CA$7.6 at the start of the period, and Real Matters sat between two plausible stories that tried to price the same digital mortgage future.
In the bullish version, a Fair Value of CA$10.95 was treated as the price implied if Real Matters captured Millennial and Gen Z demand with 23.3% annual revenue growth and profit margins rising toward 9.5%.
The more cautious script pointed to a Fair Value of CA$7.18, assuming 19.6% yearly top line growth, margins improving from a loss to 8.3%, and ongoing client concentration risk with major U.S. lenders.
What The Results Changed For Real Matters
The clearest new datapoint was Real Matters’ Q3 2026 report. Revenue was US$51.468m compared with US$45.441m a year earlier, and net income moved from a US$4.854m loss to a US$1.019m profit, lifting net margin from a 10.7% loss to 2.0%. That shift toward profitability supported the optimistic case, although margins remained far below the bullish 8% to 10% destination.
The lesson is simple. When a story leans on margin expansion, treat net margin as the key checkpoint and track whether each quarter moves that figure toward, or away from, the original target.
What Real Matters’ Lower Price Is Really Asking You
Real Matters trades at CA$3.21 today, well below the period starting point and with this Narrative’s Fair Value sitting above the current price rather than below it. The argument hinges on whether expanding Tier 1 relationships and a positive adjusted EBITDA run can eventually outweigh heavier platform and AI spending.
For the recent fall to look like an opening instead of a warning, a buyer today would need to believe that U.S. Title and U.S. Appraisal can convert current client wins and technology investment into durable segment profitability despite higher operating costs.
"Real Matters needs U.S. Title to convert its growing base of Tier 1 and nonbank clients, higher transaction volumes and high net revenue margins into sustainable segment level profitability, while managing higher corporate operating expenses from AI and platform spending."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Real Matters And A Wider Map
Real Matters is trying to digitize mortgage work. You could also scan one step sideways.
Behind those digital closings, professionals still need reliable property data and marketing hubs. Another operator concentrates on building those information networks and marketplaces.
It supplies real estate players with detailed listings, analytics and transaction tools across several regions. Those platforms help users decide where to invest, lease, build or advertise.
As more activity shifts online, that shared data grid can deepen its role inside real estate workflows. The open question is how much value eventually gathers around it.
One Narrative has already put a figure on it. → Uncover the company trading 32% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com