
Here's Why We're Watching BrainCool's (STO:BRAIN) Cash Burn Situation
Just because a business does not make any money, does not mean that the stock will go down. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
So should BrainCool (STO:BRAIN) shareholders be worried about its cash burn? In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. Let's start with an examination of the business' cash, relative to its cash burn.
How Long Is BrainCool's Cash Runway?
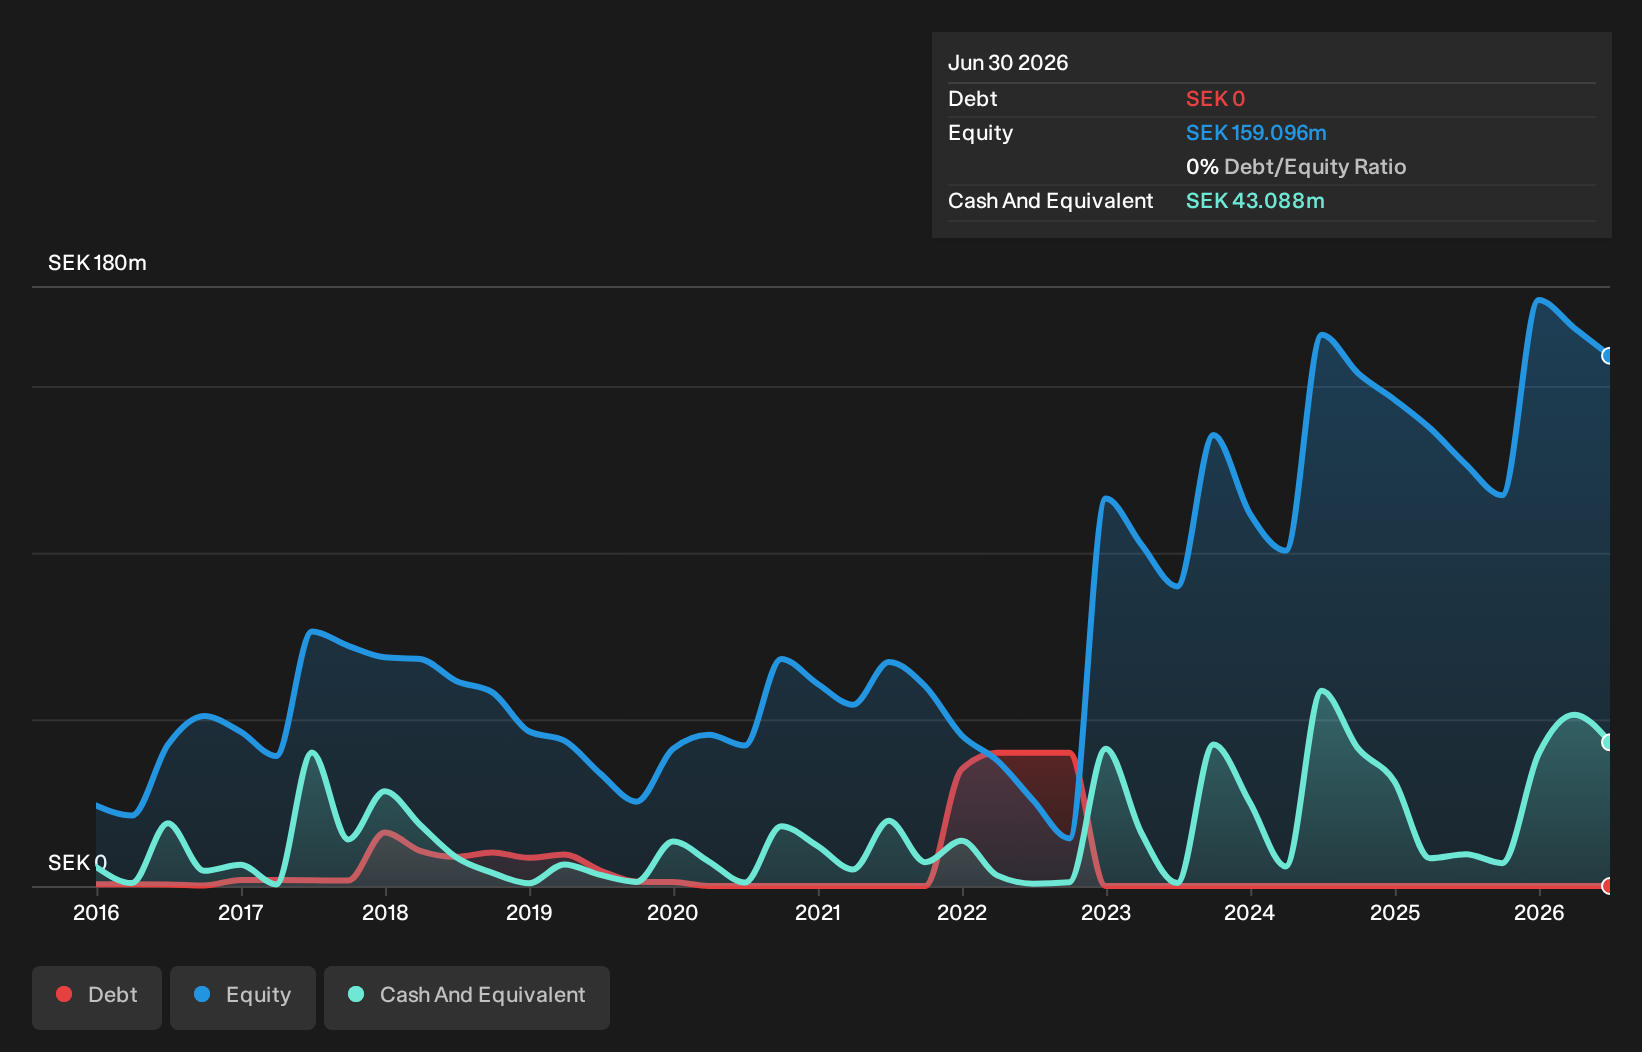
A company's cash runway is calculated by dividing its cash hoard by its cash burn. As at June 2026, BrainCool had cash of kr43m and no debt. Looking at the last year, the company burnt through kr52m. So it had a cash runway of approximately 10 months from June 2026. That's quite a short cash runway, indicating the company must either reduce its annual cash burn or replenish its cash. We should note, however, that if we extrapolate recent trends in its cash burn, then its cash runway would get a lot longer. Depicted below, you can see how its cash holdings have changed over time.
View our latest analysis for BrainCool
How Well Is BrainCool Growing?
BrainCool reduced its cash burn by 11% during the last year, which points to some degree of discipline. And operating revenue was up by 6.5% too. On balance, we'd say the company is improving over time. Clearly, however, the crucial factor is whether the company will grow its business going forward. So you might want to take a peek at how much the company is expected to grow in the next few years.
Can BrainCool Raise More Cash Easily?
Since BrainCool revenue has been falling, the market will likely be considering how it can raise more cash if need be. Companies can raise capital through either debt or equity. Commonly, a business will sell new shares in itself to raise cash and drive growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
BrainCool has a market capitalisation of kr395m and burnt through kr52m last year, which is 13% of the company's market value. Given that situation, it's fair to say the company wouldn't have much trouble raising more cash for growth, but shareholders would be somewhat diluted.
So, Should We Worry About BrainCool's Cash Burn?
On this analysis of BrainCool's cash burn, we think its cash burn relative to its market cap was reassuring, while its cash runway has us a bit worried. We don't think its cash burn is particularly problematic, but after considering the range of factors in this article, we do think shareholders should be monitoring how it changes over time. Separately, we looked at different risks affecting the company and spotted 6 warning signs for BrainCool (of which 1 can't be ignored!) you should know about.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.