
Core Scientific (CORZ) Stock Looks Rich Despite A 32% Slide
Core Scientific has had a rough stretch on the market recently, which puts a spotlight on what investors are actually paying for each dollar of its sales. With the share price under pressure, the key issue is how firmly its current revenue base supports where the stock trades today.
- The stock is down 31.7% over the past year, which puts more weight on whether its sales can justify even this lower valuation level.
- Fresh attention on long term capacity reservations with AMD and the revenue exposure to CoreWeave can influence how quickly Core Scientific converts its infrastructure into sales and how concentrated that top line remains.
- The analysts covering Core Scientific have run their own numbers. See what analysts think Core Scientific's shares could be worth.
The stock's next move may depend on whether Core Scientific's current price still lines up with the scale and resilience of its sales base.
If you are weighing Core Scientific against other AI infrastructure plays tied to chips, capacity and data centers, a focused screen of 55 AI infrastructure stocks.
Is Core Scientific Getting Expensive on Sales?
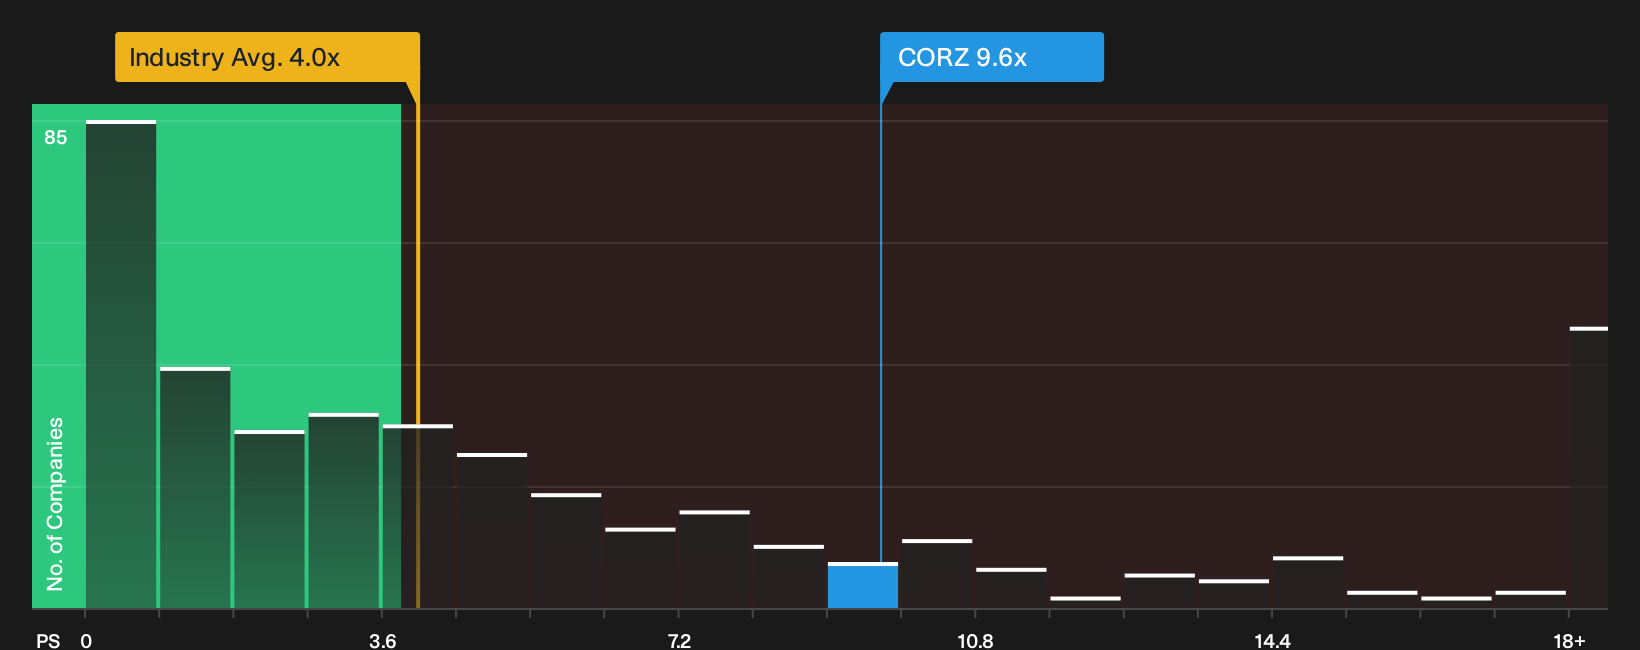
P/S fits Core Scientific because investors are currently focused on what each dollar of revenue is worth while free cash flow and earnings remain volatile. On this yardstick, the stock trades on a P/S of 9.6x, which is well above the Software industry average of 4.0x and the peer average of 3.4x. That means each dollar of Core Scientific’s sales is being valued at more than twice what the typical listed software business commands.
On a tailored fair value framework that adjusts for Core Scientific’s size, risk profile and sector, the stock screens as overvalued on its 9.6x P/S. Recent analyst commentary highlights long term AMD capacity reservations as a potential support for the story, so the current premium suggests the market is already assigning a rich price to those expectations rather than waiting to see them flow through the income statement. Investors weighing this valuation need to judge whether the sales base is resilient enough to justify paying such a high multiple for revenue today. Explore the numbers behind Core Scientific's P/S valuation.
The Core Scientific Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Core Scientific valuation puzzle leaves off, since they spell out which future paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price. Each is anchored to a specific view on how Core Scientific's revenue mix, profitability and risk profile might evolve. This gives you a concrete reference point to test and revisit as fresh information comes through.
One of the top community narratives on Core Scientific: 61% undervalued
"The improved balance sheet following significant debt restructuring and raising $625 million through a convertible note offering at 0% interest rates positions the company to effectively fund future growth initiatives…"
Discover why this Narrative puts Core Scientific at 61% undervalued.
One more piece of the Core Scientific puzzle before you act
Everything so far has focused on what Core Scientific looks like today, yet professional coverage also sketches out where they expect the business to be a few years from now. This gives you one more lens to compare with the current pricing. Explore where analysts expect Core Scientific to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com