
How Hybrid Quantum Platform Launch At Fujitsu (TSE:6702) Has Changed Its Investment Story
- SUSE and Fujitsu Services (FSAS) have already partnered with NVIDIA to build an AI driven hybrid quantum platform on Fujitsu servers, integrating SUSE AI Factory and NVIDIA CUDA-Q into a unified, production ready stack for enterprise data centers on sovereign infrastructure, targeted for availability in late 2026.
- The collaboration treats quantum circuits as workload extensions of SUSE AI Factory with NVIDIA, which could make complex hybrid quantum tasks manageable for standard IT teams and directly support Fujitsu efforts to grow higher margin advanced computing services.
- The next area of focus will be how the Fujitsu investment narrative could shift as this AI driven hybrid quantum platform moves into its enterprise rollout.
Scan other quantum and AI infrastructure plays that are moving on similar themes to Fujitsu with a curated list of 55 AI infrastructure stocks in this space.
Fujitsu Investment Narrative Recap
To hold Fujitsu, you need to believe the shift toward Service Solutions, Uvance and advanced computing can keep outweighing pressure in Hardware and Ubiquitous Solutions. The SUSE and NVIDIA hybrid quantum platform fits neatly into that story, because it leans into higher margin, recurring style services rather than volume hardware.
In the near term, the key swing factor is still execution on digital transformation projects and large public sector and defense contracts, not this single platform announcement. The bigger risk remains delays or non renewal of those long term deals, which could leave group revenue and margins more exposed to any further hardware weakness.
The most relevant recent news for this story is the SUSE and Fujitsu Services hybrid quantum platform built on NVIDIA CUDA Q and NVIDIA AI Enterprise. It plugs directly into the sovereign platform roadmap and the target for around ¥150b of sovereign platform revenue within a larger advanced computing market by 2035.
Operationally, the interest is that quantum circuits are treated as workload extensions of SUSE AI Factory on Fujitsu servers. That keeps hybrid quantum tied to Fujitsu Service Solutions, not just one off hardware. The main execution watchpoints are on time rollout in late 2026, enterprise adoption and the security posture of AI components, especially as research like BadEngram highlights fresh attack surfaces.
Fujitsu's narrative projects ¥3,940.0b revenue and ¥422.3b earnings by 2029. This is based on an assumed 3.7% yearly revenue growth and an earnings increase of about ¥104.5b from ¥317.8b today.
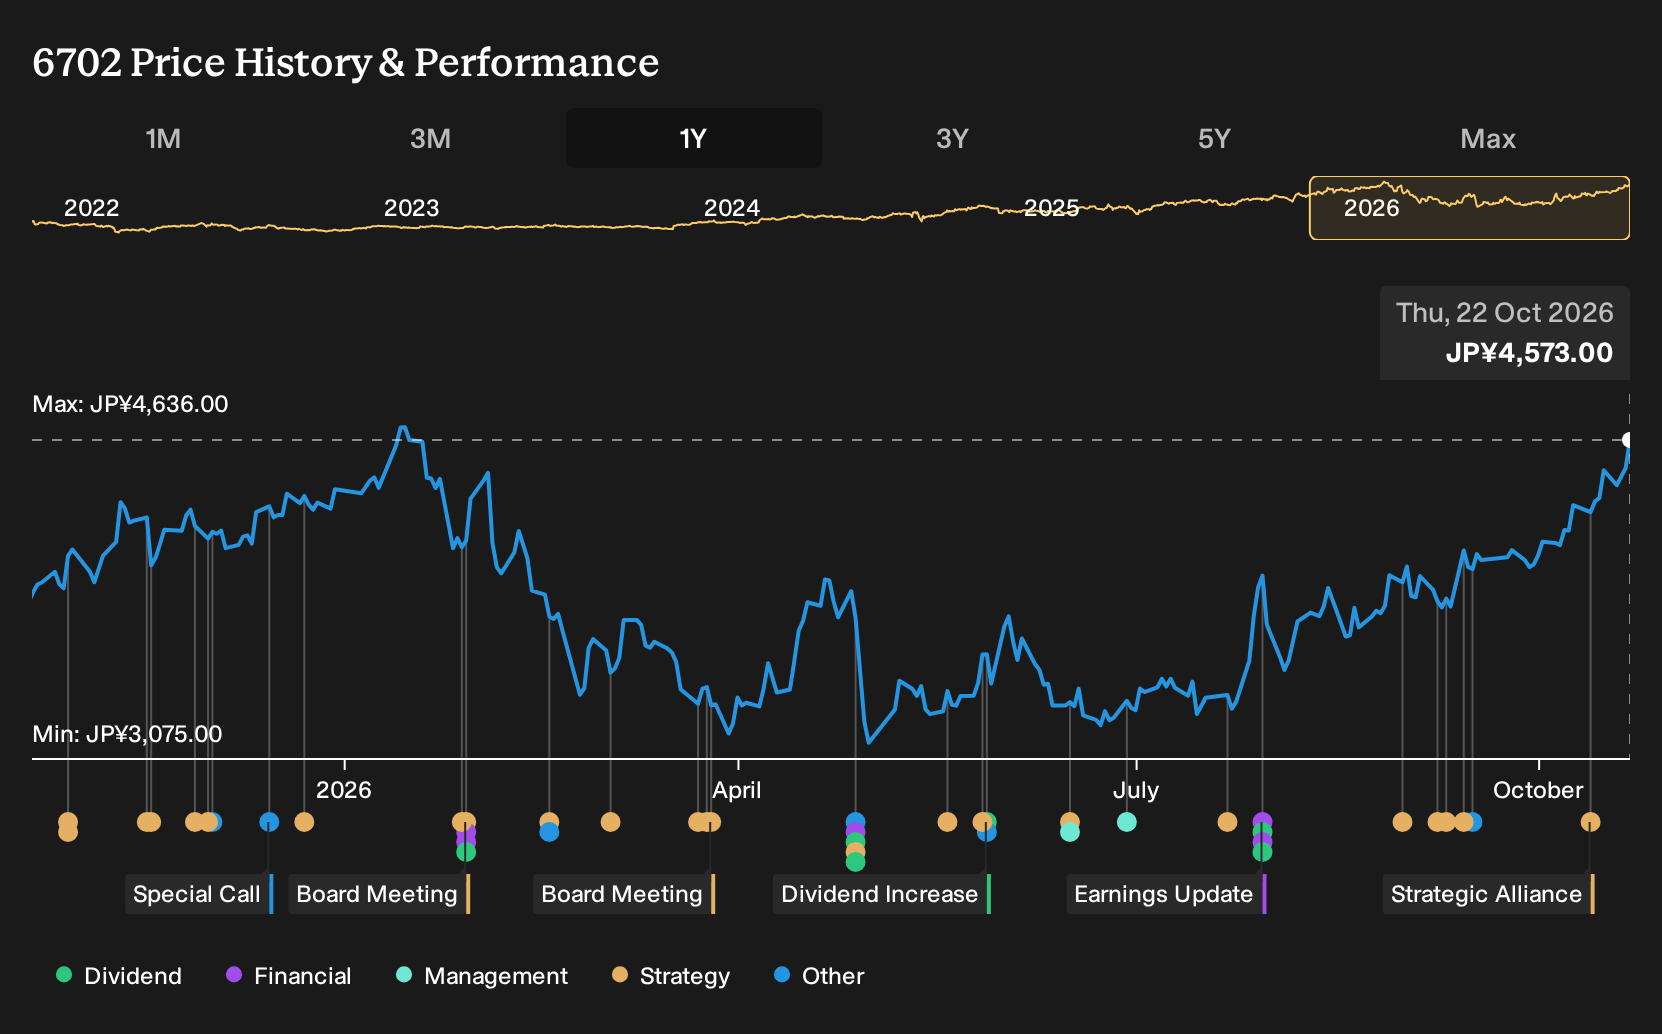
Uncover why Fujitsu's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist on Fujitsu is that some analysts already pencilled in faster Uvance and sovereign platform adoption, with revenue reaching about ¥4,102.7b and earnings around ¥481.0b by 2029. That is a more optimistic frame than consensus. These views were set before the SUSE hybrid quantum news, so expectations could still shift sharply.
Explore 2 other Fujitsu fair value estimates, including one that suggests there could be up to 31% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Fujitsu research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Fujitsu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fujitsu's overall financial health at a glance.
Looking For More Investment Ideas Beyond Fujitsu?
Once you have formed a view on Fujitsu, it helps to compare that thesis against other opportunities that fit different risk and income profiles. The Simply Wall St Screener can narrow a vast market down to a few focused shortlists tailored to what you care about most.
- If capital preservation matters to you first, filter for steadier profiles through a 21 resilient stocks with low risk scores that prioritises resilience over excitement.
- If strong balance sheets appeal more than story driven turnarounds, run a targeted search using a list of solid balance sheet and fundamentals (22 results) and see which companies carry robust fundamentals.
- If you prefer businesses that fewer investors are watching closely, cast a wider net across a 73 high quality undiscovered gems that highlight under the radar opportunities with solid metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com