
Exelon (EXC) Battery Storage Push Puts Fair Value Back In Focus
Exelon (EXC) is back in focus after subsidiary ComEd partnered with Richardson Electronics to expand battery energy storage manufacturing in Illinois and support a 5 MWh onsite demonstration project backed by the REV Illinois program.
Recent gains put Exelon back on investors’ radar. The shares are up 7.3% over the past month and 4.2% on the day of the ComEd announcement, while the 1 year total shareholder return is slightly negative and the 5 year total shareholder return of 42.4% points to more constructive longer term momentum.
Scan beyond Exelon and this battery storage push by checking a curated set of grid and infrastructure players in the 42 power grid technology and infrastructure stocks that may be riding similar demand tailwinds.
Exelon now has a battery storage story, a long record of regulated utility earnings and a share price that just jumped. Does that combination still leave enough value on the table today?
Most Popular Narrative: 7.9% Undervalued
On the most followed view, Exelon’s fair value of $48.71 sits above the last close at $44.85, which puts the recent rally into context and frames the battery storage move within a broader grid investment story priced with a 7.47% discount rate.
The rebalanced US$41.7b capital plan that shifts US$1.5b into higher earning transmission while deferring US$1.1b of lower priority distribution projects positions Exelon to pursue its targeted 7.9% rate base growth with a tilt toward assets that can support operating EPS and cash flow.
See why 37 investors see Exelon as 8% undervalued.
Result: Fair Value of $48.71 (UNDERVALUED)
Still, regulatory pushback on rate cases and customer affordability pressures at utilities like PECO could slow Exelon’s capital expenditure plans and undermine today’s undervaluation story.
Find out about the key risks to this Exelon narrative.
Another View: Exelon Through A DCF Lens
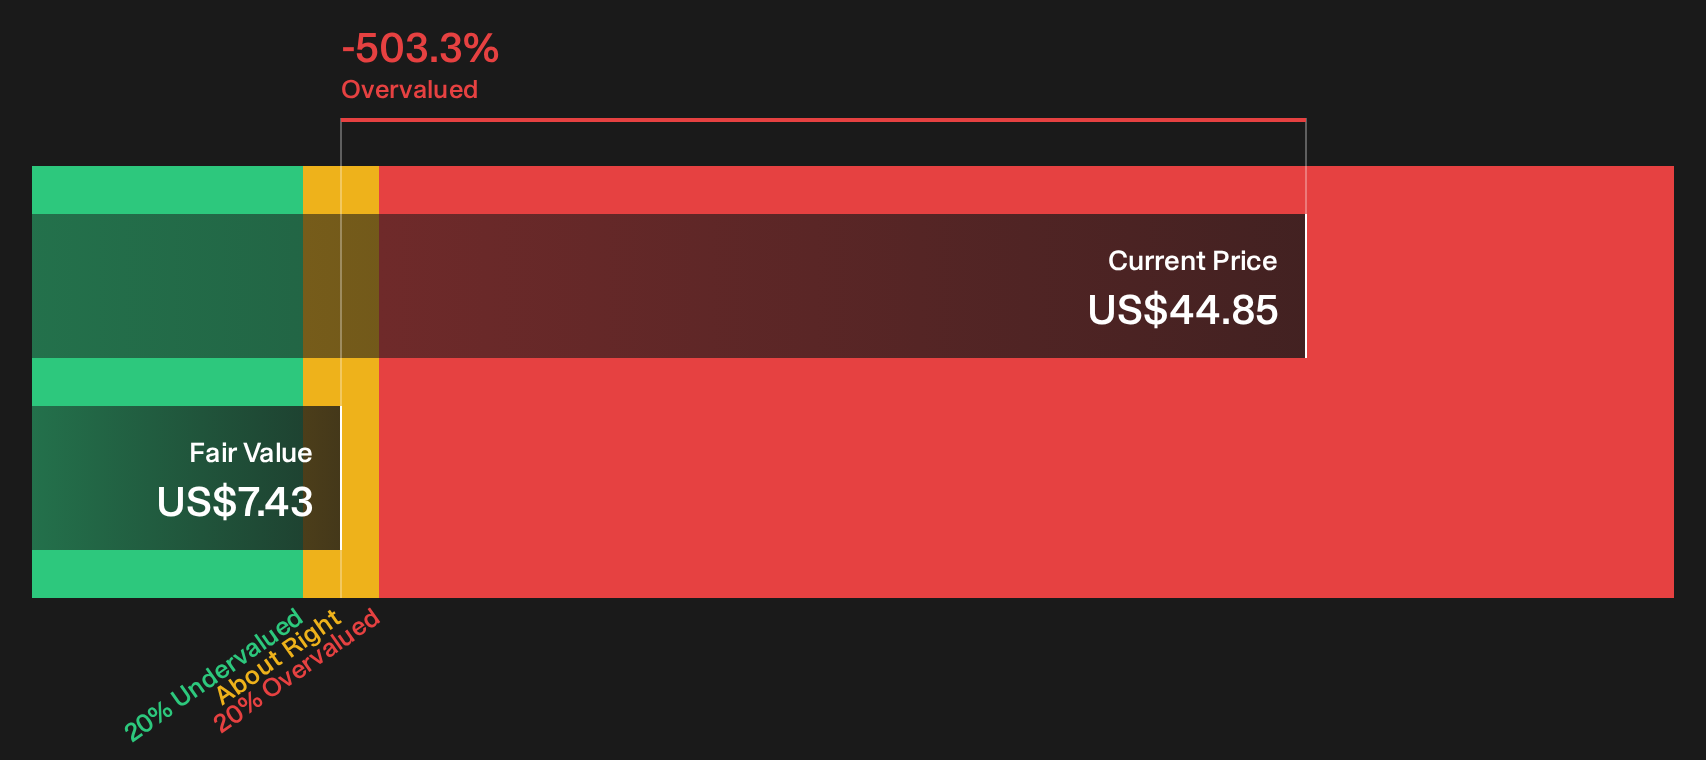
The first narrative leans on Exelon’s earnings path and analyst targets. A second cut uses the SWS DCF model, which values future cash flows at just $7.43 per share versus a $44.85 market price, implying the stock screens as heavily overvalued on this measure.
Those two pictures could not be further apart. The real question for you is which set of assumptions about long term cash generation feels more realistic for Exelon, and why.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Exelon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Exelon’s value story can be a strength if you use them as a prompt to stress test your own thesis today. To anchor that view in specifics, take a look at the 4 key rewards and 2 important warning signs.
Looking for more Exelon-sized investment ideas?
If you want a clearer sense of where Exelon fits in your portfolio, compare it with fresh opportunities that share similar quality markers and financial discipline.
- Target resilient compounders by scanning a 30 resilient stocks with low risk scores that filters for businesses with steadier fundamentals and fewer red flags than the wider market.
- Hunt for mispriced quality using a 29 high quality undervalued stocks to spot companies with strong cash flows that the market may not be fully pricing in yet.
- Stack your watchlist with potential standouts drawn from a 20 high quality undiscovered gems where solid fundamentals have yet to attract broad attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com