
Did Earnings Beat Just Shift L'Oréal's (ENXTPA:OR) Investment Narrative?
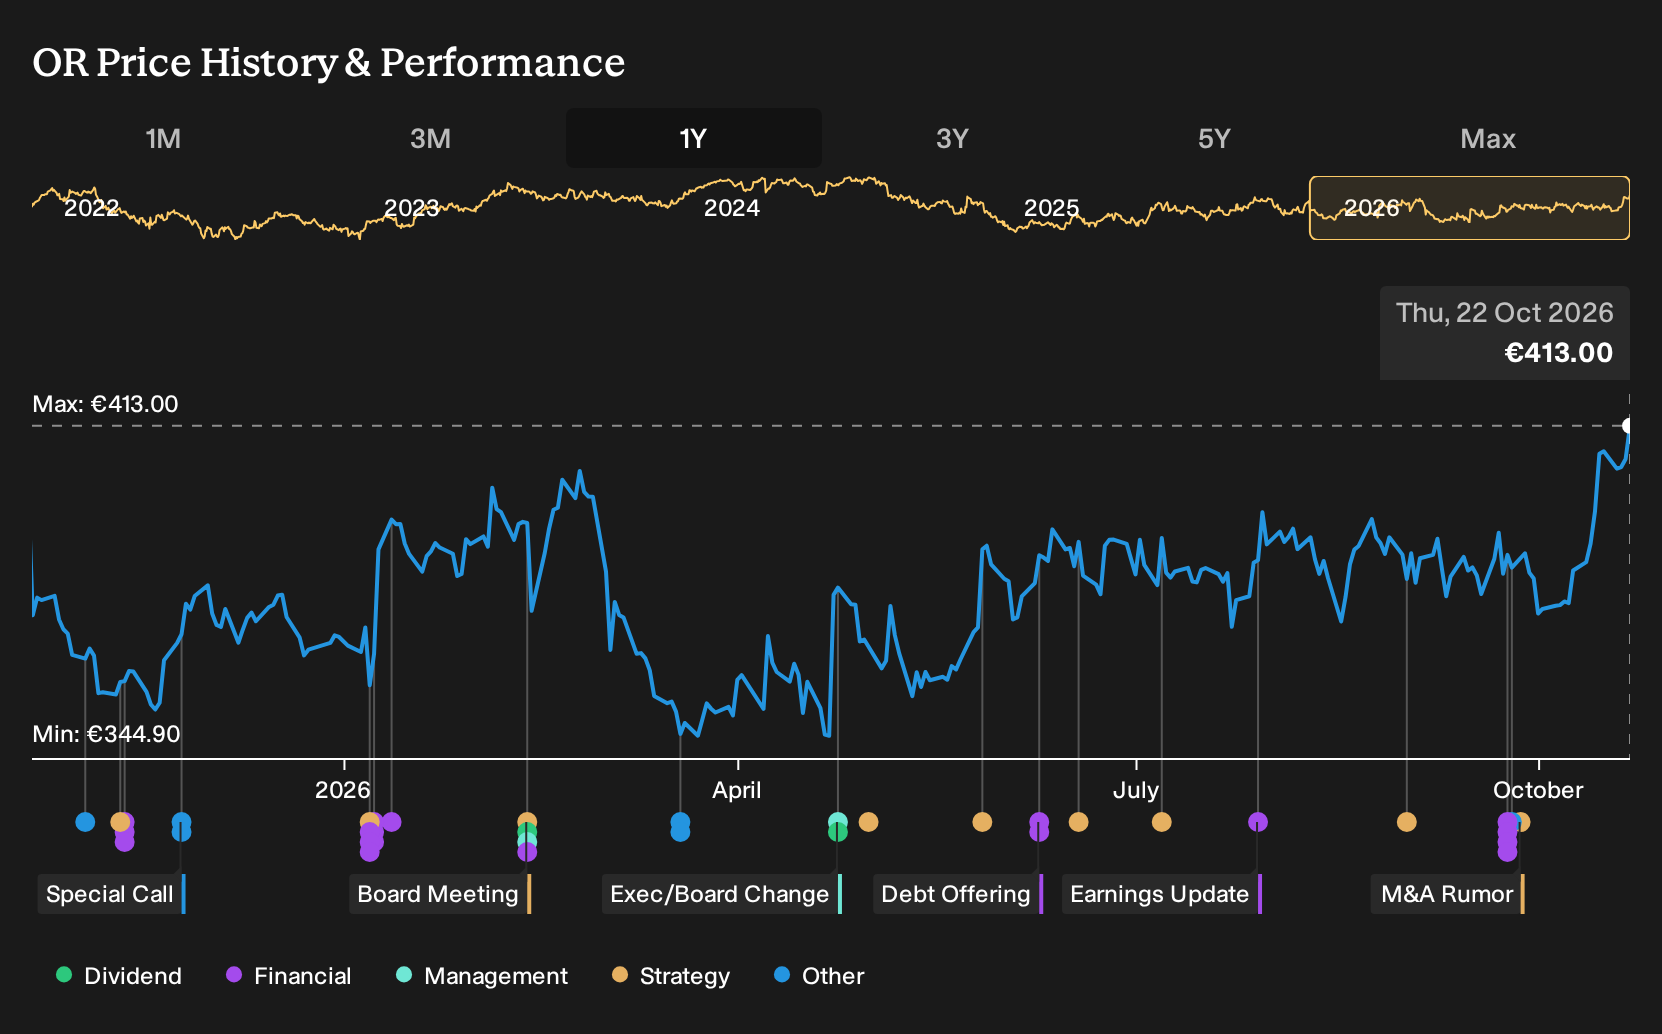
- L'Oréal recently reported double digit third quarter 2026 sales growth of 11.9% with all divisions contributing and e-commerce expanding at about 17%, while also closing the acquisition of a majority stake in Indian digital first personal care group Innovist.
- The combination of faster like for like sales than the global beauty market and a push into India through Innovist adds fresh detail on how L'Oréal is leaning into higher growth categories, regions and online channels that matter for its long term revenue mix.
- We will now look at how L'Oréal's stronger than expected third quarter sales and e-commerce momentum could influence its investment narrative.
L'Oréal Investment Narrative Recap
To own L'Oréal, you need to be comfortable with a large beauty group that leans heavily on premium brands, emerging markets and e-commerce to support future sales and earnings. The key near term swing factor remains execution in higher growth regions and online, where recent third quarter momentum and the Innovist acquisition support that focus.
The biggest operational risk still sits with competition from local and digital first rivals, plus changing tastes toward indie and dermatological brands. The new Kenyan image rights lawsuit adds legal and reputational noise, but on current information it does not alter the main commercial catalyst or the core business thesis.
The Innovist deal in India is the announcement that matters most for this set of headlines. It directly links L'Oréal to a digital first platform in a region where management already reports fast expansion, and it leans into the same themes that underpin the wider catalyst list, namely emerging markets and online channels.
For you as a shareholder, that means execution risk shifts slightly toward integration quality in India and the ability to scale acquired brands without diluting margins. If integration goes smoothly, this kind of bolt-on can reinforce the existing story of e-commerce growth and premium beauty, rather than changing it.
L'Oréal's current analyst story points to revenues of €54.7 billion and earnings of €8.9 billion by 2029, built on 6.5% yearly revenue growth and an earnings increase of about €2.6 billion from €6.3 billion today.
Uncover why L'Oréal's fair value indicates performance that is roughly in line with its current price.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster in a tight band between €418 and about €439, so you are seeing compact but still varied expectations. Set that beside L'Oréal's recent double digit sales growth, e-commerce expansion and fresh legal and competitive risks, and it becomes clear that community opinions can diverge sharply. Explore several of these alternative viewpoints before deciding where you sit.
Explore 2 other L'Oréal fair value estimates, including one that suggests up to 6% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your L'Oréal research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for L'Oréal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate L'Oréal's overall financial health at a glance.
Looking for more investment ideas beyond L'Oréal?
Once you have a view on L'Oréal, it often helps to compare it with other listed businesses that match the kind of risk, quality and income profile you want in your portfolio. The Simply Wall St Screener can narrow that universe quickly so you spend more time weighing fundamentals and less time trawling through tickers.
- If capital preservation is your priority, check out a curated set of resilient companies with steadier risk profiles through the 223 resilient stocks with low risk scores.
- For investors hunting for quality at a sensible entry point, use the screener focused on attractively priced opportunities built around the 190 high quality undervalued stocks.
- If you care most about regular cash payouts, scan income focused candidates by running the 225 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com