
Aurinia Pharmaceuticals (AUPH) Stock Looks Below Fair Value After A 136% Run
Aurinia Pharmaceuticals has delivered a powerful run for shareholders in recent years, and the share price now puts its earnings under a brighter spotlight. With the stock attracting more attention, the open question is whether the current valuation is adequately supported by the profits the business generates today and is expected to produce in the future.
- Over the past 3 years, Aurinia Pharmaceuticals has returned 136.4%, which puts real pressure on investors to ask whether the earnings profile has kept pace with the market value.
- The business is highly sensitive to how effectively it converts its drug portfolio into recurring revenue and cash, which can shape how much of today's earnings base is sustainable and how much needs to grow to support the current share price.
- The analysts covering Aurinia Pharmaceuticals have run their own numbers. See what analysts think Aurinia Pharmaceuticals's shares could be worth.
The issue now is whether Aurinia Pharmaceuticals' earnings are strong and resilient enough to justify where the stock trades today.
If you are weighing whether Aurinia Pharmaceuticals' recent 136.4% three year return is well supported by its earnings, it can help to compare it with other companies using 29 high quality undervalued stocks
Is Aurinia Pharmaceuticals Still Cheap on Earnings?
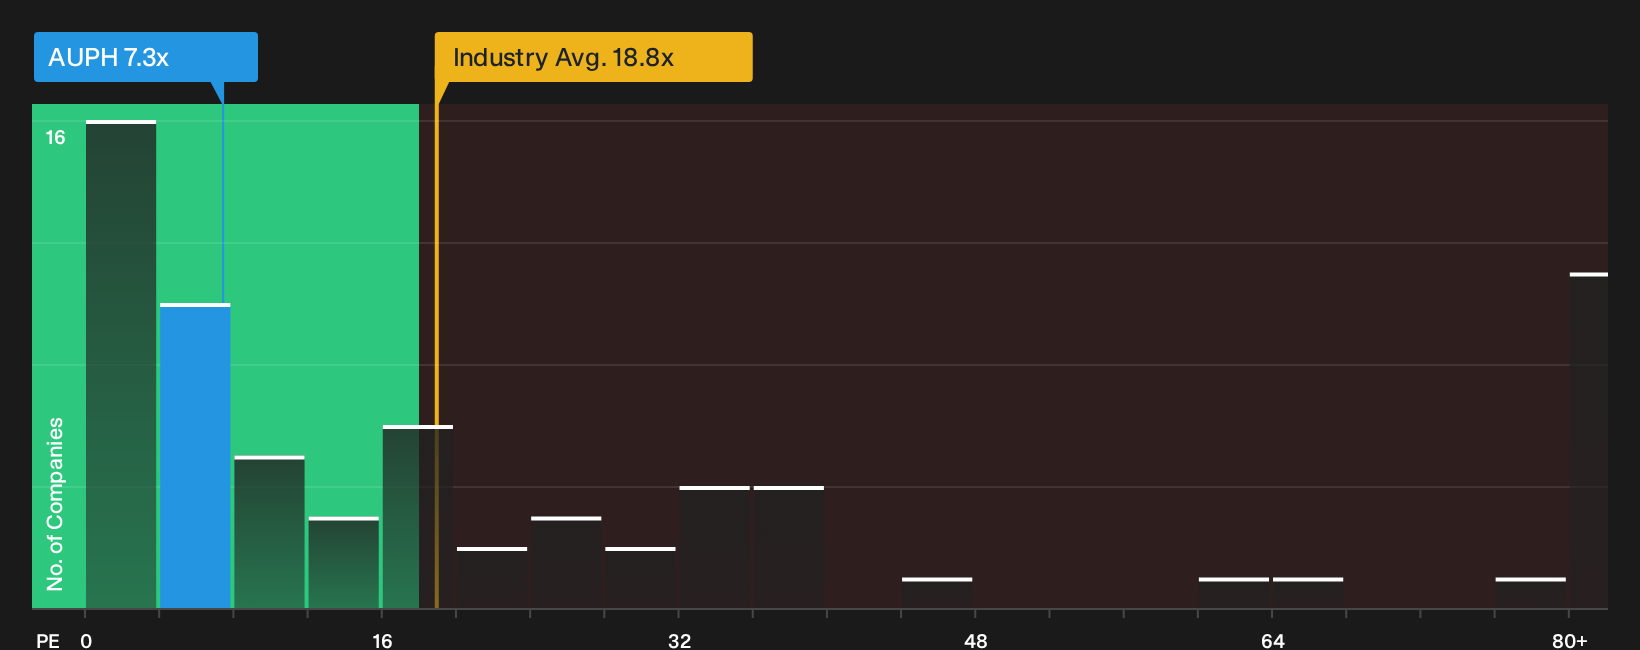
The P/E ratio works reasonably well for Aurinia Pharmaceuticals because the market can already anchor the share price to a positive earnings base. On this measure, the stock trades on a P/E of 7.3x, which is well below the broader biotech industry average of 18.8x and also below the 36.7x level seen across peers in the space.
The fair multiple implied by Aurinia Pharmaceuticals' own earnings quality, scale and risk profile sits higher than where the current 7.3x P/E is today, which points to the shares pricing in a discount to what that framework suggests. For anyone weighing whether that gap reflects opportunity or warranted caution, the key questions are how durable current profits prove to be and how much of the existing drug portfolio converts into repeatable earnings over time. Explore the numbers behind Aurinia Pharmaceuticals's P/E valuation.
The Aurinia Pharmaceuticals Narrative: What Would Justify Today's Price?
Narratives for Aurinia Pharmaceuticals pick up where the P/E puzzle leaves off and explain which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today. Each scenario links a fair value estimate to a distinct view of Aurinia Pharmaceuticals' potential catalysts and key risks so you can track over time which storyline the business is actually following on Simply Wall St's Community page.
One of the top community narratives on Aurinia Pharmaceuticals: 17% undervalued
"With Lupkynis (voclosporin) as its single commercial asset for lupus nephritis, the company has turned concentration into discipline..."
Discover why this Narrative puts Aurinia Pharmaceuticals at 17% undervalued.
Aurinia Pharmaceuticals: one more question that could reshape the story
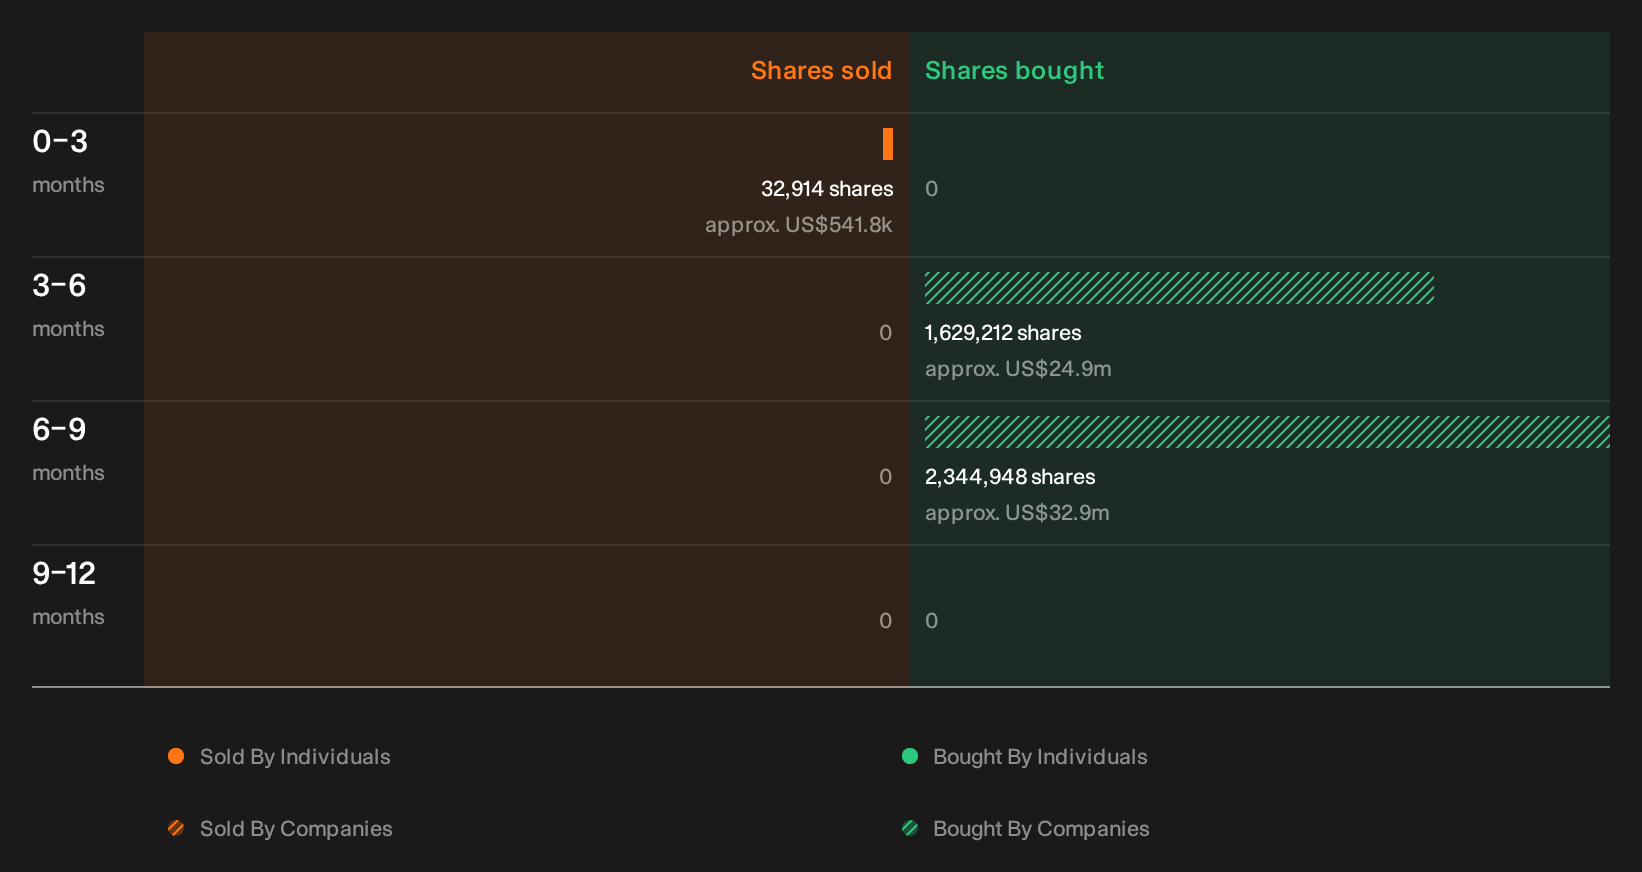
Valuation only tells part of what matters for Aurinia Pharmaceuticals. Recent management share dealings flagged by our checks raise a fresh line of inquiry about insider behaviour that you may want to examine next. See the recent insider selling flagged for Aurinia Pharmaceuticals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com