
Honeywell Aerospace (HONA) Slides 20% In 3 Months, Is The Valuation Discount Enough?
Honeywell Aerospace (HONA) trades at US$163.02 after a mixed recent run, including a decline of about 20% over the past 3 months. That backdrop makes its current fundamentals worth a closer look.
Recent trading tells a cautious story. Honeywell Aerospace’s 1 day share price return of 0.34% sits against a 7 day share price return that declined 3.02% and a 90 day share price return down 20.12%, which together point to fading momentum despite earlier resilience year to date.
See how Honeywell Aerospace compares with other industrial companies facing similar pressures by reviewing our hand picked list of list of solid balance sheet and fundamentals (26 results).
The slide in Honeywell Aerospace after earlier gains presents a simple fork in the road. Has most of the recovery already played out, or do the current fundamentals still point to meaningful upside ahead?
Preferred P/E of 26.6x: Is it justified?
Valuation for Honeywell Aerospace today leans heavily on earnings. The stock trades on a P/E of 26.6x, while peers in the US Aerospace & Defense group sit closer to the low 30s. This suggests the market currently assigns a lower earnings multiple than the broader sector.
P/E simply compares the share price to earnings per share, so it reflects how much investors are willing to pay for each dollar of profit. For Honeywell Aerospace, this lens matters because earnings are forecast to grow, even if they are not projected to grow at very high rates under the current analyst estimates.
The gap between Honeywell Aerospace on 26.6x and the industry on 32.2x is clear, and the peer average of 31.3x points in the same direction. The market is pricing the business at a discount to both its immediate rivals and the wider sector, which points to an undervalued P/E relative to these reference points.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 26.6x (UNDERVALUED)
Still, the investment case around Honeywell Aerospace could shift quickly if aerospace demand softens or if its broad hardware and services portfolio faces pricing pressure.
Find out about the key risks to this Honeywell Aerospace narrative.
Another view on Honeywell Aerospace’s value
The earnings multiple presents Honeywell Aerospace as modestly cheap, but the SWS DCF model is far more aggressive. On that framework, HONA at $163.02 trades about 37.8% below an estimated fair value of $262.13, which indicates a much deeper mispricing. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
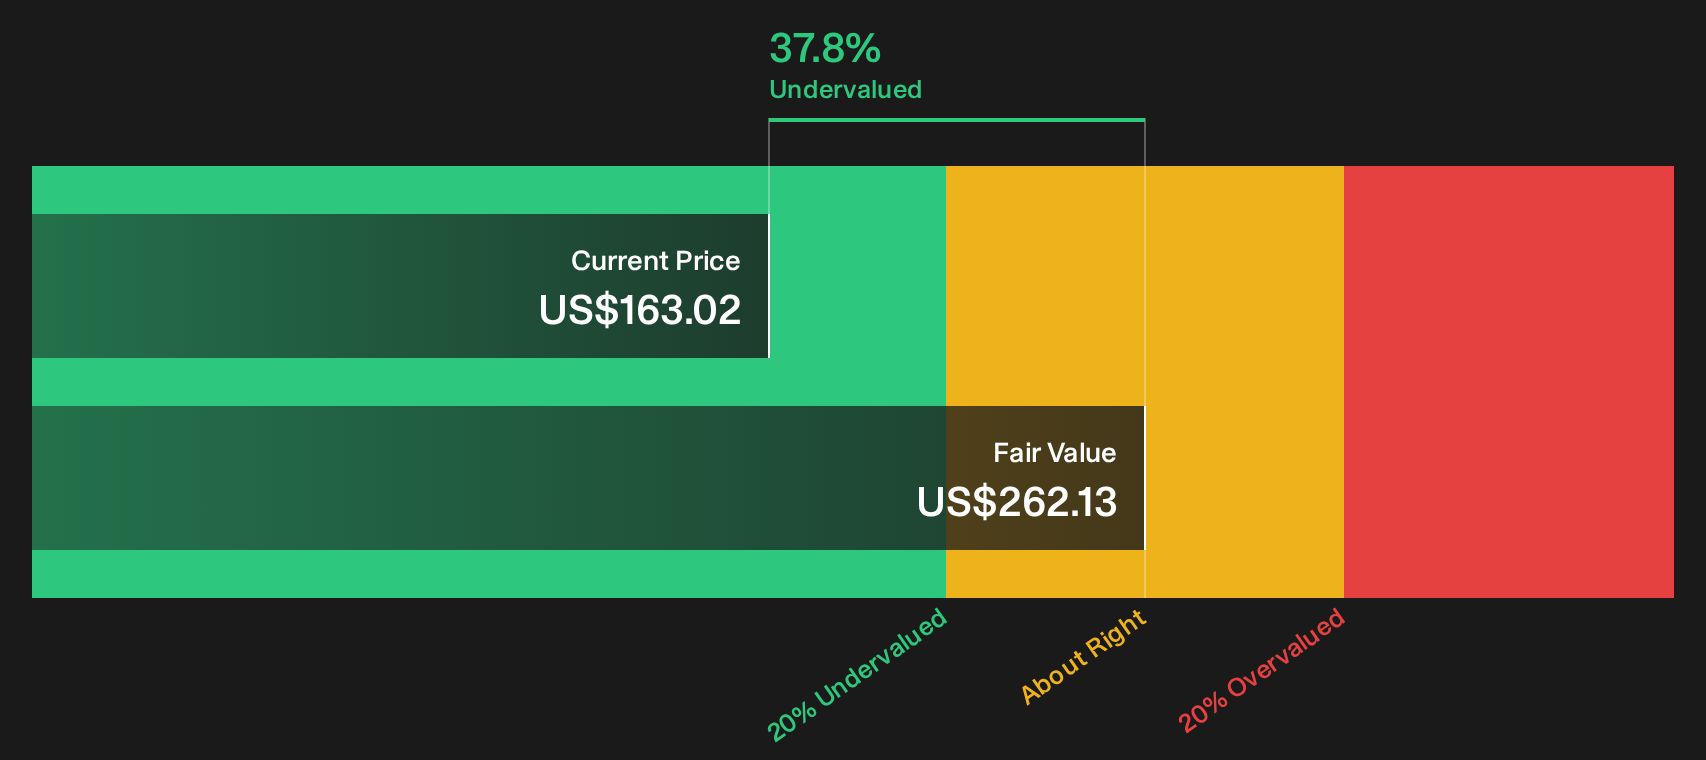
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Honeywell Aerospace for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in Honeywell Aerospace’s valuation story make this a judgment call. Act while the data is still fresh, weigh both the potential upsides and the flagged issues, and ground your own thesis in the 4 key rewards and 3 important warning signs.
Looking for more Honeywell Aerospace style investment ideas?
If Honeywell Aerospace has sharpened your focus on valuation and quality, do not stop here. Broader opportunities often sit just outside your current watchlist.
- Target resilient balance sheets that can better handle shocks by scanning our 30 resilient stocks with low risk scores.
- Hunt for pricing gaps where quality and valuation still line up by running the 29 high quality undervalued stocks.
- Spot potential future market favorites early by reviewing the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com