
Liberty Global (LBTY.A) Stock Could Be Cheap Despite Its 45% Five Year Fall
Liberty Global has seen its share price under pressure in recent years, and that slide puts a spotlight on a basic question for investors who look at revenue based metrics. Is the current valuation of the telecom and media group adequately supported by the sales the business is generating?
- Over the past 5 years the stock has fallen 44.8%, which puts long term holders squarely on the issue of whether today's market value still lines up with Liberty Global's underlying sales base.
- Recent moves around VodafoneZiggo, including EU clearance for a tower sale and progress toward a Ziggo Group listing planned for 2027, may influence how investors think about Liberty Global's future revenue mix and balance sheet strength.
- The analysts covering Liberty Global have run their own numbers. See what analysts think Liberty Global's shares could be worth.
The issue now is whether the current share price of Liberty Global is justified by the level and quality of sales that the business is producing.
If you want to pressure test this same sales based valuation question beyond Liberty Global, widen the lens with the 29 high quality undervalued stocks.
Does Liberty Global Look Undervalued on Sales?
P/S matters for Liberty Global because investors often focus on the value of its network footprint and subscriber base more than on current earnings.
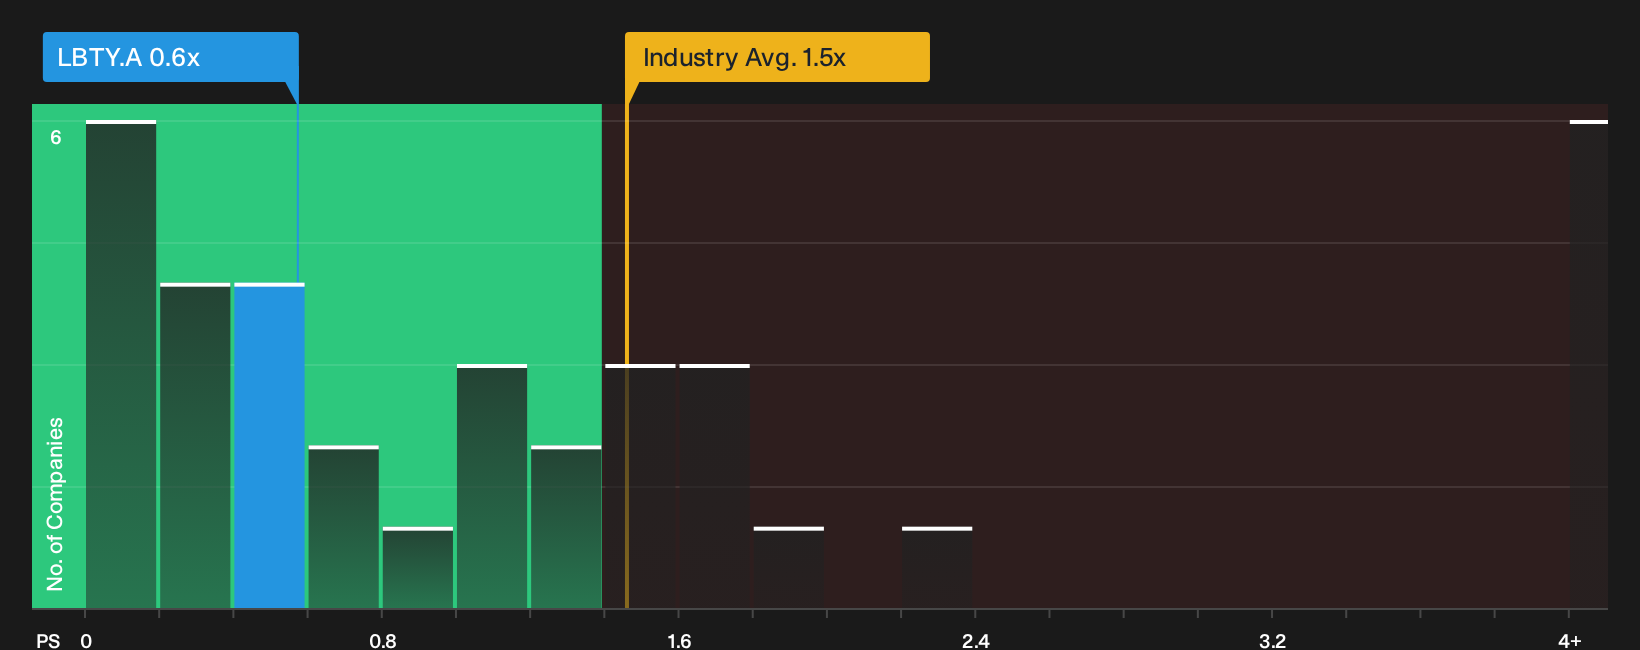
The stock trades on a P/S ratio of 0.6x, which is well below both the telecom industry average of 1.5x and a peer group closer to 2.1x. On Simply Wall St’s fair multiple framework, which looks at Liberty Global's growth prospects, profitability profile, sector and risk, the current P/S sits below the level that model would typically expect for this business. Because the recent VodafoneZiggo tower sale clearance aims to reduce leverage ahead of a Ziggo Group listing, the discounted P/S suggests the market is still pricing Liberty Global cautiously despite those balance sheet moves. Explore the numbers behind Liberty Global's P/S valuation.
The Liberty Global Narrative: What Would Justify Today's Price?
Narratives pick up where Liberty Global's valuation puzzle leaves off and show which combinations of future growth, margins and earnings would need to occur for the share price to sit meaningfully above or below today's level. Each Narrative turns Liberty Global's implied fair value into a clear, testable idea about the business, so you can revisit the same thesis over time and see how it holds up as new information emerges on the Community page.
One of the top community narratives on Liberty Global: 32% undervalued
"The discount is substantial, but Liberty is not a straightforward holding company with $27 of readily available assets behind each share..."
Discover why this Narrative puts Liberty Global at 32% undervalued.
Before you act on Liberty Global's valuation, there is one more piece to check
Price tells you what the market thinks today, but analyst models sketch out where they see Liberty Global a few years from now. This gives you a different benchmark to compare with the current sales based multiple. Explore where analysts expect Liberty Global to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com