
VICI Properties (VICI) Stock May Still Be A Bargain As Dividend Questions Persist
VICI Properties has been paying a high dividend and attracting income focused investors, yet its share price is still well below where it was a year ago. That mix of income appeal and softer recent returns puts a clear question on the table for VICI Properties stock, which is whether the current price makes sense when you line it up against the earnings that support it.
- The share price has fallen 18.2% over the past year, which puts extra pressure on the argument that VICI Properties' earnings fully support where the stock trades today.
- The business is paying an 8.0% dividend yield that is currently covered by adjusted funds from operations at about a 74% payout ratio, which can influence how investors weigh the durability of its earnings against the level of income they receive.
- The analysts covering VICI Properties have run their own numbers. See what analysts think VICI Properties's shares could be worth.
The issue now is whether VICI Properties' current share price is justified by the earnings power the business is generating today.
If you want to test the same earnings versus price question beyond VICI Properties, apply the same approach to a wider field of income ideas with the 6 dividend fortresses
Is VICI Properties a Bargain on Earnings?
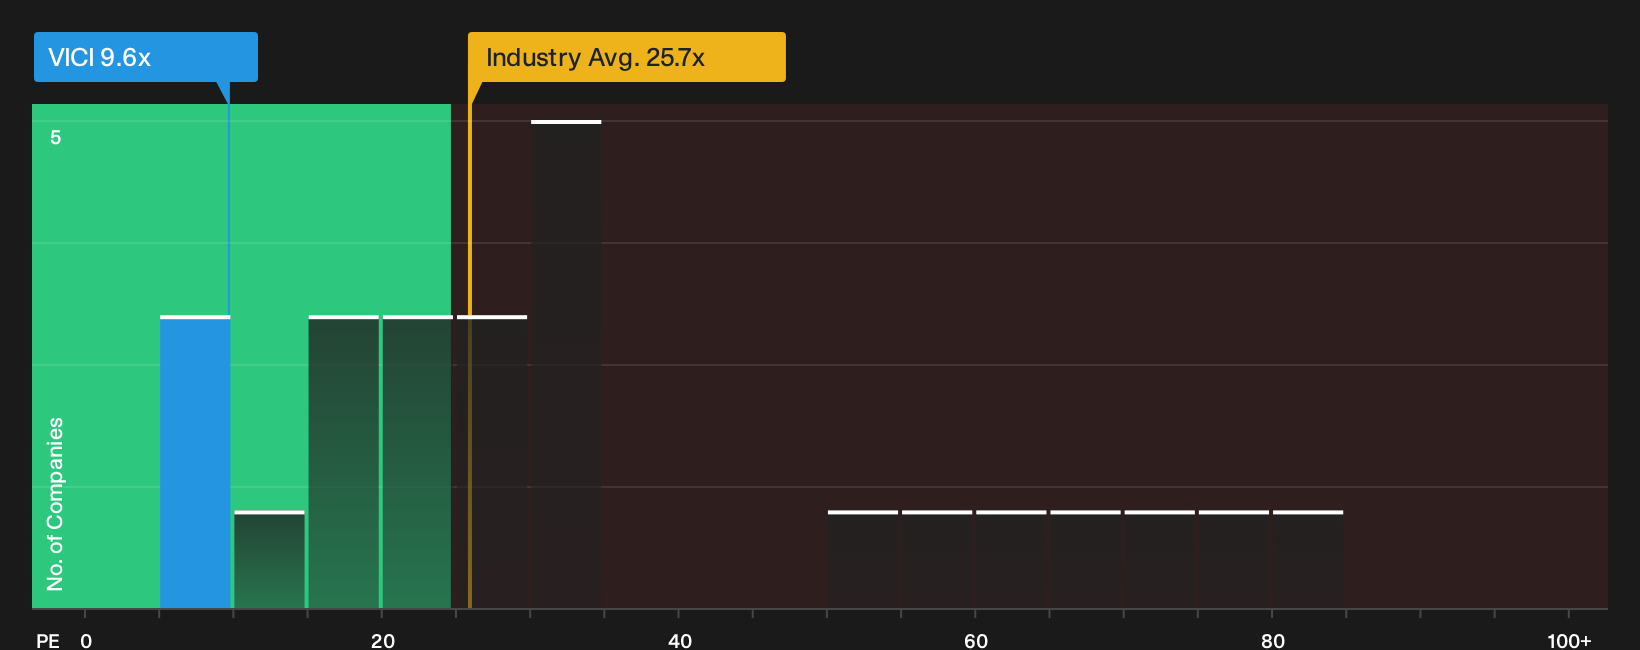
P/E suits VICI Properties because earnings are the core support for its dividend and AFFO story. On that yardstick, the stock trades on a P/E of 9.6x, which is well below the Specialized REITs industry average of 15.1x and far under the broader peer group on about 35.6x. That gap tells you the market is assigning a materially lower valuation to each dollar of VICI Properties' earnings than to comparable real estate businesses.
Fair value models that blend factors like growth expectations, profitability and risk suggest VICI Properties would typically trade on a higher P/E than where it is now, so the current multiple screens as undervalued on this framework. Because the shares are pricing in this discount even as the company continues to pay an 8.0% dividend and absorb uncertainty around the Caesars acquisition, you need to decide whether that lower earnings multiple reflects risks that matter to you or a potential opportunity. Explore the numbers behind VICI Properties's P/E valuation.
The VICI Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for VICI Properties' P/E leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth materially more or less than today's market price on the Community page. Rather than a single multiple or model output, each narrative lays out the assumptions that sit behind its fair value view so you can track those against VICI Properties' actual results as they arrive.
One of the top community narratives on VICI Properties: 43% undervalued
"Using this valuation method investors can see VICI through a dividend first lens that focuses on its payout capacity over time..."
Discover why this Narrative puts VICI Properties at 43% undervalued.
One more crucial question for VICI Properties
Before you focus solely on VICI Properties' valuation, it is worth checking the specific risk factors our research has flagged and deciding how they fit with your own comfort level. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com