
Ollie’s Bargain Outlet Holdings (OLLI) Could Be 6% Undervalued As Buyback Lifts The Debate
Ollie's Bargain Outlet Holdings (OLLI) put capital allocation in focus on 13 October 2026, when the retailer announced a share repurchase plan of up to US$500 million with no set end date.
That buyback decision lands after a strong run in the share price over the past quarter, with a 90 day share price return of 39.69% and a 30 day gain of 12.31%. However, the year to date share price return is still down 16.79% and the 1 year total shareholder return has declined 23.56%, so momentum in Ollie's Bargain Outlet Holdings appears to be rebuilding from a weaker longer term base.
Scan how Ollie's Bargain Outlet Holdings compares to other retailers acting on renewed momentum by reviewing a curated list of 20 high quality undiscovered gems.
Ollie's Bargain Outlet Holdings has rallied sharply on the buyback news, yet the stock is still down notably over the past year. Is most of the recovery already reflected in the price, or is there still meaningful value left?
Most Popular Narrative: 6% Undervalued
On the most followed narrative, Ollie's Bargain Outlet Holdings is priced below an assessed fair value of $98.78, compared with the latest close at $92.63. This puts the buyback against a backdrop of modest implied upside and a detailed earnings story.
Ollie's reported its second quarter of fiscal 2027 on September 2, 2026, posting comparable store sales of -1.8% against what management called "one of the toughest comparisons we have had as a company." The headline earnings beat, adjusted EPS of $1.42, up 43%, was substantially powered by IEEPA tariff refunds that added 380 basis points to gross margin, a nonrecurring item that management both celebrated and immediately began caveating.
See why 2 investors see Ollie's Bargain Outlet Holdings as 6% undervalued.
Result: Fair Value of $98.78 (UNDERVALUED)
Still, the Ollie's Bargain Outlet Holdings narrative leans on tariff refund support and heavier price investment, so any weaker closeout supply or softer comps could quickly challenge it.
Find out about the key risks to this Ollie's Bargain Outlet Holdings narrative.
Another View On Ollie's Bargain Outlet Valuation
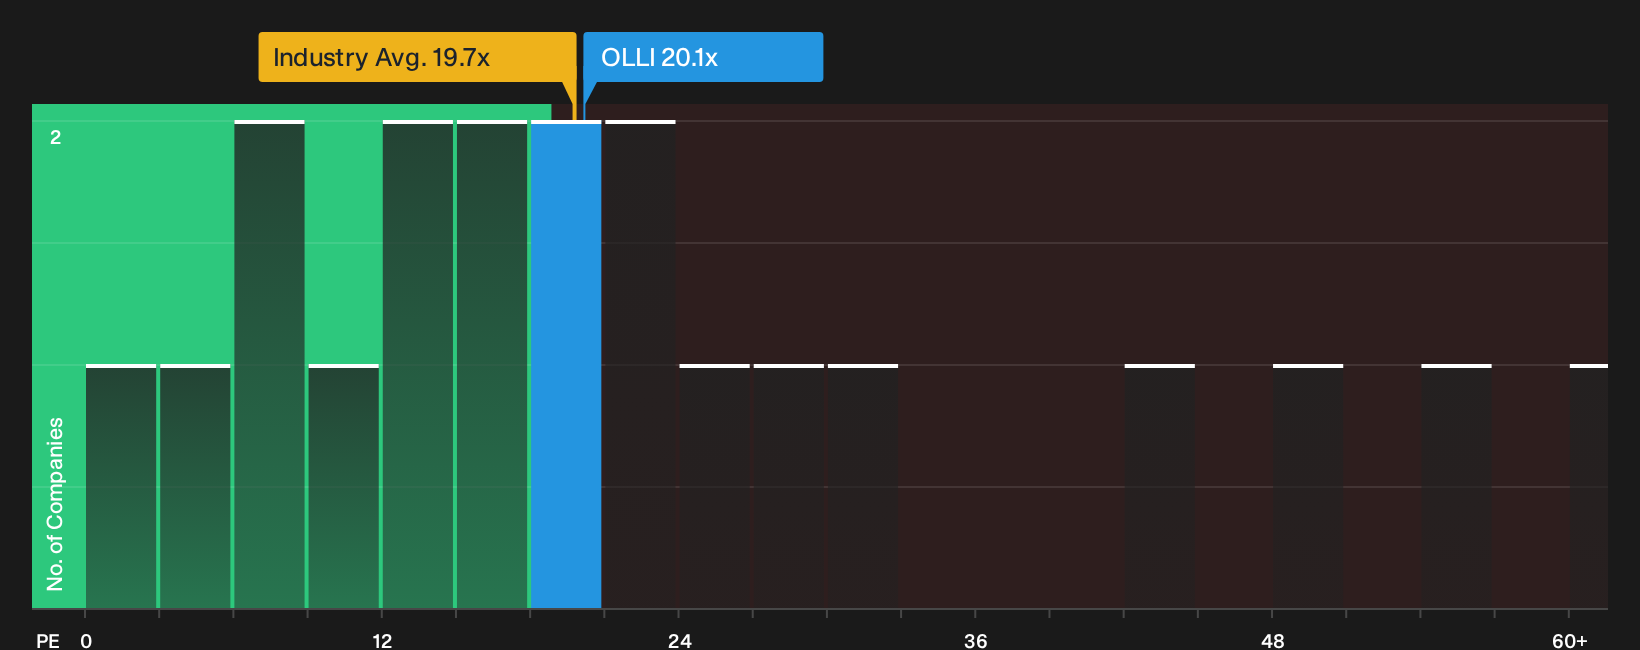
The narrative pegs Ollie's Bargain Outlet Holdings at a fair value of $98.78, yet the preferred P/E work paints a tighter picture. The stock trades at 20.1x earnings, slightly above the Global Multiline Retail group at 19.7x, and well above a fair ratio of 13.4x that the market could eventually lean toward.
That gap suggests investors are paying a premium multiple that leaves less room for error than the 6% undervalued story implies. The real question is how comfortable you are owning a retailer where expectations already sit above that fair ratio. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed takes on Ollie's Bargain Outlet Holdings are healthy, but you do not need to sit on the sidelines while others debate the story. Act while the data is fresh and review the full breakdown of 3 key rewards.
Looking for more investment ideas beyond Ollie's Bargain Outlet Holdings?
Do not stop with a single watchlist candidate. Broader context across sectors can help you spot patterns earlier and avoid concentrating risk in one story.
- Target fresh upside setups by scanning a curated pool of 20 high quality undiscovered gems that pair strong fundamentals with low current visibility.
- Prioritise resilience in rough patches and filter for companies on the 30 resilient stocks with low risk scores that score well on financial strength and volatility.
- Strengthen the core of your portfolio by anchoring it with a list of solid balance sheet and fundamentals (26 results) so weak financing does not undermine a good thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com