
Moog (MOG.A) Could Be 23% Below Fair Value As Defense Growth Comes Into Focus
Moog stock performance and recent context
Moog (MOG.A) has attracted fresh attention after a period of mixed share performance, with the price near US$341.71 and returns down over the past week, month, and past 3 months but higher over the year to date.
Recent trading has been choppy. The share price has slipped over the past week and quarter, yet Moog still carries strong momentum on a longer view, with a year to date share price gain and multiyear total shareholder return comfortably positive.
Spot fresh momentum in Moog, and then widen your watchlist with a handpicked set of resilient industrial and capital goods stocks in the 30 resilient stocks with low risk scores.After a sharp pullback from recent highs yet a strong run over the past year, Moog now forces a choice. Do you commit at this level, or wait for a cleaner entry as the valuation picture comes into focus next?
Most Popular Narrative: 23% Undervalued
Moog is framed as undervalued in the most followed narrative, with a fair value of $446.40 against the last close at $341.71. This puts the focus firmly on whether its current growth drivers can support that gap.
Moog is positioned to benefit from a sustained increase in global defense spending, with significant order backlog and direct exposure to U.S., NATO, and Indo Pacific modernization programs. These factors are likely to drive multi year revenue growth and increased earnings stability.
See why 22 investors see Moog as 23% undervalued.
Result: Fair Value of $446.40 (UNDERVALUED)
Still, the Moog story can be knocked off course if higher tariffs squeeze Commercial Aircraft profitability, or if the next wave of efficiency gains proves tougher to realize.
Find out about the key risks to this Moog narrative.
Another View: Moog through a cash flow lens
Moog may look inexpensive relative to the $446.40 fair value from the most popular narrative, yet the Simply Wall St DCF model presents a contrasting view. In that framework, the current $341.71 share price is well above an estimated future cash flow value of $183.77, which highlights a risk of overvaluation if cash generation falls short.
When one approach suggests upside and our DCF model indicates caution, it brings the focus back to your own assumptions about how reliably Moog can convert its backlog and margin plans into cash over time.
To understand how this cash flow view is constructed, and which assumptions matter most, check out the Look into how the SWS DCF model arrives at its fair value..
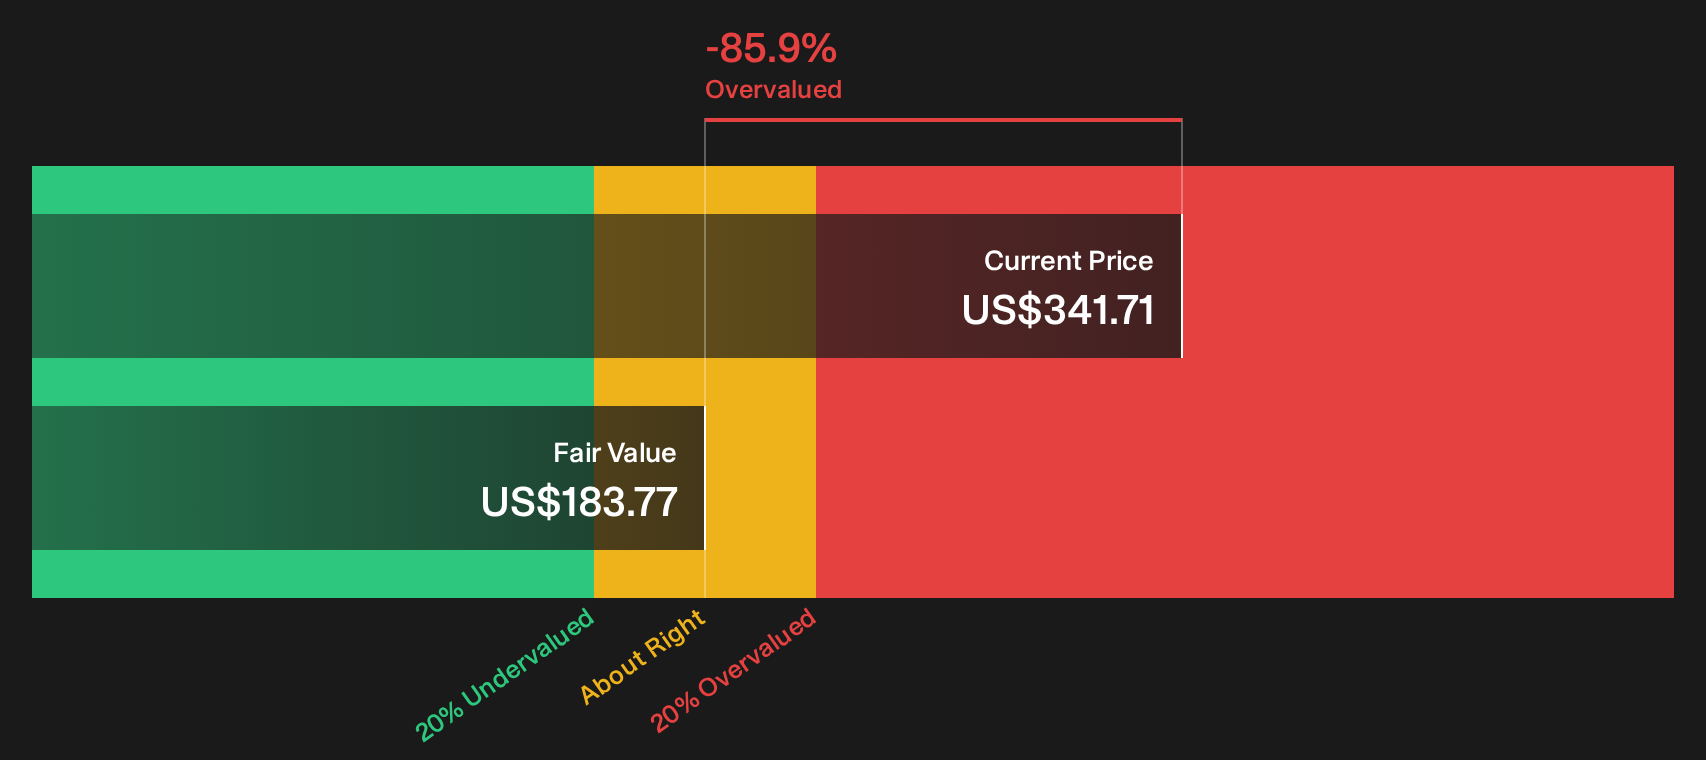
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Moog for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split views on Moog have you on the fence, consider acting while the data is fresh and test the thesis for yourself using the 3 key rewards.
Looking for more Moog alternatives and investment ideas?
If Moog has sharpened your thinking, do not stop here. Broaden your watchlist now with data driven ideas that others will only find later.
- Target stability first by scanning a list of solid balance sheet and fundamentals (26 results) that can help you focus on companies built on stronger financial foundations.
- Hunt for pricing gaps using the 29 high quality undervalued stocks to spot opportunities where fundamentals and current market expectations do not fully line up.
- Build a cash flow focused watchlist through the 6 dividend fortresses so you are not relying only on future price moves for returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com