
Snap (SNAP) Could Be 13% Undervalued On Its Q2 Beat
Snap (SNAP) moved back into focus after a second quarter update in 2026 beat Wall Street expectations, with revenue supported by small and medium-sized advertisers and World Cup related spending.
At a share price of US$6.35, Snap has seen a 90 day share price return of 45.98% and a 30 day gain of 12.99%. However, the total shareholder return over one year is still down 19.31%, which signals short term momentum building against a weaker longer term record.
Scan how Snap's rebound compares with other potential breakouts in digital media and tech by reviewing the hand picked list of 20 high quality undiscovered gems in the same space.
Snap now trades well below some valuation estimates, even after a sharp rebound. So the next step is clear: Do the current numbers still tilt the risk reward toward buyers or toward patience?
Most Popular Narrative: 13% Undervalued
On the most followed narrative, Snap’s fair value of $7.33 sits above the last close at $6.35. This frames the recent rebound as only a partial catch up rather than a full rerating.
Accelerating innovation in augmented reality (AR), including the upcoming public launch of Specs AR glasses in 2026 and continuous expansion of the AR developer ecosystem, positions Snap to benefit from both increased user engagement and the creation of premium advertising and subscription revenue streams, which can boost top-line revenue and improve gross margins over time.
See why 72 investors see Snap as 13% undervalued.
Result: Fair Value of $7.33 (UNDERVALUED)
Still, competition for digital ad budgets and ongoing losses, with Snap reporting a net loss of US$311.24 million, could yet blunt this undervaluation story.
Find out about the key risks to this Snap narrative.
Another View: What Multiples Say About Snap
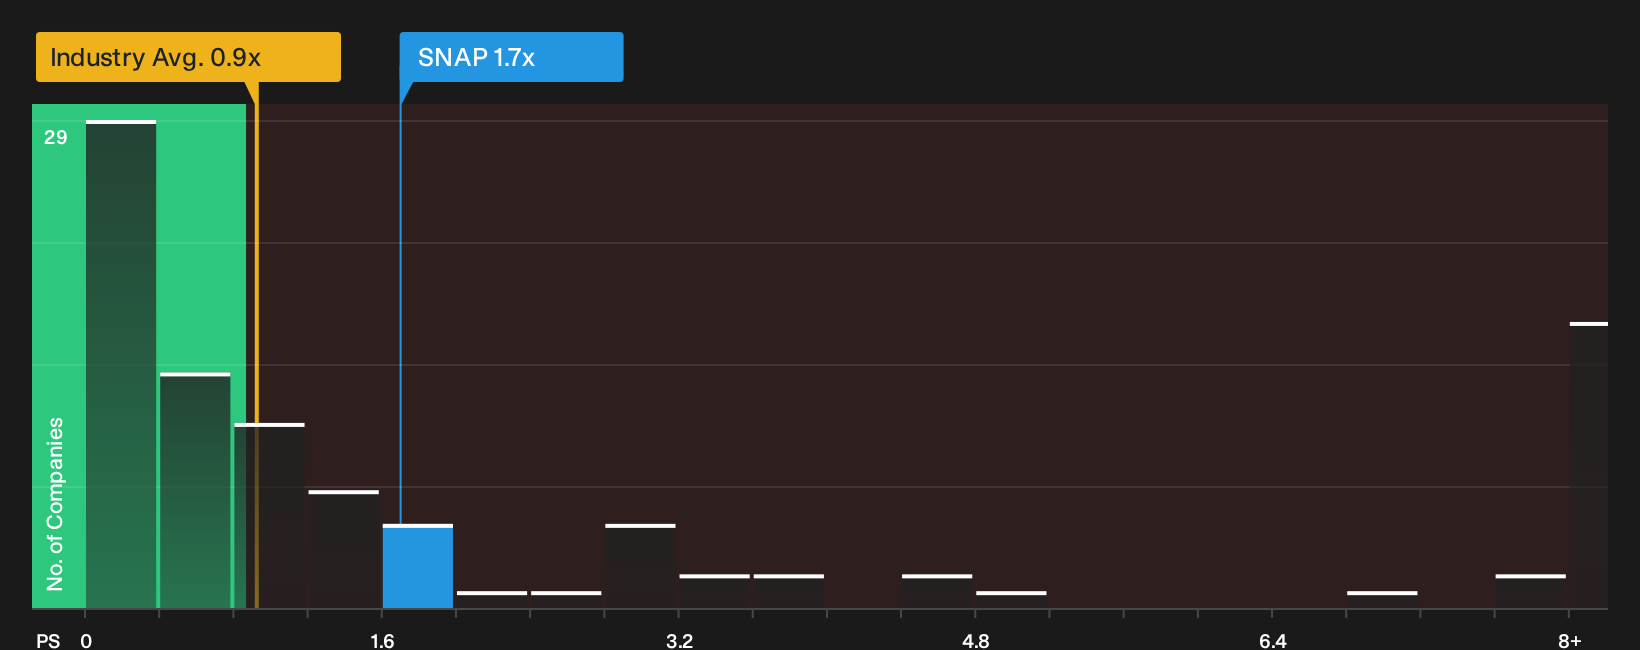
On price-to-sales, Snap does not look cheap. The stock trades at a P/S of 1.7x, which is almost double the US Interactive Media and Services average of 0.9x, yet still below a fair ratio estimate of 2.2x that the market could move toward over time.
That gap hints at two very different readings. One is that peers are pricing in less risk than Snap despite weaker ratios. The other is that Snap has already been marked down and the P/S could eventually drift closer to the 2.2x fair ratio. Which version do you think the market is leaning toward right now, and what does that mean for your own risk budget when you compare it with list of solid balance sheet and fundamentals (26 results)?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Snap so far, with a rebound in the share price sitting against past losses and questions about advertising strength and profitability. Act while the data is fresh and form your own view by weighing the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Snap?
Do not stop at just one ticker. Fresh opportunities often appear where solid fundamentals, resilient balance sheets, and misunderstood stories meet.
- Target steady compounders by reviewing a curated mix of quality companies that currently look mispriced using the 29 high quality undervalued stocks.
- Prioritise staying power by focusing on businesses with stronger cushioning against shocks through the 30 resilient stocks with low risk scores.
- Hunt for tomorrow's potential standouts by scanning a research driven short list of under the radar stocks in the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com