
McKesson (MCK) 1% Over Fair Value As Dividend Reaffirmation Keeps Focus On Valuation
McKesson (MCK) has reaffirmed its regular shareholder payout, with the board declaring a quarterly dividend of US$0.94 per share, payable on January 4, 2027, to investors of record on December 1, 2026.
The dividend decision comes after a strong run in McKesson’s share price, with a 30 day share price return of 13.6% and a 90 day move of 20.4%. The 1 year total shareholder return of 28.2% and very large 5 year total shareholder return indicate that momentum has been building over time around its earnings track record and upcoming results on November 4, 2026.
See how McKesson’s dividend story compares with other healthcare stocks showing strong recent momentum in our curated 29 high quality undervalued stocks list.
After a surge that has pushed McKesson to around US$1,012 per share and close to analyst targets, the key question is straightforward: do you lean into the momentum now or wait for the valuation to cool first?
Most Popular Narrative: 1% Overvalued
McKesson’s most followed narrative pegs fair value at about $1,001, which is slightly below the last close around $1,012. This suggests the current rally is running just ahead of that framework while still leaning on a detailed long term earnings view.
Increasing adoption of specialty and oncology pharmaceuticals, together with the build out of multispecialty platforms such as US Oncology Network and PRISM, is shifting McKesson’s mix toward higher margin services that can support operating margin and earnings growth.
Integration of Precision Medicine Group into McKesson’s oncology ecosystem, including clinical research and commercialization capabilities, is expected to create a fuller service offering to biopharma customers that can support future revenue growth and margin expansion in the Oncology & Multispecialty segment.
See why 63 investors see McKesson as 1% overvalued.
Result: Fair Value of $1,001 (OVERVALUED)
Still, McKesson’s story can change quickly if drug pricing pressure hits margins or if cyber and data security issues lead to higher costs and customer losses.
Find out about the key risks to this McKesson narrative.
Another View: McKesson On Earnings Multiples
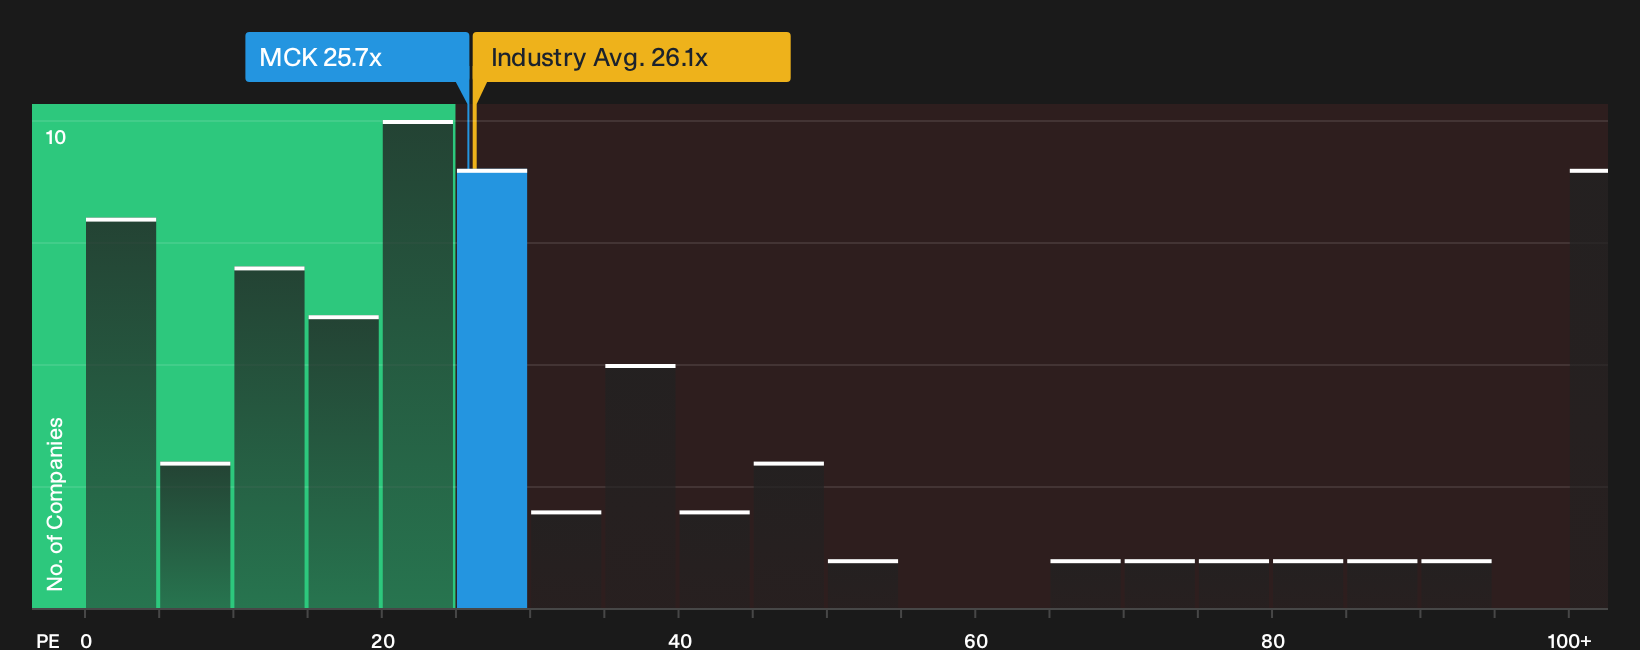
The first narrative argues McKesson is about 1% overvalued versus a US$1,001 fair value, yet the P/E picture sends a different signal. The stock trades on 25.7x earnings, below both the 26.1x US Healthcare average and a fair ratio of 31.2x. This points to valuation risk cutting both ways.
For investors weighing that gap between current P/E and the higher fair ratio, the key question is simple: Does the market close it upward or treat today’s price as already generous, given the recent run in McKesson?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around McKesson’s value and momentum can feel urgent, so use that urgency to check the full picture yourself. To weigh both the upside potential and the issues investors are worried about, review the 4 key rewards and 1 important warning sign.
Looking for more McKesson-sized investment ideas?
If McKesson has caught your attention, do not stop here. Broaden your watchlist with fresh ideas that match different goals and risk levels.
- Target steadier compounding by focusing on companies that combine quality metrics with attractive pricing through our 29 high quality undervalued stocks.
- Strengthen your income stream by hunting for reliable payers with robust yields and payout support using the 6 dividend fortresses.
- Protect your downside by filtering for financially resilient businesses that show lower overall risk characteristics inside the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com