
Annaly Capital Management (NLY) Faces A Valuation Test Following Its Third Quarter Loss
Annaly Capital Management (NLY) just posted a third quarter net loss of US$1.0b, a sharp swing from profit a year earlier, after rising rates and wider Agency MBS spreads pressured results.
Annaly Capital Management’s share price has fallen 14.5% over the past month and 19.9% year to date. The 3 year total shareholder return of 82.8% and 1 year total shareholder return of 0.5% point to fading near term momentum after a strong prior run.
Spot potential income alternatives to Annaly Capital Management by scanning our hand picked 6 dividend fortresses that have navigated volatile rate moves with relatively resilient share price performance.After a sharp pullback and a fresh quarterly loss, Annaly Capital Management now poses a practical question for income focused investors. Is today’s weaker share price already enough compensation for the risk, or does patience look wiser until the valuation section spells out the trade off?
Preferred P/E of 15.1x: Is it justified for Annaly Capital Management?
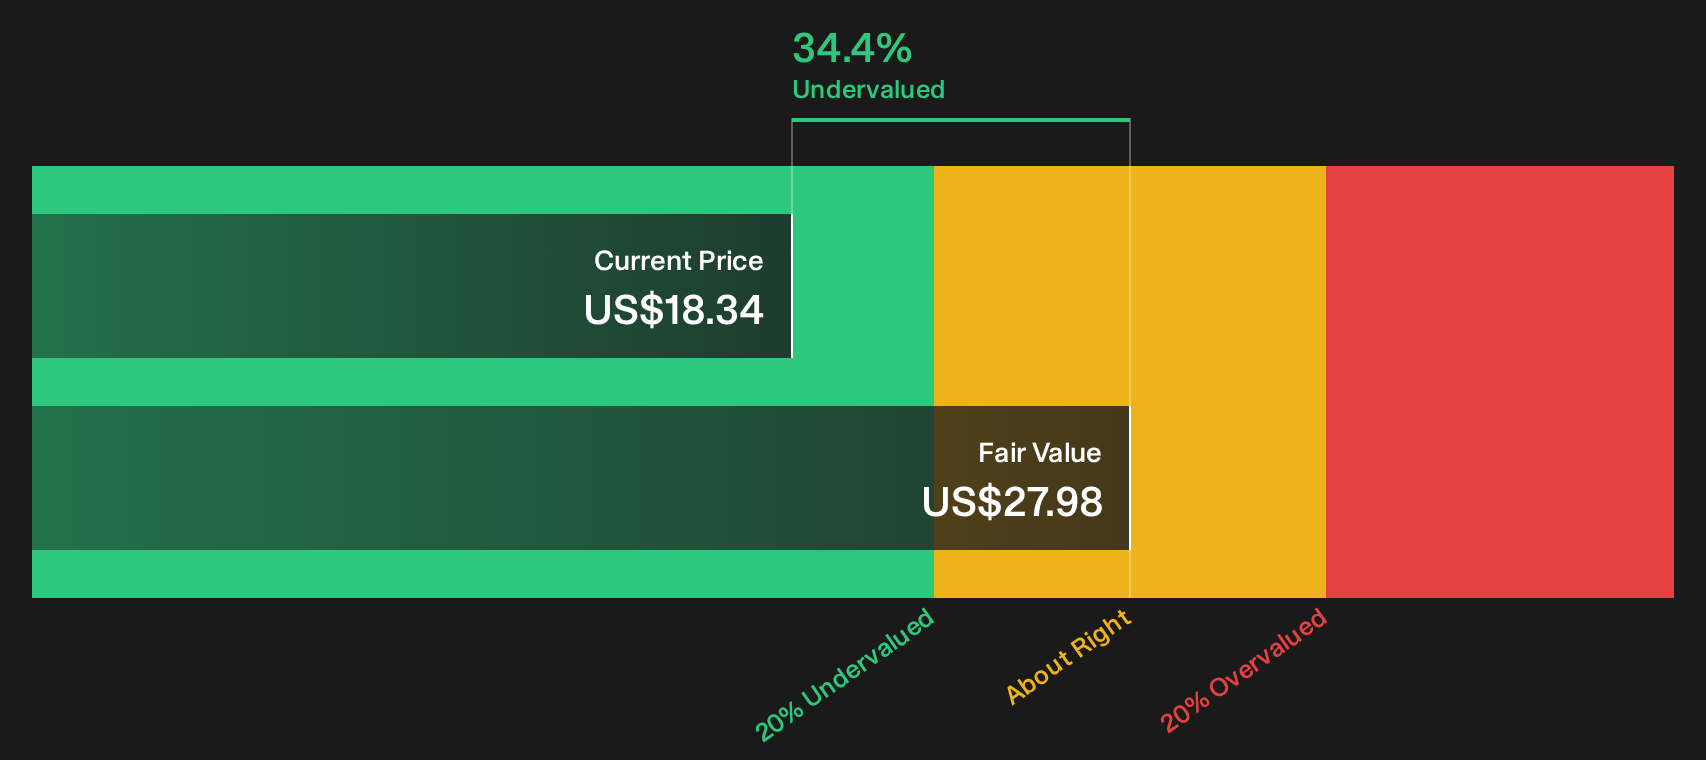
Valuation screens mark Annaly Capital Management on a P/E of 15.1x, which is higher than Mortgage REIT peers and sits alongside a discounted view from the SWS DCF model that places fair value closer to $27.98 per share versus a last close of $18.34.
The P/E multiple compares the current share price to earnings per share and gives a quick shorthand for how much investors are paying for each dollar of profit. For a mortgage REIT like Annaly Capital Management, this ratio often reflects views on future earnings resilience, interest rate sensitivity, and how sustainable the current income profile looks.
At 15.1x earnings, the stock screens as expensive compared with the US Mortgage REITs industry average of 9.7x. The same framework that estimates a Fair P/E of 24.2x indicates that the current ratio could still move closer to that implied level if the market becomes more comfortable with the earnings outlook and risk profile.
Explore the SWS fair ratio for Annaly Capital Management.
Result: Price-to-earnings of 15.1x (OVERVALUED)
Still, the Annaly Capital Management story can be knocked off course if mortgage spreads widen further, or if funding costs stay higher for longer than expected.
Find out about the key risks to this Annaly Capital Management narrative.
Another View on Annaly Capital Management’s Value
A different lens tells almost the opposite story. Our DCF model points to a fair value of about $27.98 per share for Annaly Capital Management, which is roughly 34.4% above the recent $18.34 price and presents the stock as undervalued instead of expensive. Which signal should investors rely on when real money is at stake?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Annaly Capital Management for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Annaly Capital Management is clearly mixed right now. Move quickly, pull up the full data, and weigh both sides of the story for yourself with 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Annaly Capital Management?
Do not stop your research with Annaly Capital Management. A broader watchlist could give you more options and a clearer view of risk and reward.
- Target potential value plays that pair solid balance sheets with reasonable pricing by running the list of solid balance sheet and fundamentals (26 results).
- Hunt for opportunities that combine quality fundamentals with attractive pricing by scanning the 20 high quality undiscovered gems before other investors catch on.
- Prioritize stability and capital preservation by reviewing the 30 resilient stocks with low risk scores and see which businesses currently carry lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com