
FormFactor Stock In Focus After New AI Chip Test Factory Opens
- FormFactor opened a new manufacturing facility in Farmers Branch, Texas, expanded probe card production capacity, and secured a US$300 million equity investment from Teradyne, followed by a US$300,000,056 private placement closing.
- The Farmers Branch site gives FormFactor more room to handle rising test complexity around GPUs, custom ASICs, HBM, and silicon photonics. The Teradyne alliance also tightens integration between probe cards and test systems for high volume AI hardware production.
- We will now look at how FormFactor's new Farmers Branch capacity could reshape the investment narrative built around AI test demand.
Compare FormFactor's AI test capacity story with other potential beneficiaries of the same trend by scanning our hand picked 55 AI infrastructure stocks for your watchlist.
FormFactor Investment Narrative Recap
To own FormFactor, you need to believe semiconductor test intensity around GPUs, custom ASICs, HBM and silicon photonics stays structurally high and that the firm can translate this into durable probe card and systems demand. The key near term swing factor is execution on the expanded Farmers Branch capacity and broader operational transformation, including keeping gross margins closer to recent levels.
The biggest risk right now is that expectations around AI related test demand and margins are already high after strong recent share price performance, so any cooling in orders or a reset in gross margin could hit sentiment quickly. Customer and product concentration also matters, because shifts in spending or roadmaps at a few large DRAM, GPU or hyperscaler accounts could make quarterly results more volatile.
The Teradyne collaboration and related US$300m equity investment look most relevant to the Farmers Branch ramp. You now have a test systems provider and a probe card specialist trying to align architectures from wafer through high volume production. This aligns directly with FormFactor’s goal of handling more complex AI and advanced packaging workloads efficiently.
For you as an investor, that partnership turns into a practical execution test. Can FormFactor convert deeper integration with Teradyne into stickier design wins across GPUs, HBM and custom ASICs without slipping on quality, lead times or profitability? If the integration is slow, or if joint customers delay deployments, the capacity that Farmers Branch brings could take longer to fill at attractive economics.
FormFactor's current analyst narrative points to revenue of US$1.6b and earnings of US$519.5m by 2029, based on a forecast 20.8% yearly increase in revenue and an increase in earnings of about US$404m from US$115.5m today.
Uncover how FormFactor's fair value indicates a 62% potential upside to its current price before the gap to FormFactor closes.
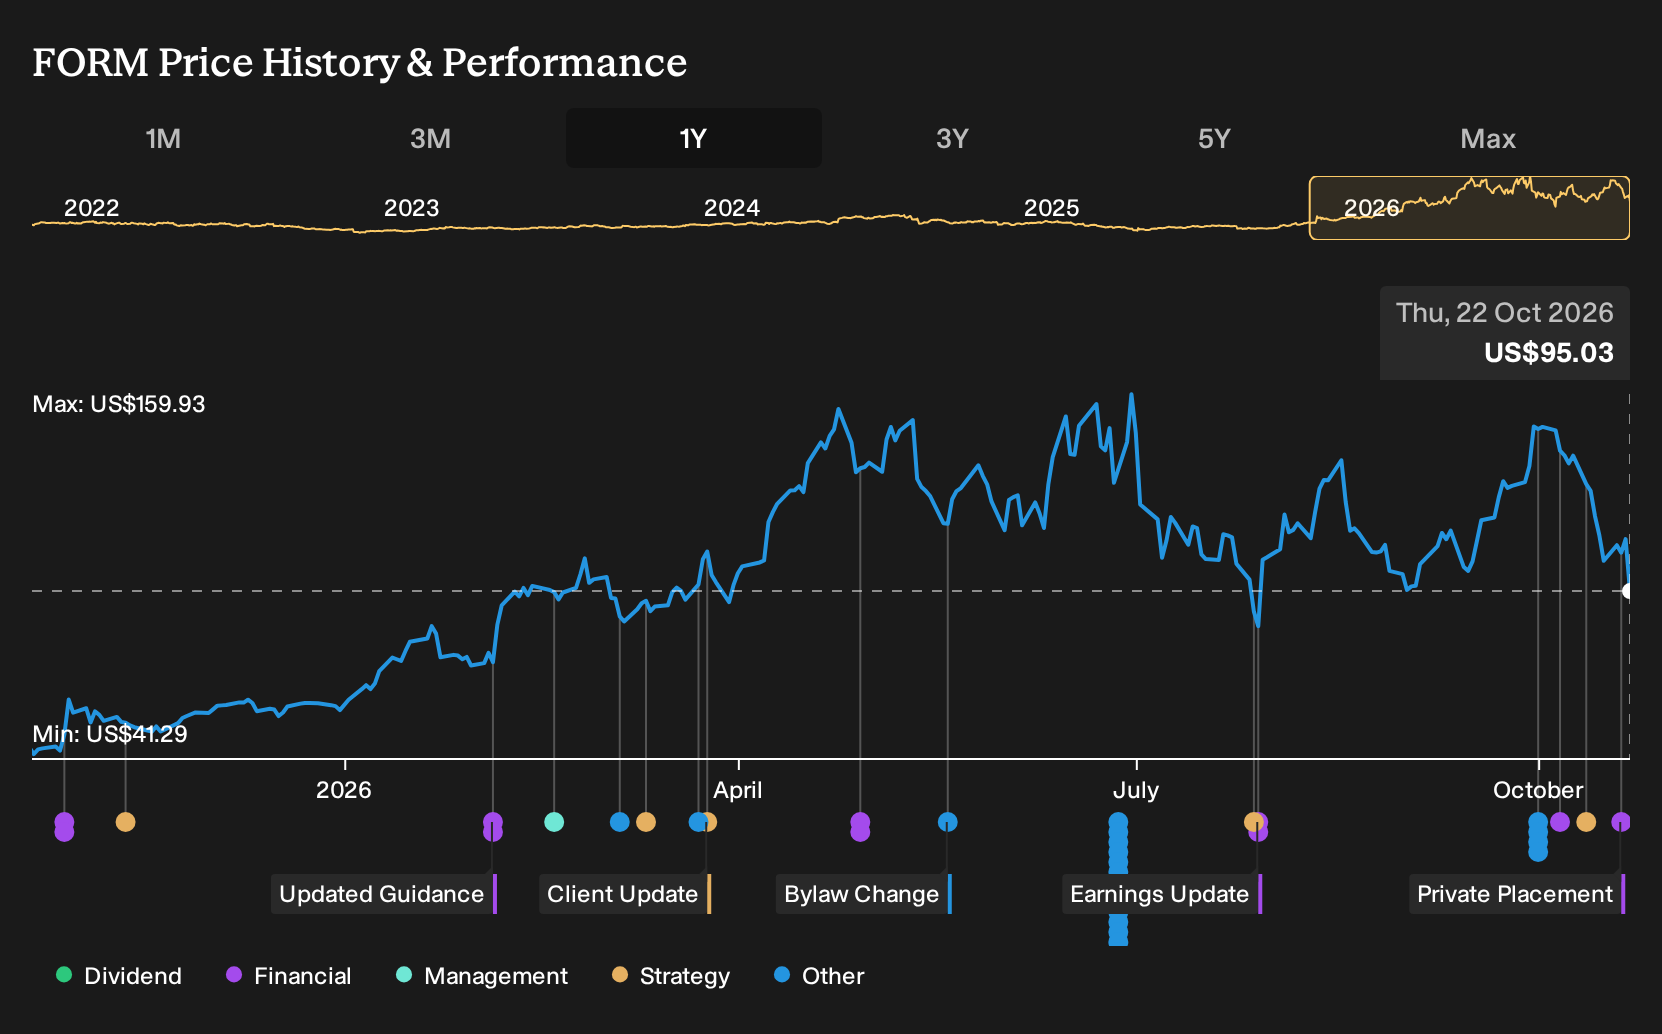
Exploring Other Perspectives
Some of the most optimistic analysts focus on FormFactor’s capacity buildout itself as the key catalyst, expecting about US$1.9b of revenue and US$597.5m of earnings by 2029, even before factoring in the Farmers Branch news. You can see how far opinions stretch, so treat this as a prompt to explore multiple narratives, not a final verdict.
Explore 3 other FormFactor fair value estimates, including one that suggests as much as 119% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your FormFactor research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for FormFactor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FormFactor's overall financial health at a glance.
Looking for more investment ideas beyond FormFactor?
If the FormFactor story has sharpened your view on where testing and AI hardware might go next, it can help to widen the lens and line up a few other candidates that fit your risk profile and income needs.
- For investors hunting for mispriced opportunities with solid fundamentals, start by scanning a 29 high quality undervalued stocks that align with disciplined, value driven criteria.
- If capital preservation and steadier profiles matter more to you than chasing every AI theme, consider filtering for 30 resilient stocks with low risk scores that score well on resilience.
- Those who prefer financial robustness and cleaner balance sheets can shortlist companies from a list of solid balance sheet and fundamentals (26 results) to anchor the core of a portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com