
Frontdoor (FTDR) As Non Warranty Growth Fuels The Undervalued Case
Frontdoor (FTDR) drew fresh attention after its recent share move, with the price closing at $86.03. Investors are weighing that shift against solid annual figures for revenue, net income, and multiyear total returns.
That sharp 6.41% 1 day share price return sits on top of a strong run, with the stock posting a 20.34% 90 day share price return and a 50.82% year to date share price return, while total shareholder return over five years sits at 105.72%. This points to momentum that has been building rather than fading as investors reassess Frontdoor’s growth potential and risk profile.
Scan how Frontdoor’s momentum compares with hand picked 29 high quality undervalued stocks that pair strong fundamentals with market skepticism on price.
After a surge like this and a market value of about US$5.6b, the obvious tension is clear. Does Frontdoor still offer a favourable risk reward, or has the easy upside already been used up as valuation stretches?
Most Popular Narrative: 11.7% Undervalued
On the widely followed view of Frontdoor, a fair value of $97.40 sits above the latest $86.03 close. This puts the recent rally in a different light.
Expansion of non warranty offerings, with the HVAC upgrade program scaling from US$13 million to an expected US$170 million of annual revenue in four years and non warranty revenue growing more than 19% year over year in early 2026, gives Frontdoor a template to add further trades and increase total revenue and EBITDA.
See why 8 investors see Frontdoor as 12% undervalued.
Result: Fair Value of $97.40 (UNDERVALUED)
Still, Frontdoor’s reliance on promotional direct to consumer pricing and heavier marketing spend could squeeze margins if membership or revenue outcomes fall short.
Find out about the key risks to this Frontdoor narrative.
Another View: Multiples Put Frontdoor On A Richer Hook
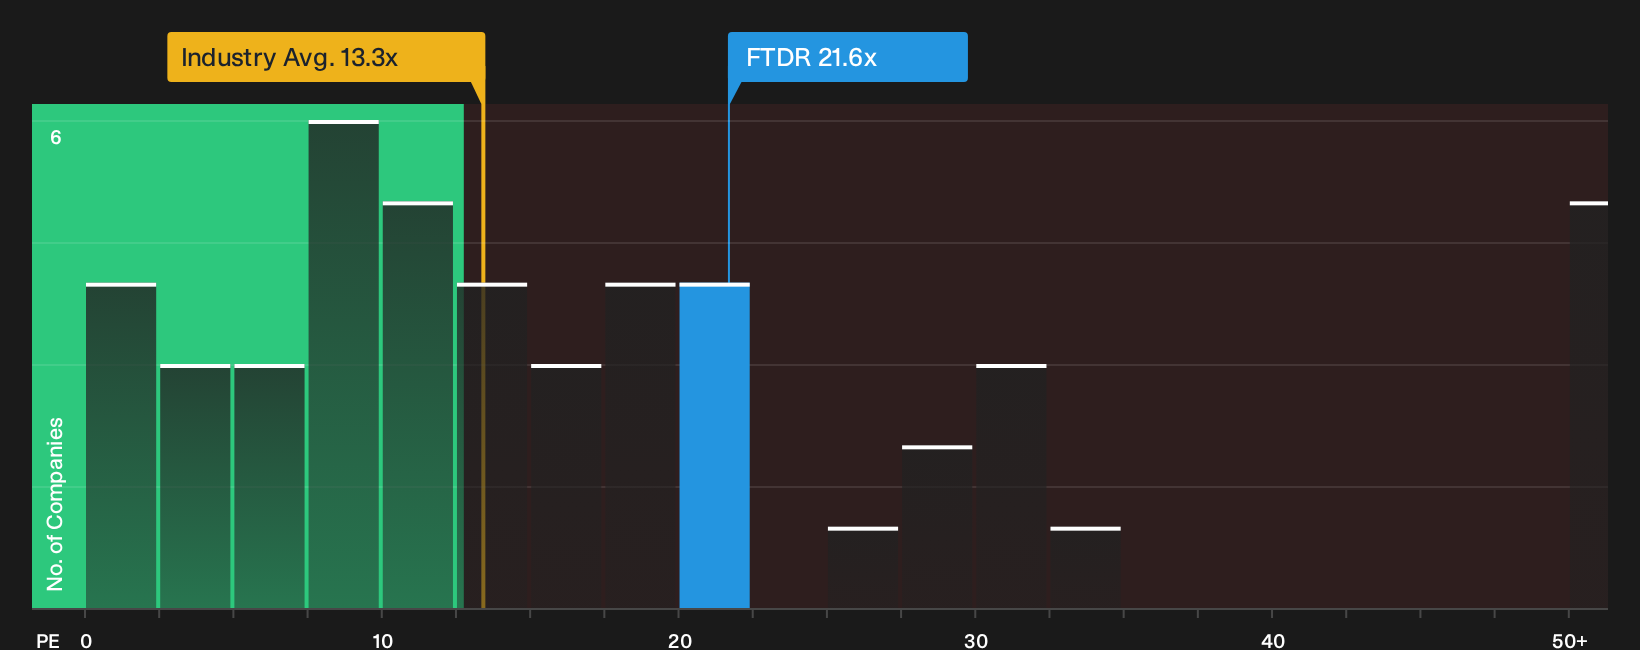
The story shifts when the focus moves from fair value estimates to simple earnings multiples. Frontdoor trades on a P/E of 21.6x, compared with a fair ratio of 19x, a Consumer Services industry average of 13x and a peer average of 17.1x. That pricing leans toward optimism. Are you comfortable paying a premium if growth forecasts stay modest?
To see how that premium could evolve if sentiment or earnings expectations change, take a closer look at the valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Frontdoor’s valuation and outlook can look exciting or uncomfortable, depending on your risk appetite. Move quickly, review the data for yourself, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Frontdoor?
If Frontdoor has you thinking harder about where you put your money next, do not stop here. Broader ideas can sharpen your overall portfolio decisions.
- Target resilient cash generators by reviewing a list of solid balance sheet and fundamentals (26 results) that can help anchor your portfolio when sentiment swings.
- Hunt for mispriced opportunities with a 29 high quality undervalued stocks that screens for quality businesses trading at what may be discounted valuations.
- Build a watchlist of potential income plays using a 6 dividend fortresses that highlights higher yielding options for investors who want regular cash returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com