
Unicharm (TSE:8113) Could Be 35% Undervalued As East Africa Expansion Takes Shape
Unicharm (TSE:8113) has transitioned its East African operations to a direct sales model through SOFY UNICHARM EAST AFRICA LIMITED, a joint venture with Toyota Tsusho, aiming to deepen its reach across Kenya and neighboring markets.
Recent trading has been constructive for Unicharm, with a 30-day share price return of 6.12% and a year-to-date share price gain of 13.65% pointing to building momentum at the current ¥1,019.0 level, even though the 3-year total shareholder return has declined 37.67% and the 5-year total shareholder return is down 29.37%.
Scan other consumer and hygiene players moving on similar regional growth stories by reviewing the hand picked 72 high quality undiscovered gems alongside Unicharm in your watchlist.
Unicharm now pairs a direct East Africa push with a share price that has moved ahead in the short term but still lags over three and five years. Is that recent strength already pricing in the opportunity, or not yet?
Price-to-Earnings of 27.2x: Is it justified for Unicharm?
Unicharm trades on a P/E of 27.2x, which sits above both its peers and the broader Asian household products group, even with the share price at ¥1,019.0.
The P/E ratio compares what investors are currently paying per share to the earnings that Unicharm generates per share. For a consumer and hygiene business with established brands and a wide footprint across Japan, Asia, China and other regions, this yardstick helps you judge how much the market is willing to pay for its profit profile.
At 27.2x, investors are paying more for each yen of Unicharm earnings than the estimated fair P/E of 31.2x suggests the market could move toward. That gap implies the valuation is closer to the lower end of what the SWS fair ratio model indicates for the business, even though the current P/E is still well above the Asian Household Products industry average of 16.1x and the peer group at 21.1x. The market is pricing Unicharm at a premium to rivals, and that premium already reflects higher expectations for future profits.
Explore the SWS fair ratio for Unicharm.
Result: Price-to-Earnings of 27.2x (OVERVALUED)
Still, the premium on Unicharm could come under pressure if earnings momentum slows or if higher input costs squeeze profitability more than investors currently expect.
Find out about the key risks to this Unicharm narrative.
Another View: What The SWS DCF Says About Unicharm
The P/E suggests Unicharm trades rich against peers, yet the SWS DCF model paints a different picture. With the shares around ¥1,019 and an estimated future cash flow value of ¥1,569.07, the stock screens as trading about 35.1% below that cash flow based fair value. Which signal do you trust more when the two tools disagree?
Look into how the SWS DCF model arrives at its fair value.
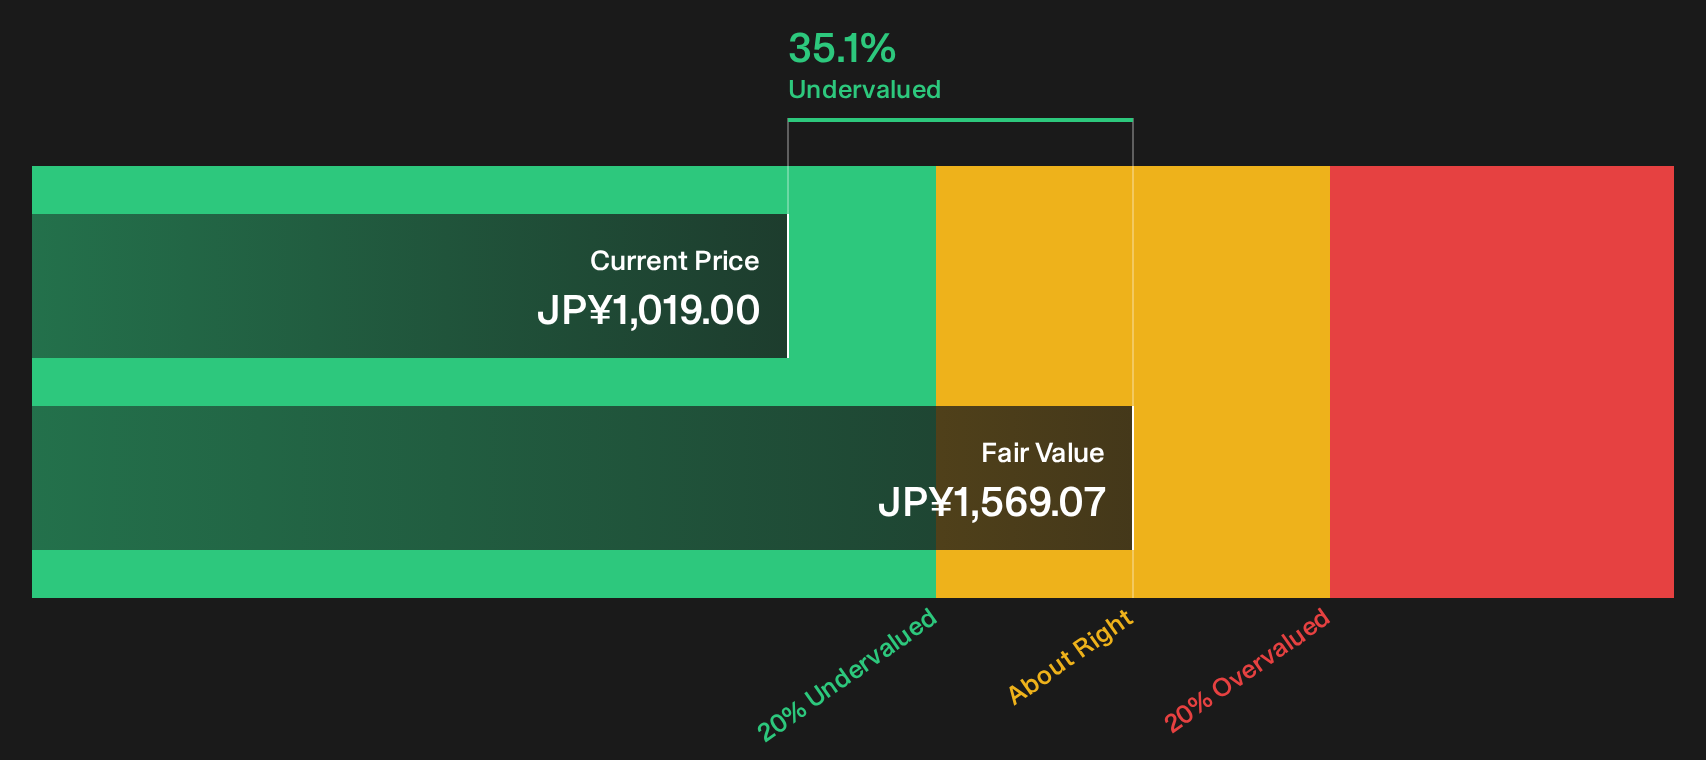
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Unicharm for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Unicharm is mixed, which is exactly when it can help to review the numbers yourself and decide how convincing the story looks to you. To see what optimistic investors are focusing on right now, start with the 3 key rewards
Looking for more Unicharm investment ideas?
If Unicharm has your attention, do not stop here. Broaden your watchlist with a few targeted screens that surface different types of opportunities.
- Target steadier opportunities by scanning 22 resilient stocks with low risk scores which may help cushion your portfolio when volatility picks up.
- Hunt for quality at a discount by reviewing the 15 high quality undervalued stocks that match your return and risk preferences.
- Strengthen your core holdings by checking the list of solid balance sheet and fundamentals (23 results) so you do not miss sturdier businesses hiding in plain sight.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com