
Mosaic (MOS) Stock Still Looks Reasonable As Shares Fell 53%
Mosaic has seen its share price fall sharply in recent years, and that slide puts fresh focus on a simple question for investors who still follow the stock. Is the current US$17.27 price tag adequately supported by the fertilizer producer's sales base?
- The stock is down 53.2% over the past 5 years, which raises the question of whether the market is now giving Mosaic too little or too much credit for its revenue profile.
- Recent coverage has highlighted rising input costs, production cuts and higher debt, which can all feed directly into how much value investors choose to place on each dollar of Mosaic's sales.
- The analysts covering Mosaic have run their own numbers. See what analysts think Mosaic's shares could be worth.
The issue now is whether Mosaic's current market value is reasonably aligned with the sales it is generating today and what those revenues could support over time.
If you want to stress test this same sales based question beyond Mosaic, you can compare it directly with 29 high quality undervalued stocks.
Is Mosaic a Bargain on Sales?
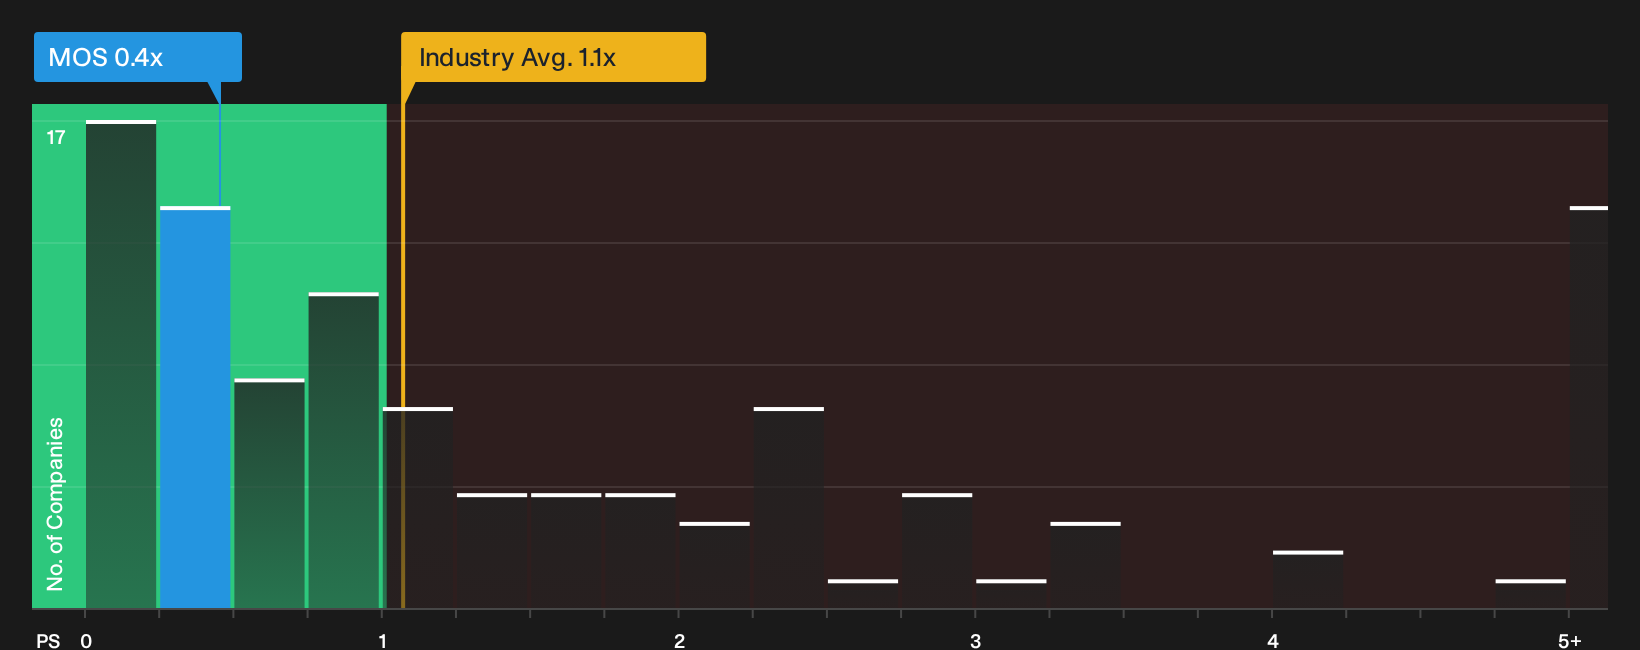
For Mosaic, a sales-based yardstick like the P/S ratio often gives a cleaner read than earnings metrics that can swing around with commodity cycles. At the current share price, Mosaic trades on a P/S of about 0.4x, which sits well below the Chemicals industry average of roughly 1.1x and also under the broader peer group at about 1.5x.
The fair multiple model, which adjusts for factors like Mosaic's margins, scale and risk, points to a higher P/S level than where the stock trades today. As a result, the shares screen undervalued on this yardstick. Because recent coverage has focused on higher costs, production cuts and more debt, the discount suggests investors are placing a low value on each dollar of Mosaic's revenue relative to similar businesses. Explore the numbers behind Mosaic's P/S valuation.
The Mosaic Narrative: What Would Justify Today's Price?
Mosaic's low P/S raises the real question of what kind of future the current share price is already baking in, and Simply Wall St Narratives are designed to spell out which combinations of growth, margins and earnings would need to play out for the stock to be worth much more or much less from here on the Community page. Rather than a single multiple or model readout, each scenario lays out the assumptions behind its estimate of fair value so you can track those against Mosaic's actual results as they come through.
One of the top community narratives on Mosaic: roughly fairly valued
"Bearish analysts expect Mosaic to struggle with structurally higher compliance and input costs as sulfur disruptions keep phosphate production curtailed."
Discover why this Narrative puts Mosaic at roughly fairly valued.
Mosaic’s valuation is only part of the story
Before treating Mosaic’s current pricing as your main reference point, it is worth knowing that Simply Wall St’s broader checks have flagged specific areas of concern that deserve your attention alongside the multiples. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com