
Can Phillips 66 (PSX) Keep Justifying Its Price After 345% Gains?
Phillips 66 has delivered a powerful run over the past few years, which puts fresh scrutiny on whether the current share price still lines up with the earnings behind it. With the stock having already rewarded long term holders, the question now is what that track record means for anyone looking at the valuation today.
- Over the past 5 years, Phillips 66 has returned about 344.7%, so a lot of future earning power may already be baked into expectations.
- The latest dividend increase and focus on debt reduction signal management's confidence in cash generation, which can shape how much investors are willing to pay for each dollar of profit.
- The analysts covering Phillips 66 have run their own numbers. See what analysts think Phillips 66's shares could be worth.
The issue now is whether Phillips 66's current price is adequately explained by the earnings it produces today and what investors expect those profits to look like over time.
If you are weighing Phillips 66 against other opportunities that also focus on earnings power, a targeted screener built around 29 high quality undervalued stocks can be a useful next step in your research.
Is Phillips 66 Fairly Priced on Earnings?
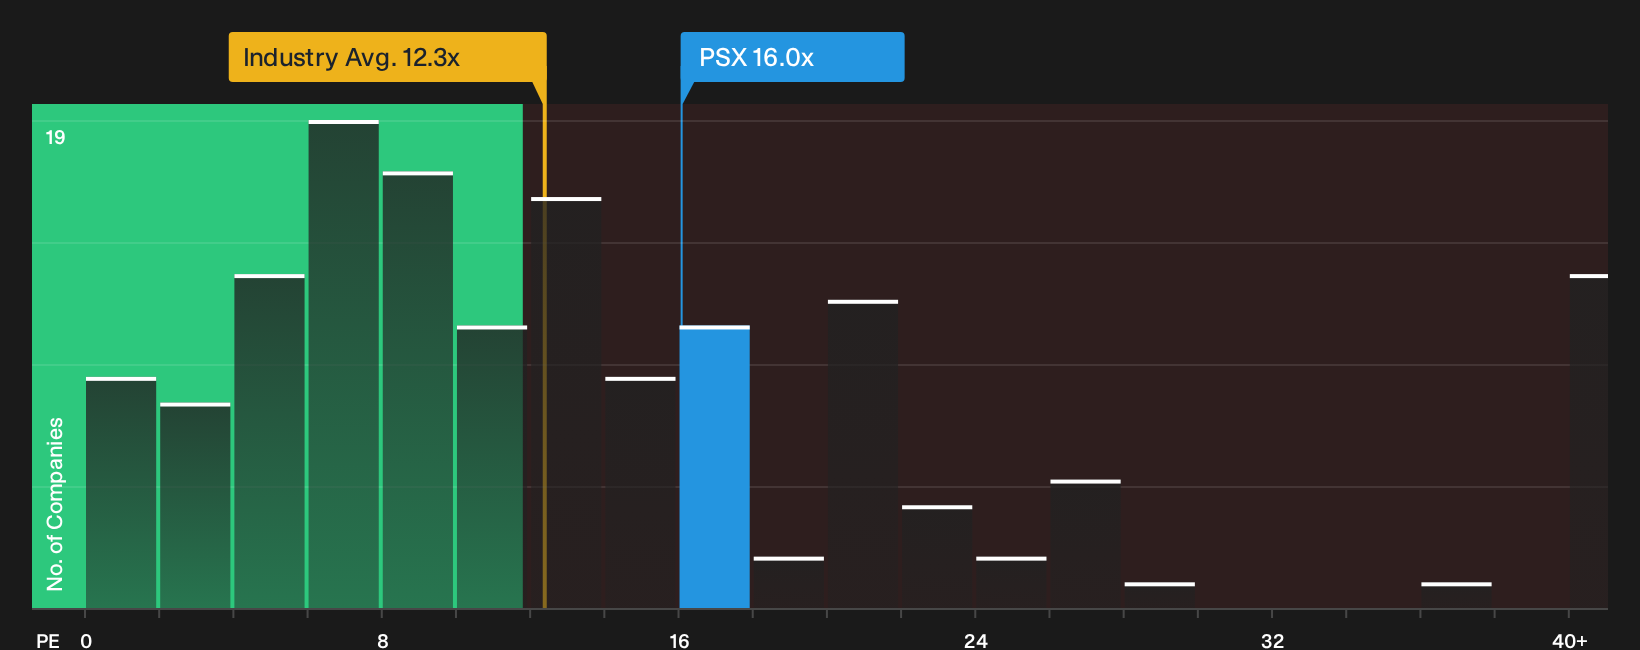
The P/E multiple fits Phillips 66 because earnings still sit at the center of how investors frame refiners and midstream operators. The stock trades on a P/E of 16.0x, compared with about 12.3x for the wider Oil and Gas industry and roughly 10.7x for its peer group. That puts a clear premium on the shares relative to sector benchmarks and closer to the level investors might usually reserve for businesses with more resilient or differentiated profit streams.
Because the latest dividend hike and debt reduction push have raised confidence in Phillips 66's cash generation, the current P/E lines up broadly with the multiple suggested by a more tailored fair value framework that weighs growth, margins, scale and risk. The shares trade close to that implied level rather than at a clear discount or a clear stretch valuation, so you need to judge whether the quality and durability of future earnings justify paying more than the simple industry averages would indicate. Despite the recent lift from stronger refining margins and higher earnings estimates, the P/E still prices Phillips 66 as roughly in line with what that more detailed model would point to as a fair range for the stock. Explore the numbers behind Phillips 66's P/E valuation.
The Phillips 66 Narrative: What Would Justify Today's Price?
Narratives for Phillips 66 pick up where the valuation puzzle leaves off, spelling out in plain terms which paths for growth, margins and earnings would need to play out for the shares to command a meaningfully higher or lower price than today. Rather than a single multiple or model line, each Narrative lays out the moving parts behind its view of fair value so you can track those assumptions against actual results over time on Simply Wall St's Community page.
Community views on Phillips 66 are split between one group that sees extra upside still on the table and another that thinks much of the story is already captured in the price.
Bull case: 17% undervalued
"Ongoing cost improvement in Refining, with a targeted adjusted controllable cost of about US$5.50 per barrel by year end 2027 and over 300 efficiency initiatives, is intended to structurally lower the cost base..."
Discover why this Narrative puts Phillips 66 at 17% undervalued.
Bear case: roughly fairly valued
"If the equity market has already priced in most of the margin strength and operational improvements and views Phillips 66 as somewhat overvalued, any slowdown in execution or sentiment could trigger a share price decline..."
Explore why this Narrative puts Phillips 66 at roughly fairly valued.
The share price is only one piece of the Phillips 66 puzzle
You have seen how the current valuation stacks up against today’s earnings, but the next question is how professional analysts sketch out Phillips 66 a few years from now. Explore where analysts expect Phillips 66 to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com