
Does Lennar (LEN) Stock Look Undervalued After Mixed Signals?
Lennar shares closed at US$84.45 and the stock has given up 32.2% over the past year, which puts fresh focus on whether that current price still lines up with the earnings power of the homebuilder. With investors weighing both new projects and legal questions, the key issue now is how much of Lennar's underlying profit stream is already reflected in the valuation.
- The 32.2% share-price decline over the past 12 months raises the question of whether the market is reassessing what Lennar's earnings are worth.
- The new attainable housing project in downtown Las Vegas may support expectations for future homebuilding volume and cash generation, while the ongoing securities investigation can influence how investors think about the reliability and risk attached to those earnings.
- Your read on Lennar is one view; the desks covering it have another. See what analysts think Lennar's shares could be worth.
The issue now is whether Lennar's current share price is justified by the earnings it is generating today and what investors expect those profits to look like in the future.
If you are questioning whether Lennar's recent 32.2% share price decline fairly reflects its earnings power, it can help to compare that same earnings lens across 29 high quality undervalued stocks.
Does Lennar Look Undervalued on Earnings?
P/E works well for Lennar because the business is already profitable and investors tend to anchor housing stocks to near term earnings.
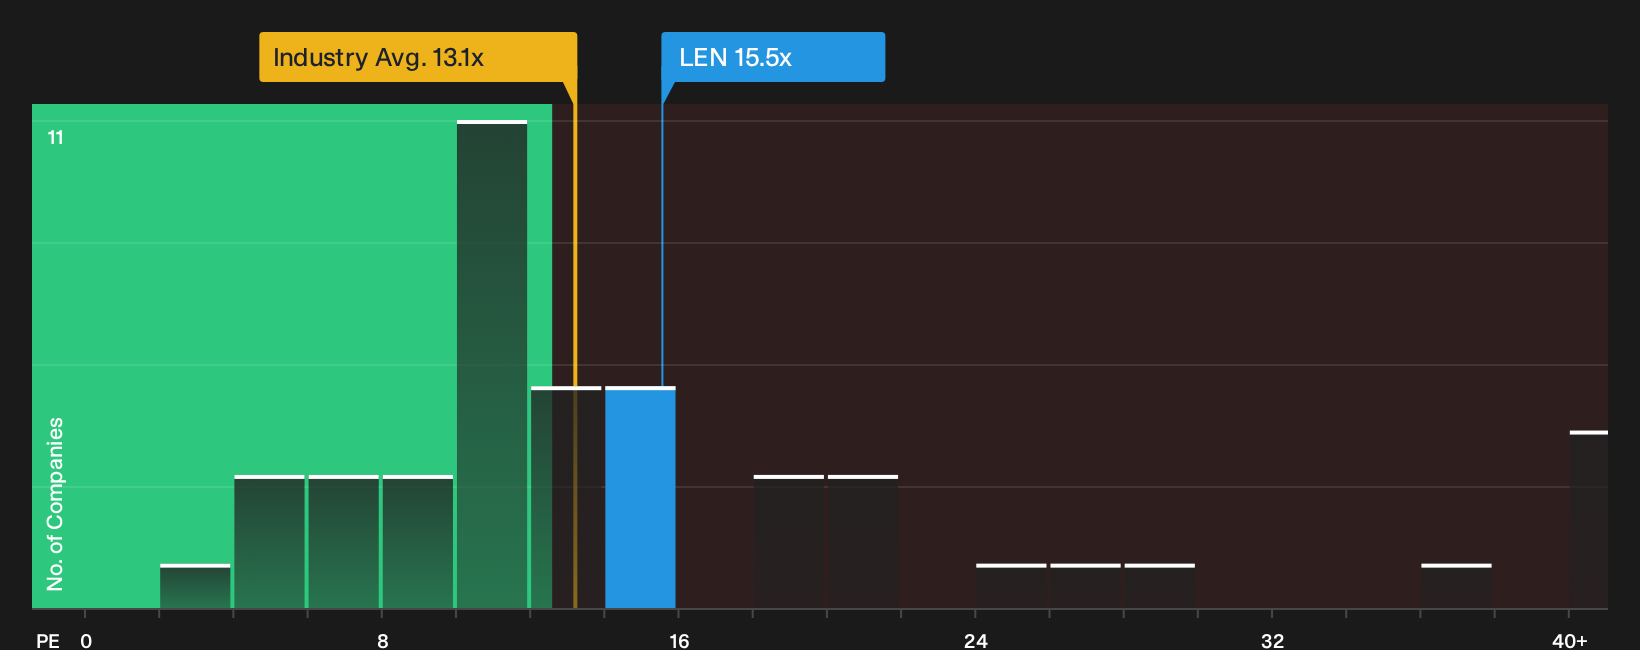
On this lens, Lennar trades on a P/E of 15.5x compared with about 13.1x for the wider Consumer Durables sector and a peer average of roughly 13.1x. That means the shares change hands at a premium to both the industry and direct comparables, even after the recent share price pullback.
The fair value model, which estimates the P/E that might fit Lennar's own mix of growth profile, margins, size and risk, points to a higher multiple than where the stock trades today. On this framework, the current 15.5x therefore screens as undervalued. Because the securities fraud investigation has pressured sentiment recently, the present discount to that tailored fair P/E suggests the market is giving extra weight to headline and legal risk rather than to the earnings stream investors are paying for. Explore the numbers behind Lennar's P/E valuation.
The Lennar Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Lennar valuation puzzle leaves off. They spell out which combinations of growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price, and set each scenario against a clear view of how Lennar’s future profitability and risks might evolve that you can revisit as fresh information comes through.
Community views on Lennar are split between those who see the asset light model as underappreciated and those who think current pricing already captures the moving parts.
Bull case: 21% undervalued
"The record-low construction cycle time of 116 days in Q3 2026, together with construction cost per square foot around US$80, points to further room for a manufacturing-style approach to free up working capital and support net margin and earnings quality..."
Discover why this Narrative puts Lennar at 21% undervalued.
Bear case: 8% overvalued
"Rising land and land banking costs, including higher land cost per homesite and growing option maintenance fees tied to the asset light model, could prevent Lennar from sustaining its recent gross margin and net margin levels..."
Explore why this Narrative puts Lennar at 8% overvalued.
One more Lennar check that belongs beside the price tag
Valuation only tells part of the story for Lennar, because the research checks behind this review have also surfaced specific risk flags that investors may want to examine before leaning on the numbers alone. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com