
Exploring 3 Undervalued Small Caps With Insider Action Across Regions
Over the last 7 days, the United States market has experienced a slight decline of 1.2%, although it remains up by 11% over the past year with earnings projected to grow by 17% annually. In this context, identifying stocks that are potentially undervalued and exhibit insider activity can be an intriguing strategy for investors seeking opportunities in various regions across the country.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.7x | 0.5x | 28.94% | ★★★★★★ |
| Financial Institutions | 9.9x | 3.3x | 23.10% | ★★★★★☆ |
| Enovis | NA | 0.5x | 36.84% | ★★★★★☆ |
| Bank of Marin Bancorp | NA | 7.2x | 32.42% | ★★★★☆☆ |
| Bank of the James Financial Group | 11.4x | 2.6x | 22.93% | ★★★★☆☆ |
| Union Bankshares | 9.1x | 2.0x | 27.89% | ★★★★☆☆ |
| German American Bancorp | 13.5x | 5.1x | 23.52% | ★★★☆☆☆ |
| Citizens Community Bancorp | 16.2x | 3.6x | 9.86% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.5x | 2.6x | 7.84% | ★★★☆☆☆ |
| Surgery Partners | NA | 0.6x | 19.19% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Surgery Partners (SGRY)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Surgery Partners operates a network of surgical facilities, including ancillary services, with a market capitalization of approximately $3.38 billion.
Operations: The company generates revenue primarily from its surgical facilities, with a recent revenue figure of $3.37 billion. The cost of goods sold (COGS) for the same period was $2.61 billion, resulting in a gross profit margin of 22.51%. Operating expenses and non-operating expenses were significant contributors to the financial results, impacting net income figures over time.
PE: -23.3x
Surgery Partners, a player in the ambulatory surgical center industry, is navigating its growth strategy with an eye on acquisitions while maintaining financial discipline. Despite a net loss of US$15 million in Q2 2026, they forecast earnings to grow at 73.49% annually. Revenue guidance for 2026 stands between US$3.08 billion and US$3.18 billion after divesting non-core assets. Insider confidence remains evident as leadership actively seeks strategic acquisitions, aiming to capitalize on their unique market position by year-end 2026.
- Unlock comprehensive insights into our analysis of Surgery Partners stock in this valuation report.
Evaluate Surgery Partners' historical performance by accessing our past performance report.

Brandywine Realty Trust (BDN)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Brandywine Realty Trust is a real estate investment trust that focuses on the ownership, management, and development of urban town center and transit-oriented office properties, with a market capitalization of approximately $1.03 billion.
Operations: Brandywine Realty Trust generates revenue primarily through its real estate operations, with a notable gross profit margin reaching as high as 60.85% in recent periods. The company faces significant costs, including cost of goods sold and operating expenses which include general and administrative expenses consistently around $36 million. Additionally, non-operating expenses have been volatile, impacting net income margins significantly over time.
PE: -3.6x
Brandywine Realty Trust, a smaller company in the real estate sector, shows potential for those eyeing undervalued stocks. Despite reporting a net loss of US$22.03 million for Q3 2026, this is an improvement from last year's US$25.92 million loss. Their sales and revenue have both seen slight increases year-over-year, hinting at gradual recovery. Insider confidence is evident with recent share purchases by executives over the past few months, reflecting belief in future prospects despite lowered earnings guidance for 2026.
- Click to explore a detailed breakdown of our findings in Brandywine Realty Trust's valuation report.
Learn about Brandywine Realty Trust's historical performance.
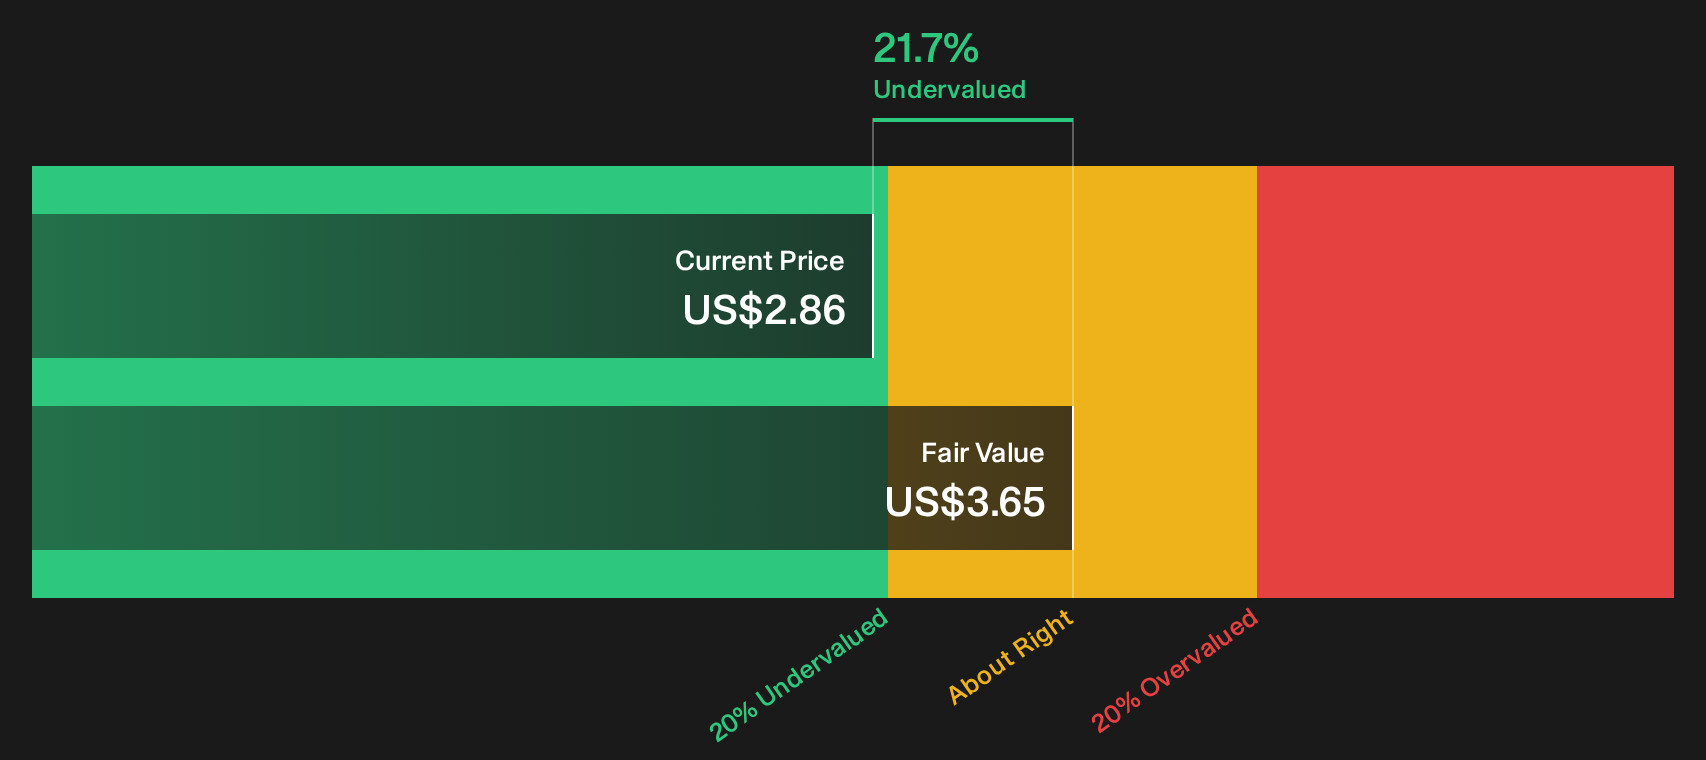
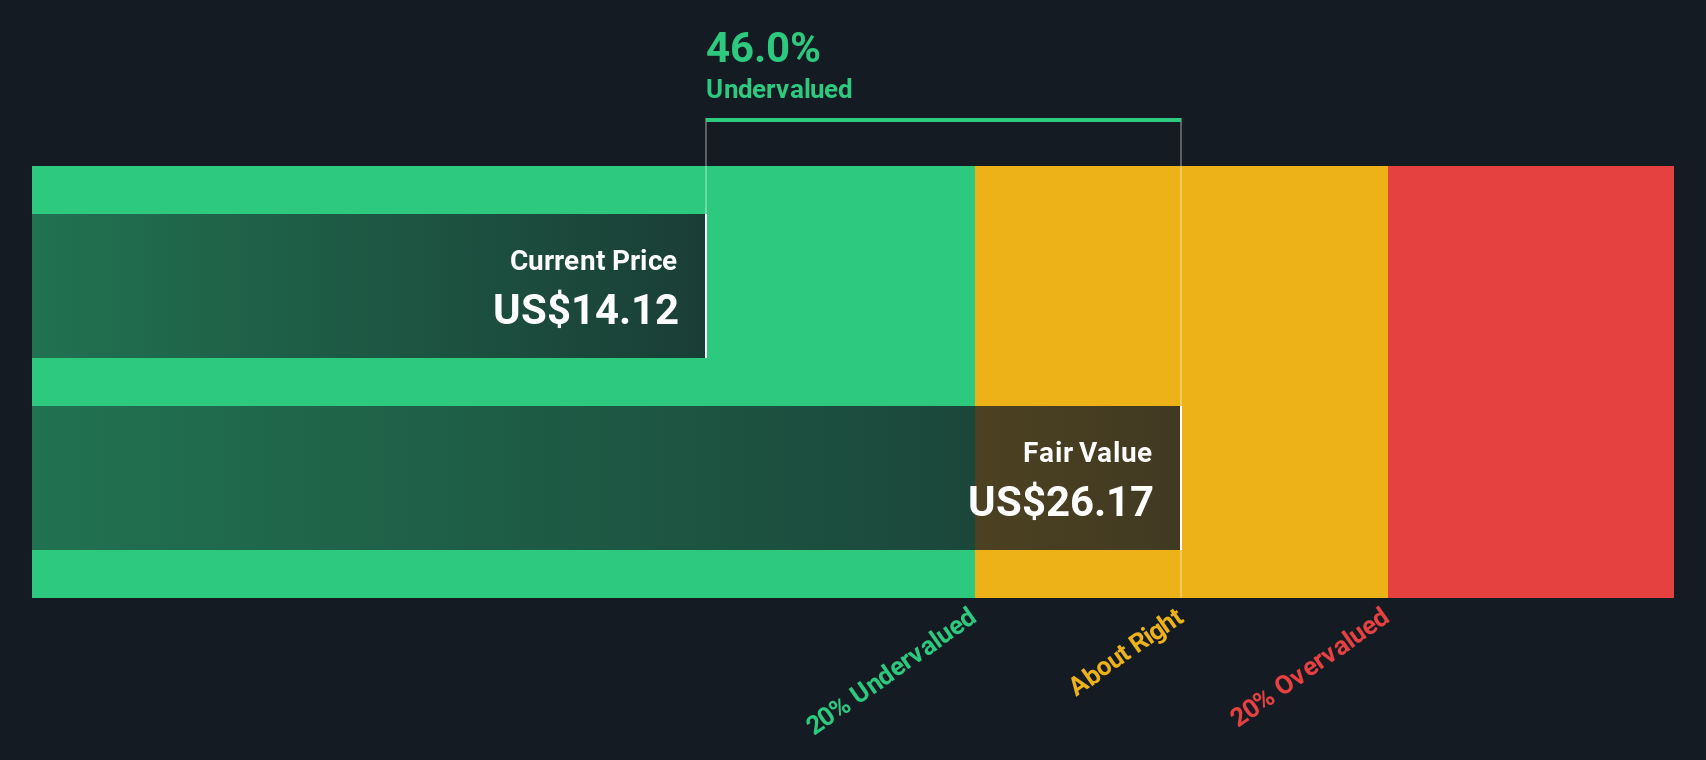
UMH Properties (UMH)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: UMH Properties is a real estate investment trust specializing in the ownership and operation of manufactured home communities, with a market capitalization of approximately $1.08 billion.
Operations: The company generates revenue primarily from the ownership and operation of manufactured home communities, with a recent revenue figure of $271.05 million. Over time, its gross profit margin has shown an upward trend, reaching 54.82% in the latest period. Operating expenses are significant and include costs such as depreciation and amortization, which amounted to $70.40 million recently.
PE: 123.2x
UMH Properties, a player in the manufactured housing sector, is capturing attention for its perceived value. Erez Asset Management's recent activism highlights UMH's persistent trading at a discount to net asset value. Insider confidence is evident with strategic discussions on governance and potential sales. Despite earnings forecasts of 11% annual growth, UMH faces challenges with high-risk funding and interest coverage issues. Still, their innovative housing solutions and dividend affirmations suggest resilience amidst industry shifts.
- Take a closer look at UMH Properties' potential here in our valuation report.
Gain insights into UMH Properties' historical performance by reviewing our past performance report.
Summing It All Up
- Explore the 66 names from our Undervalued US Small Caps With Insider Buying screener here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com