
Tomra Systems (OB:TOM) Could Be 62% Undervalued Following Q3 Growth And UK Vending Deal
Tomra Systems (OB:TOM) just put fresh numbers on the table for the third quarter of 2026, pairing higher sales and net income with a new UK reverse vending rollout opportunity.
The recent gains have caught the eye because Tomra Systems’ share price is up 4.37% over the past week and 1.53% over the past month. However, the year-to-date share price return is still down 31.79% and the 1-year total shareholder return is down 26.47%. The longer-term picture is mixed, with a 14.34% 3-year total shareholder return but a 63.60% decline over five years. This suggests short-term momentum is improving after a difficult stretch as investors reprice both growth potential and risk following the Q3 report and UK reverse vending agreement.
Spot opportunities beyond Tomra Systems by scanning a curated 193 high quality undervalued stocks that share solid cash flows and balance sheet strength.The Q3 rebound and UK contract potential are now partly reflected in the share price. The next step is to assess how much upside the valuation still allows for Tomra Systems.
Most Popular Narrative: 62% Undervalued
Tomra Systems closed at NOK93.10, while the central narrative on Simply Wall St anchors fair value at NOK243.43, so the gap between price and perceived worth is wide and hard to ignore.
Tomra Systems ASA is a Norwegian based industrial machinery Maker which get most of its revenues from Machines and sensors of collection (56%), food (25%) and recycling waste materials (17%) with a total 2025 net revenue of €1318 M (€1,318 B). Now the company is set to benefit from PPWR, which is The European Union's Packaging Waste Regulation (PPWR) that became mandatory on August 12, 2026, setting strict new sustainability, labeling, and reduction standards for all packaging of the EU countries.
See why 5 investors see Tomra Systems as 62% undervalued.
Result: Fair Value of NOK243.43 (UNDERVALUED)
Still, Tomra Systems relies heavily on regulatory rollouts and reverse vending contracts; slower PPWR adoption or delayed tenders could quickly weaken this undervaluation narrative.
Find out about the key risks to this Tomra Systems narrative.
Another View: What Tomra Systems’ P/E Is Telling You
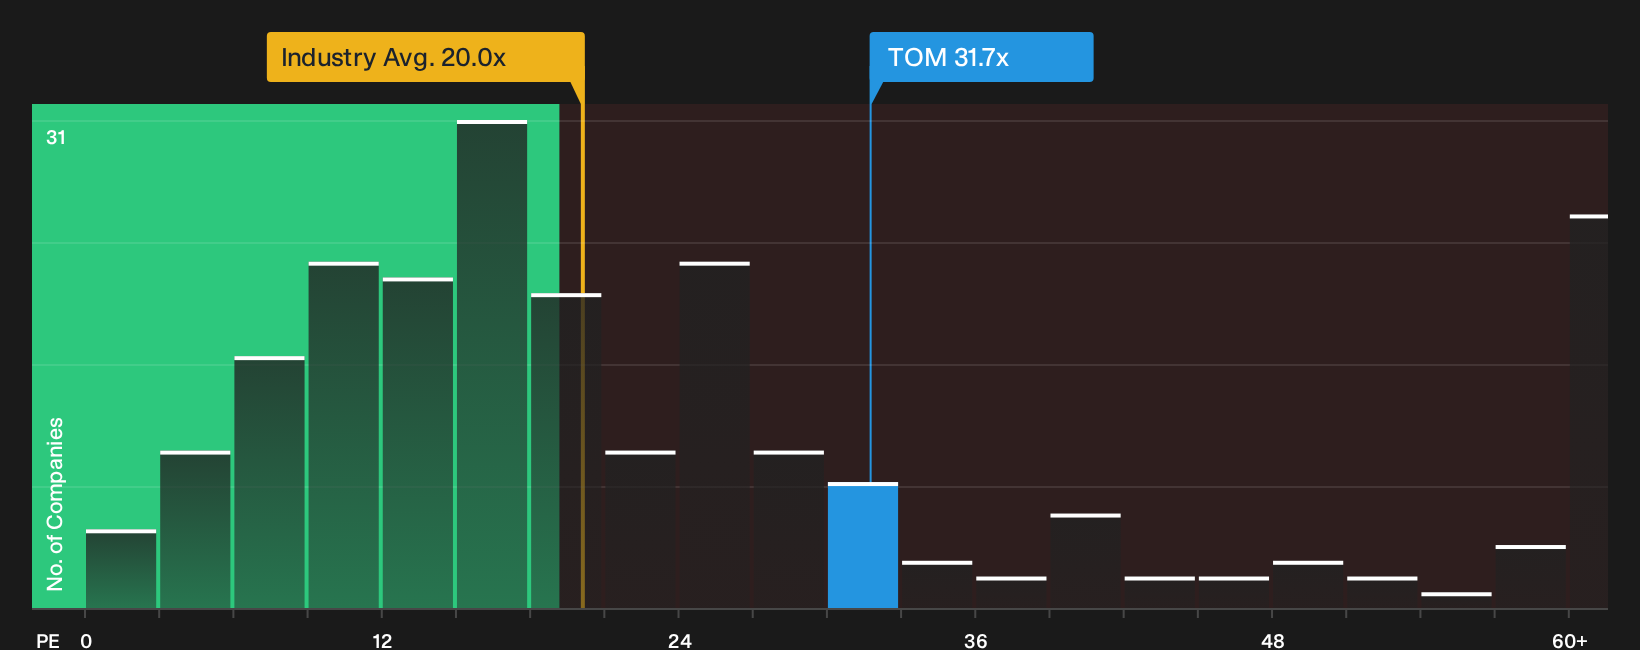
The story looks very different when you move away from fair value models and focus on Tomra Systems’ earnings multiple. The stock trades on a P/E of 31.7x, which is higher than both its peer group at 30.4x and the broader European machinery sector at 20.3x.
Yet the fair ratio suggests a P/E of 39.8x could be more in line with where the market might settle over time. That gap points to valuation risk if growth expectations fade, but it also indicates there could be room for sentiment to narrow the difference. Which side of that trade are you more comfortable owning?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Tomra Systems often create the sharpest opportunities, so consider acting promptly and test the thesis against your own checklist with 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tomra Systems?
If Tomra Systems has sharpened your thinking, do not stop here. Broaden your watchlist now using focused stock ideas sourced directly from the Simply Wall St Screener.
- Target potential mispricings by scanning a curated set of companies that combine quality metrics with appealing valuations through the 193 high quality undervalued stocks.
- Strengthen your focus on resilience by reviewing a 222 resilient stocks with low risk scores that screens for businesses with more stable profiles and fewer red flags.
- Hunt for tomorrow's potential leaders early by checking a 615 high quality undiscovered gems before the crowd rushes in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com