
Johnson & Johnson (JNJ) Unveiled Fresh Cardiology Data, Is The Stock Fully Valued?
Johnson & Johnson (JNJ) is back in focus after fresh data from its VARIPURE and Omny-IRE studies on pulsed field ablation were unveiled at the APHRS 2026 cardiology meeting in Busan.
Those cardiology data land at a time when Johnson & Johnson’s share price has gained 29.06% year to date, including a 3.81% 1-day share price return and 5.66% 7-day share price return. Its 1-year total shareholder return of 42.17% and 3-year total shareholder return of 95.59% point to momentum that recent product launches, dividend affirmations and mixed Q3 earnings are helping to reshape around MedTech expectations and longer-term drug pipeline progress.
See how Johnson & Johnson’s cardiology momentum compares with peers by exploring a curated set of 36 healthcare AI stocks while this part of the market remains in focus.
That kind of move in Johnson & Johnson after mixed earnings and fresh MedTech data can either signal a re-rating of the business or a swing in sentiment. How does the current price reflect that balance?
Most Popular Narrative: 11.2% Overvalued
Johnson & Johnson last closed at $267.61, while the most followed narrative pegs fair value at $240.69. That gap frames recent MedTech questions in a harsher light. That valuation view leans heavily on how management language in Q3 contrasts with what actually showed up in the numbers and product cadence.
Double-digit growth by the end of the decade now functions as connective tissue rather than a milestone with a defined delivery mechanism. It opens the call, closes the call, and recurs inside the Abiomed defense, the MedTech defense, and the capital allocation discussion. Three months ago, the phrase anchored a specific claim about portfolio depth. This time, an analyst has to ask management, on the call itself, whether the phrase still means organic growth or now implicitly includes acquisitions. That a sell-side analyst needed to ask what the company’s signature phrase means is itself the signal.
See why 3 investors see Johnson & Johnson as 11% overvalued.
Result: Fair Value of $240.69 (OVERVALUED)
Still, the Johnson & Johnson story carries pressure points, including MedTech performance that management itself called below internal standards, and a proposed talc settlement that could reshape future capital priorities.
Find out about the key risks to this Johnson & Johnson narrative.
Another Take On Johnson & Johnson’s Value
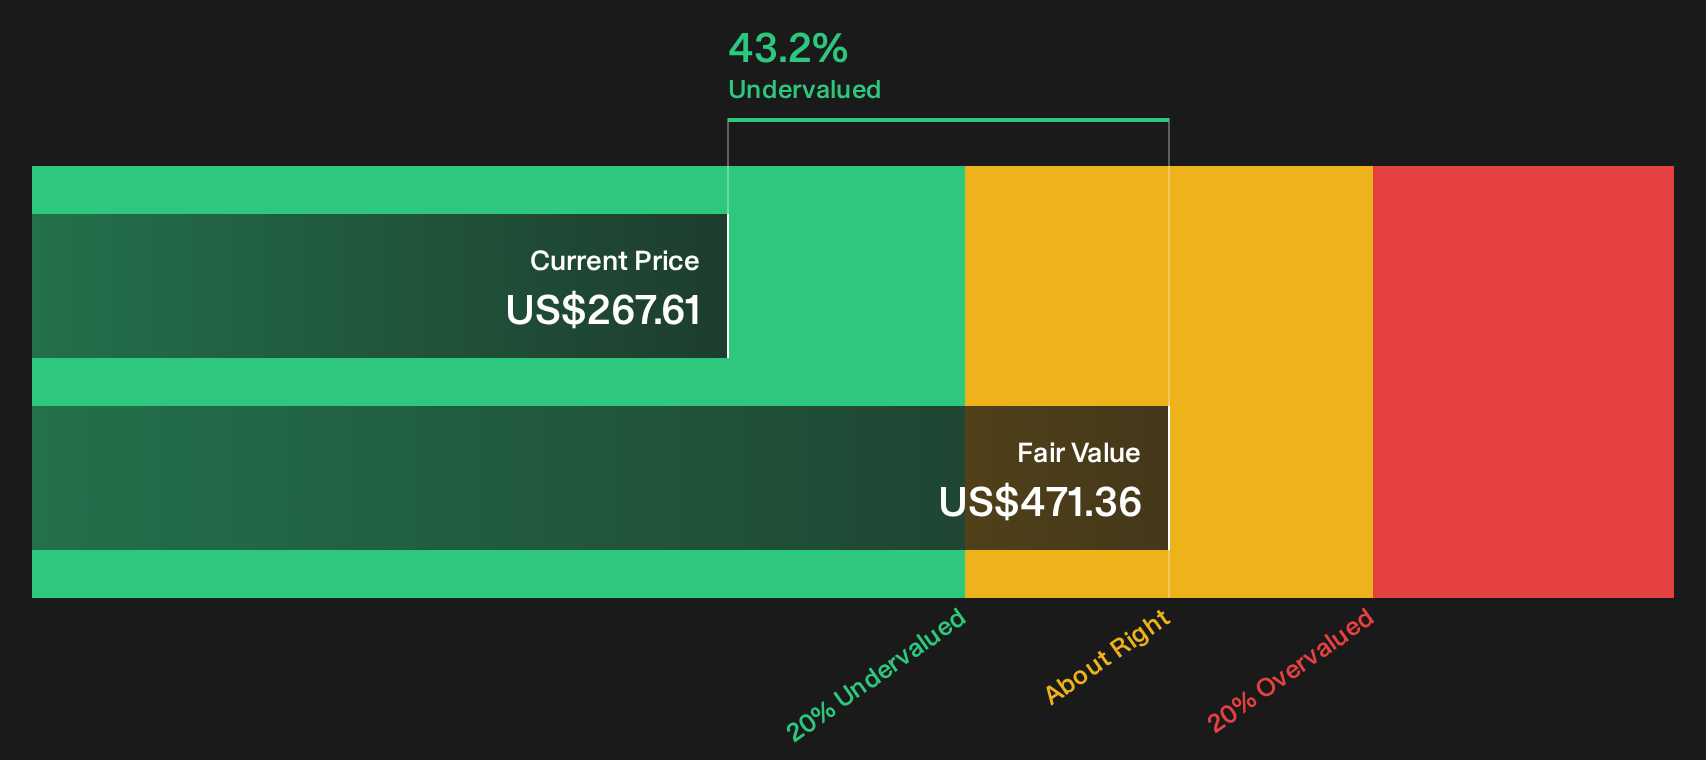
The narrative crowd calls Johnson & Johnson 11.2% overvalued at $267.61 versus a $240.69 fair value, yet the SWS DCF model tells a different story. On that cash flow view, the shares sit below an estimated value of $471.36. Which lens do you give more weight to when price and narrative diverge this far?
To see how that cash flow view is built, and where the key assumptions sit, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Johnson & Johnson is split, which is exactly when it helps to move fast, review the numbers yourself and decide where you stand on the mix of promise and pressure. To weigh both sides in one place, start with 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Johnson & Johnson?
If you only stop at Johnson & Johnson, you miss the chance to stack your watchlist with other potential opportunities that fit your style and risk comfort.
- Target reliable income streams by scanning for potential 6 dividend fortresses that might help anchor your portfolio with recurring cash returns.
- Hunt for potential value opportunities by reviewing a 29 high quality undervalued stocks that combine quality fundamentals with prices below estimated worth.
- Strengthen your downside protection by focusing on a 30 resilient stocks with low risk scores that score well on resilience and financial stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com