
Micron (MU) Stock Looks Fairly Valued With Little Room For Error
Micron Technology has been through a sharp pullback in recent weeks after a huge multi year climb, which puts fresh attention on a basic question for you as an investor. Do the cash flows that Micron can generate over time really support where the stock now trades?
- Over the past 3 years Micron has delivered a very large share price gain of about 12x. As a result, even a small change in expectations for its cash generation can matter a lot for valuation.
- Micron's recent commitments to areas like US critical minerals processing and new memory technologies can affect future free cash flow by influencing capital spending needs, long term supply security and the timing of cash returns to shareholders.
- Prefer to judge Micron Technology on earnings? See why Micron Technology's 11.4x P/E tells a different valuation story.
The issue now is whether Micron's current share price is adequately supported by the cash flows implied by a Discounted Cash Flow (DCF) style intrinsic value estimate.
If you want a second lens on this AI memory story, you can start a shortlist using 55 AI infrastructure stocks.
Does Micron Technology Look Fairly Valued on Cash Flow?
The Discounted Cash Flow (DCF) approach here takes Micron Technology's projected cash generation and brings it back to today using a required return for shareholders. Latest twelve month free cash flow sits at about $52.2b, and the model then assumes that cash generation grows further over the next few years before easing into lower growth by the mid 2030s.
Micron's ten year path in this DCF is not a straight line. Forecasts point to rising free cash flow into the late 2020s, then a cooler phase where annual figures step down from the 2031 peak rather than keep climbing. That pattern helps explain why the model still puts Micron's estimated intrinsic worth broadly in line with the current share price of $856.49. Because the recent sell off tied to CXMT's DRAM progress has highlighted competitive pressure on future memory economics, the fact that the DCF only lands roughly in line with the market price suggests expectations for Micron are already demanding. Find out what Micron Technology could be worth using our Discounted Cash Flow (DCF) estimate.
The Micron Technology Narrative: What Would Justify Today's Price?
Narratives for Micron Technology pick up where the cash flow puzzle leaves off and spell out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than today. Each one treats Micron Technology's implied fair value as a thesis about how the business develops that you can track over time, rather than a static snapshot. They are available on Simply Wall St's Community page.
Community views on Micron Technology split cleanly between those who see an AI powered cash engine and those who think the cycle is being overestimated.
Bull case: 31% undervalued
"Micron Technology has become one of the most important “picks and shovels” companies in the AI buildout, supplying the memory and storage that keep GPUs useful…"
Discover why this Narrative puts Micron Technology at 31% undervalued.
Bear case: 56% overvalued
"The real question is how long pricing power lasts, because more capacity is already planned and being built with increased capex…"
Explore why this Narrative puts Micron Technology at 56% overvalued.
One more Micron Technology signal that could shift your view
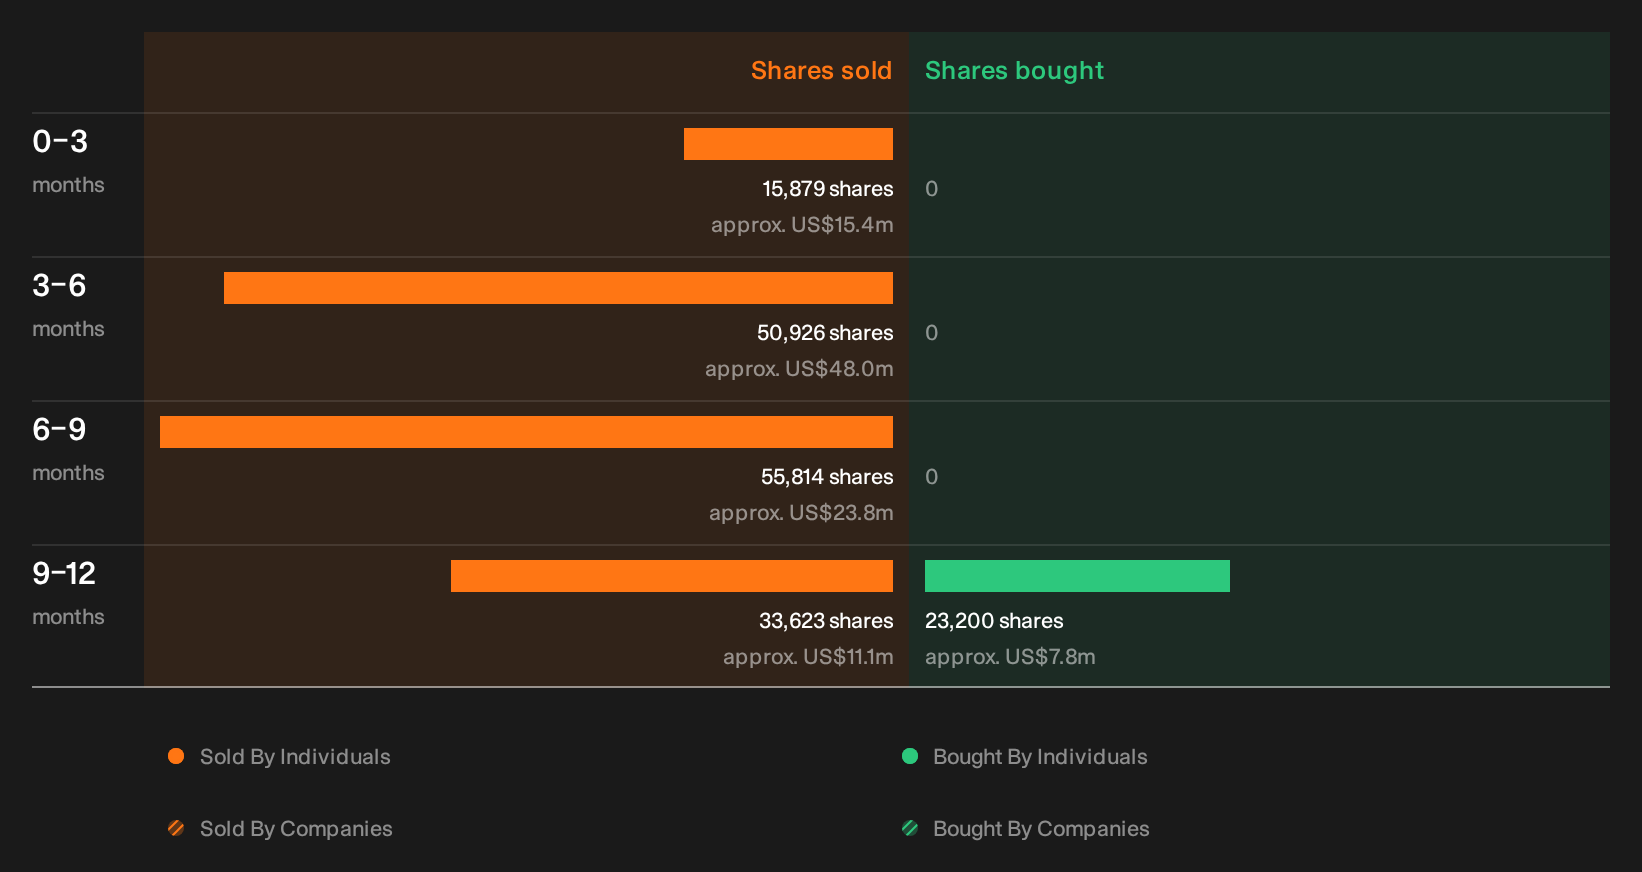
Before you move on from Micron Technology, there is a separate thread to pull on as recent executive share dealings have been flagged by our checks, with the sellers, amounts and possible read throughs still to unpack. See the recent insider selling flagged for Micron Technology.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com