
Is Japan Prime Realty Investment (TSE:8955) Fairly Valued As It Buys In Otemachi And Lifts Dividend?
Japan Prime Realty Investment (TSE:8955) just combined a new property deal in Tokyo’s Otemachi office district with a declared semi-annual dividend of ¥2,150 per unit, giving investors fresh information on income and portfolio direction.
Recent trading has been mixed for Japan Prime Realty Investment. The share price is up 1.33% over the past day and 1.00% across the week, yet down 2.98% over the past month and 13.47% year to date. Meanwhile, the 3 year total shareholder return of 16.47% points to longer term momentum that contrasts with the softer recent trend.
Scan beyond Japan Prime Realty Investment and see how other income-focused real estate plays stack up in our hand picked 29 dividend fortresses.
Japan Prime Realty Investment has paired a high profile Otemachi acquisition with a fresh ¥2,150 payout, so the real choice now is paying up at today’s price or waiting for a cheaper entry before the next move on value.
Preferred P/E of 19.4x: Is it justified for Japan Prime Realty Investment?
On recent numbers, Japan Prime Realty Investment trades on a P/E of 19.4x, which looks rich next to both its Asian Office REITs peer group and the broader market, even though the last close sits at ¥91,200.
The P/E ratio compares the current unit price to earnings per unit. For a REIT like Japan Prime Realty Investment, it reflects how much investors are willing to pay for each yen of current profit, which is closely watched given the focus on income and relatively steady rental cash flows.
Here, the trust carries a P/E of 19.4x against an Asian Office REITs industry average of 14.5x and a peer average of 18.7x, so the valuation is clearly higher than sector norms. At the same time, internal fair value work points to a "fair" P/E of 19.8x, which is very close to where the units trade and suggests the market may already be anchoring to that level, even as returns over the past year have lagged the wider JP market.
Explore the SWS fair ratio for Japan Prime Realty Investment.
Result: Price-to-earnings of 19.4x (OVERVALUED)
Still, the higher P/E on Japan Prime Realty Investment can come under pressure if rental income growth slows or if broader office demand in Tokyo weakens.
Find out about the key risks to this Japan Prime Realty Investment narrative.
Another view on Japan Prime Realty Investment’s value
That rich looking 19.4x P/E is only one lens. The SWS DCF model, which estimates value based on future cash flows, points to fair worth of around ¥26,282 per unit. On that framework, Japan Prime Realty Investment screens as heavily overvalued. So which signal should drive your next move?
Look into how the SWS DCF model arrives at its fair value.
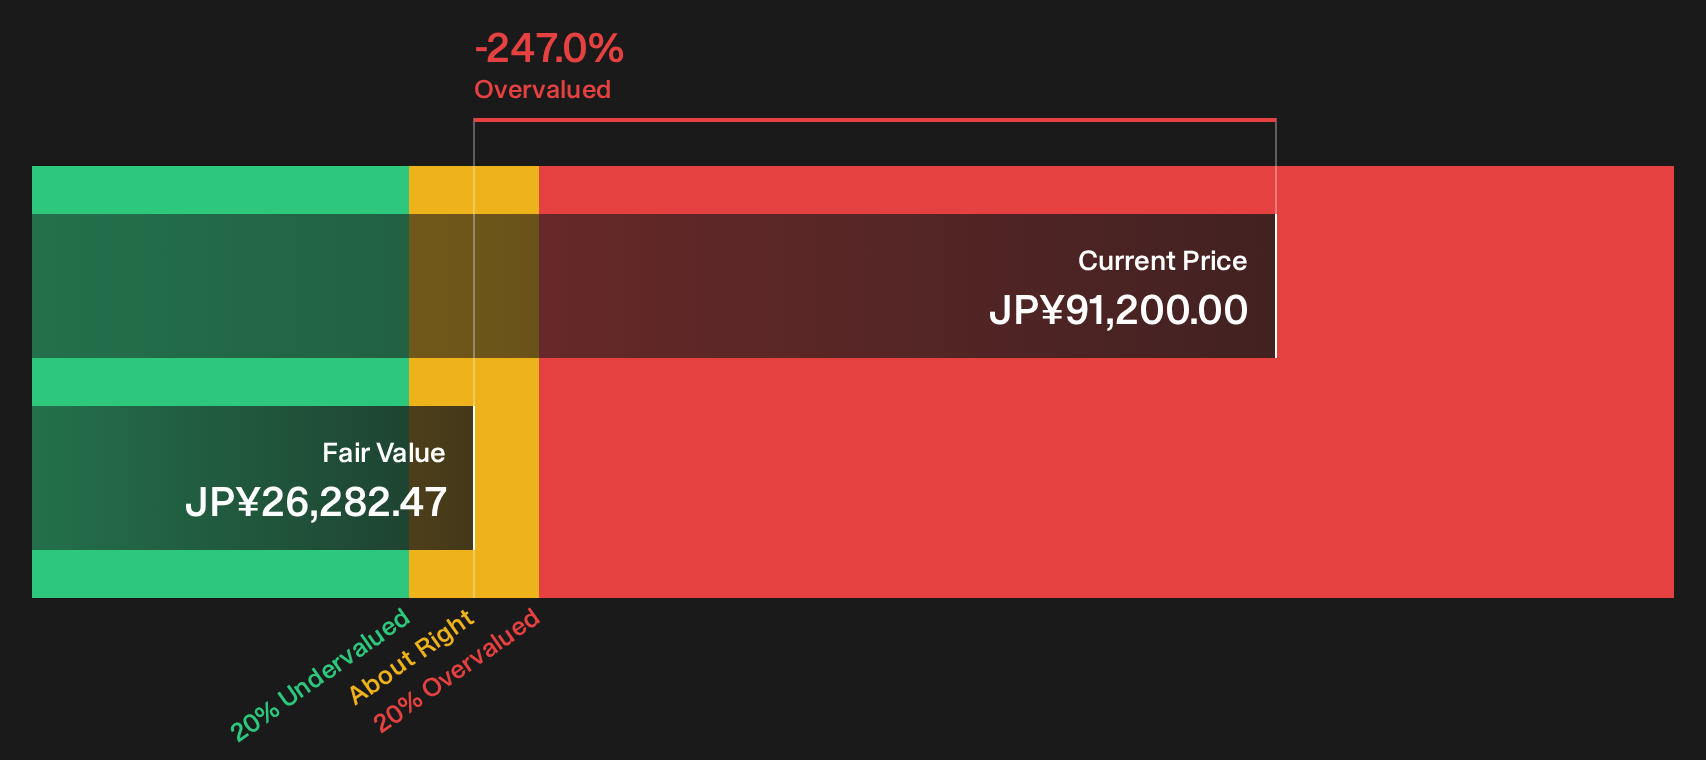
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Japan Prime Realty Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of signals in Japan Prime Realty Investment point in different directions, so move quickly, review the data yourself, and weigh both sides of the story with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Japan Prime Realty Investment?
If you stop your research with Japan Prime Realty Investment, you risk missing other opportunities that line up better with your goals, risk limits, and dividend needs.
- Hunt for potential mispriced opportunities by scanning our curated 15 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Prioritise resilience by working through the list of solid balance sheet and fundamentals (23 results) so your watchlist tilts toward companies with sturdier financial foundations.
- Get ahead of the crowd by reviewing the 72 high quality undiscovered gems before these quieter stories attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com