
What Tyler Technologies Stock's Fairfax AI Rollout Means For Shareholders
- Tyler Technologies reported that Fairfax County, Virginia launched the Ask Fairfax generative digital assistant in August 2026, replacing a legacy chatbot and answering more than 40,000 resident questions using information drawn only from the county’s official website.
- The Fairfax rollout highlights growing real world demand for Tyler Technologies’ Resident AI Assistant, which can deepen SaaS relationships as governments modernize digital services and seek analytics on citizen queries without storing individual conversations.
- This article examines how Tyler Technologies' investment narrative is influenced by Resident AI Assistant adoption in Fairfax County's public services.
Scan how Tyler Technologies is leaning into applied AI for government, then size up other public sector and infrastructure plays on our curated list of 55 AI infrastructure stocks.
Tyler Technologies Investment Narrative Recap
To own Tyler Technologies, you need to believe that state and local governments will keep upgrading to cloud, payments, and AI tools, and that Tyler can turn that adoption into higher recurring software revenue and better operating margins. The Ask Fairfax launch is helpful evidence that Resident AI Assistant is being used in real workloads, but by itself it does not change the short term picture.
The key near term catalyst is execution around the upcoming Q3 2026 earnings release and whether management shows clean SaaS growth after earlier timing related softness. The biggest risk is that subscription growth and margin expansion again fall short of expectations, which could reinforce existing market skepticism about the long term earnings trajectory.
The Q3 2026 print on October 28 is the announcement that now matters most in light of this Fairfax news. Analysts expect earnings per share of US$2.70, with forecasts pointing to higher revenue and around 16% year over year EPS growth. That sets a clear hurdle for how well Tyler is converting its cloud and AI investments into profit.
If reported numbers or guidance show that digital modernization contracts and tools like Resident AI Assistant are supporting steadier SaaS revenue and progress on margins, that would speak directly to the core thesis. A weaker update, especially another quarter of softer subscription growth or limited margin improvement, would keep the focus squarely on execution risk.
What The Tyler Technologies Forecasts Assume
Tyler Technologies' current analyst playbook rests on some specific numbers that you can pressure test against your own expectations. Forecasts point to revenue climbing to US$3.2b and earnings reaching US$533.0m by 2029, based on annual top line growth of 9.6%. That compares with earnings today of US$324.6m, which means analysts are effectively baking in an earnings increase of about US$208m over the forecast window to support their 2029 consensus.
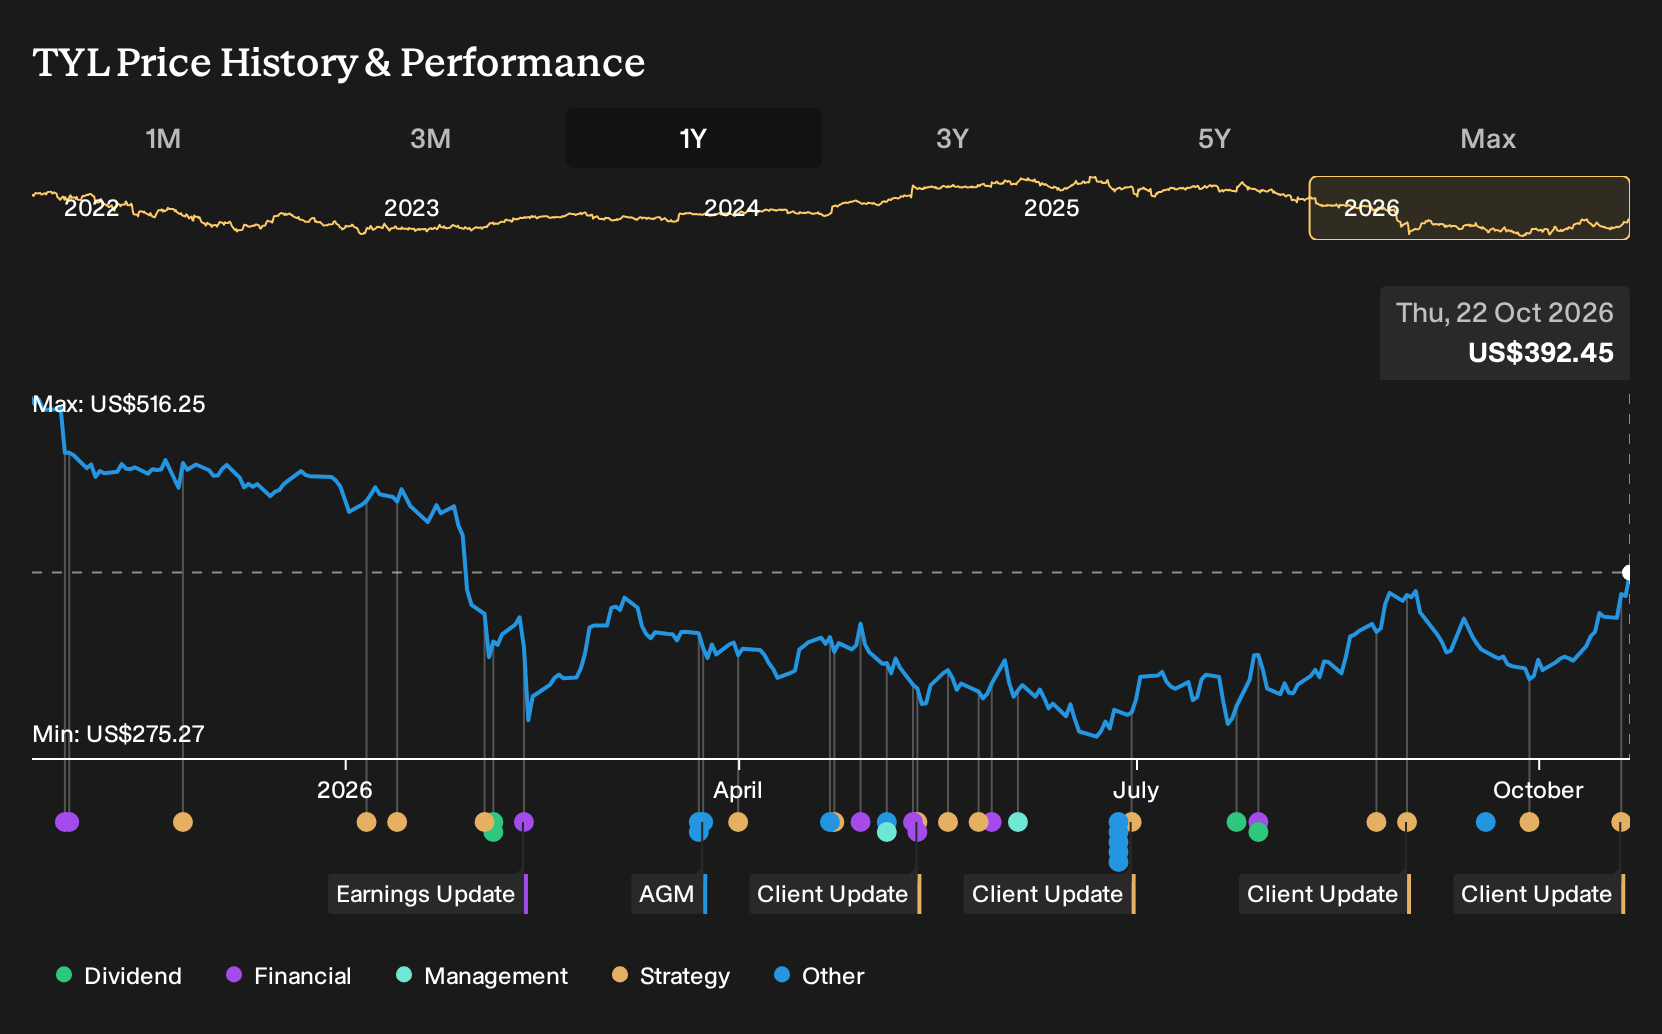
Uncover how Tyler Technologies' fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on slower monetization from tools like Resident AI Assistant. The most pessimistic Tyler Technologies analysts were only penciling in about US$3.1b of revenue and US$513.7m of earnings by 2029 before this Fairfax news. That is a cooler story than consensus, so use it to stress test your own assumptions as opinions may shift.
Explore 6 other Tyler Technologies fair value estimates, including one that suggests as much as 63% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Tyler Technologies research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Tyler Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tyler Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Tyler Technologies?
Once you have a view on Tyler Technologies, it often helps to line it up against other opportunities and see where the risk and return trade off feels most comfortable for you. The Simply Wall St Screener can surface different types of stocks that match the kind of profile you want in your portfolio.
- If income and resilience matter most to you, focus on companies with stronger yield and payout support using our curated set of 6 dividend fortresses.
- If you want balance sheet strength and financial durability, narrow your search to businesses with more robust finances via the list of solid balance sheet and fundamentals (26 results).
- If you prefer to hunt for overlooked opportunities, cast a wider net across under followed quality stocks using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com