
Gecina (ENXTPA:GFC) Wins New La Défense Leases On A Modest Undervalued View
Why Gecina’s New La Défense Leases Matter For Investors
Gecina (ENXTPA:GFC) just locked in two long-term office leases in Paris La Défense, securing full occupancy for Building B and Adamas with firm terms above 11 years.
These agreements, covering 29,000 sq.m with tenants in nuclear energy and security technology, extend visibility on income from 2028 and highlight ongoing demand for prime, energy efficient offices in this submarket.
Gecina’s latest leasing win comes at a time when momentum in the shares has been weak, with the 90 day share price return down 13.72% and the year to date share price return down 20.39%, while the 1 year total shareholder return is down 17.02%. This points to pressure that these firm, long dated contracts may start to reframe in investors’ eyes as they reassess income visibility and perceived risk.
Scan beyond Gecina to see how other real estate players with full pipelines and resilient tenants line up in our curated 222 resilient stocks with low risk scores for ideas with lower business risk profiles.
Gecina now trades at a clear discount to both analyst targets and some intrinsic estimates, while the share price has been under pressure. Is the gap a margin of safety, or a warning sign that the market is right to price in caution?
Most Popular Narrative: 9% Undervalued
On the most followed narrative, Gecina’s fair value sits at €70.00, a touch above the last close at €63.85. This frames today’s discount as modest rather than extreme.
The assumed bearish price target for Gecina is €70.0, which represents up to two standard deviations below the consensus price target of €91.2. This valuation is based on what can be assumed as the expectations of Gecina's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
See why 1 investors see Gecina as 9% undervalued.
Result: Fair Value of €70.00 (UNDERVALUED)
Still, if Gecina keeps securing long leases on prime Paris assets and maintains its A and A3 credit ratings, that cautionary fair value story could shift.
Find out about the key risks to this Gecina narrative.
Another View: What Gecina’s P/E Ratio Is Telling You
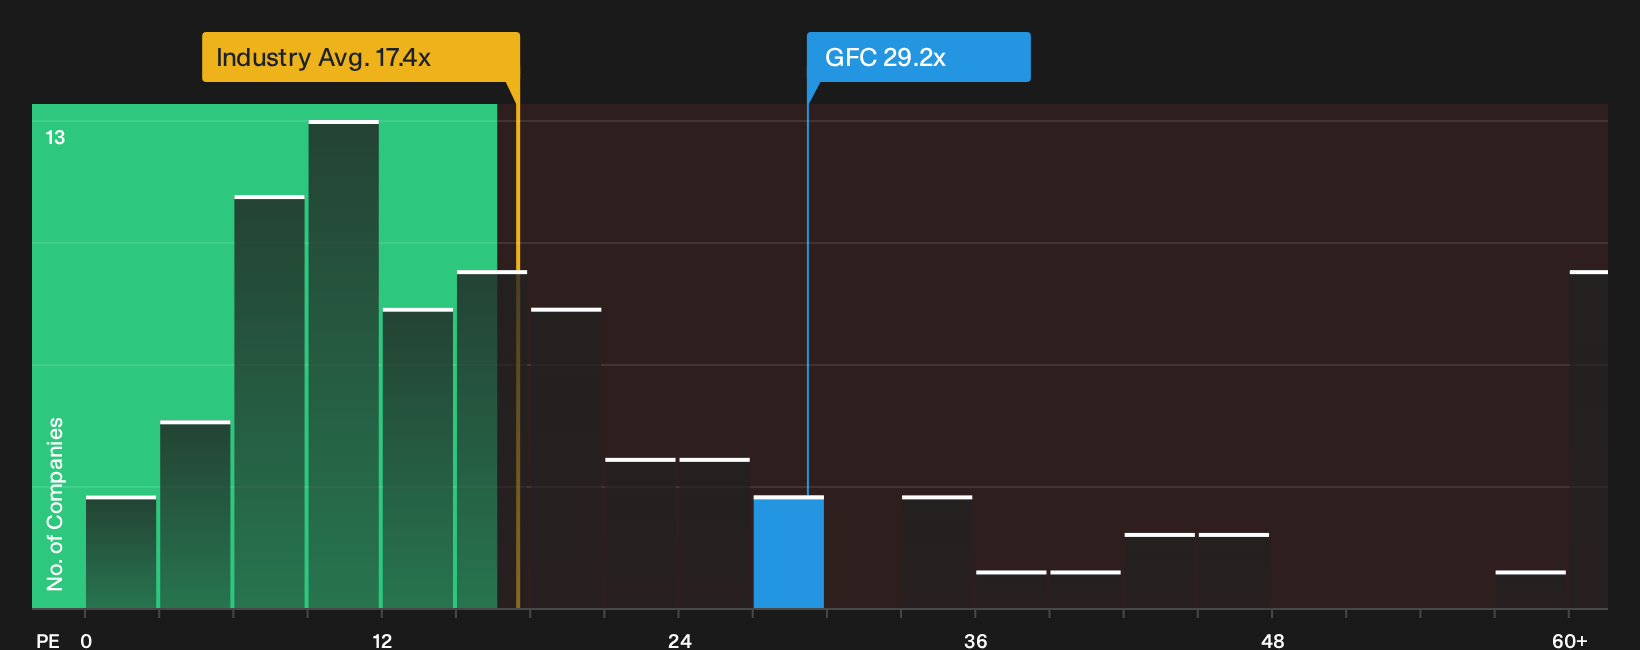
Strip the story back to simple price tags and Gecina looks less generous. The stock trades on a P/E of 29.2x, which is higher than both the Global Office REITs average of 17.6x and its own fair ratio of 16.7x. That gap points to valuation risk if sentiment or earnings assumptions change.
To see how that premium lines up with the rest of the market, and whether the numbers justify paying up for Gecina at this level, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Gecina’s valuation and leasing momentum can feel messy, so move quickly to the underlying data and decide what really matters to you. To see the balance between potential upside and the issues investors are worried about, go straight to the 4 key rewards and 3 important warning signs
Looking For More Gecina-Like Investment Ideas?
If Gecina has you thinking harder about quality, do not stop with a single ticker. Use focused screeners to surface other opportunities that match how you like to invest.
- Target potential mispricing by scanning for strong fundamentals and attractive valuations through the 195 high quality undervalued stocks.
- Lock in income focused ideas by reviewing companies screened as potential 224 dividend fortresses.
- Prioritise resilience by filtering for companies with sturdy finances in the list of solid balance sheet and fundamentals (205 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com