
Does Strong September Sales Change The Bull Case For Don Quijote Operator Pan Pacific International Holdings (TSE:7532)?
- Pan Pacific International Holdings reported September 2026 domestic retail sales at 103.1% year over year for comparable stores and 105.2% for all stores, with both Discount Store and UNY segments showing sales above 100% on this basis.
- The broad-based sales strength across both Discount Store and UNY operations points to resilient consumer demand and solid in-store execution for Pan Pacific International Holdings rather than a single product or channel swing.
- Next, the focus shifts to how this broad-based September sales outturn could shape Pan Pacific International Holdings’ investment narrative.
What Is Pan Pacific International Holdings' Investment Narrative?
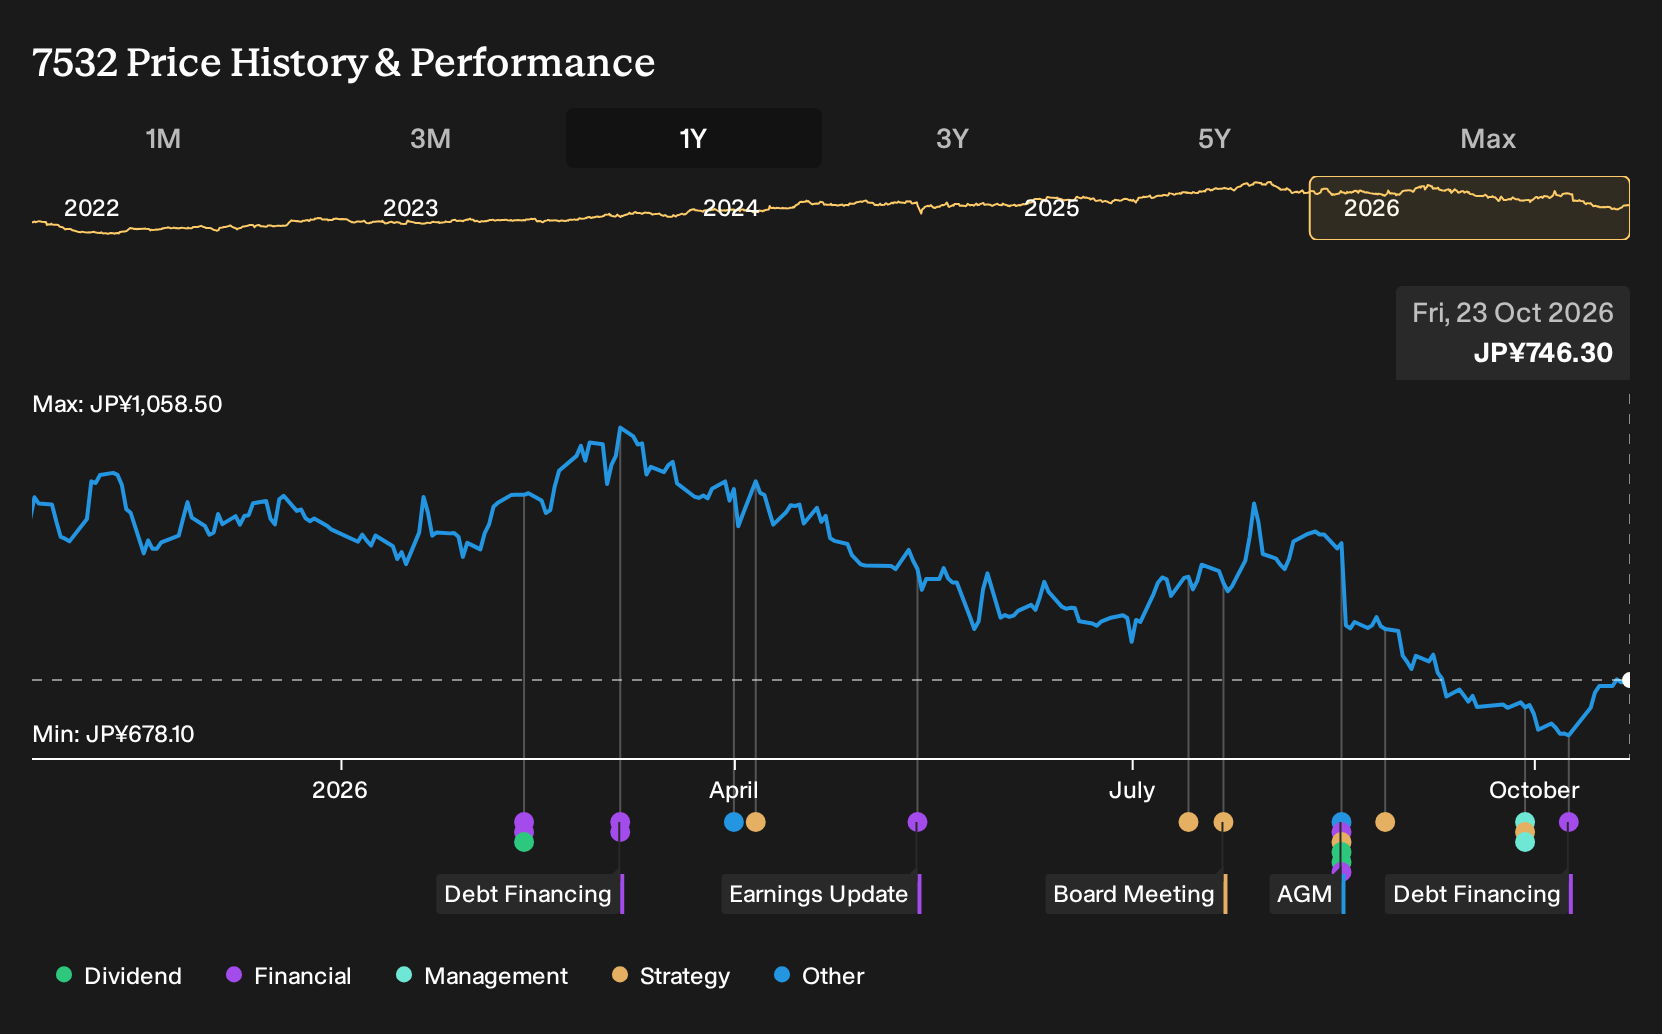
To own Pan Pacific International Holdings, you need to be comfortable with a fairly capital intensive retail model that leans on steady footfall, decent pricing power and ongoing store refresh. The September sales print, with comparable domestic stores at 103.1% and all domestic outlets at 105.2% year over year, supports a view that demand across both Discount Store and UNY formats remains resilient in the near term. In the short term, that points more to consistent execution than a one off surge, especially against a share price that has fallen about 22% over the past year despite multi year earnings growth and higher net profit margins.
The new ¥25b unsecured bond, carrying a 2.455% coupon and maturing in 2029, shows management still comfortable using debt financing for bond redemption rather than shrinking the balance sheet. That keeps funding straightforward but does not reduce reliance on higher risk borrowing sources. With the stock trading on a P/E of 20.3x, above the Japan multiline retail average yet below peer P/E, the near term story hinges on whether mid single digit revenue growth and forecast 7.5% earnings expansion remain enough to justify that multiple if comparable sales ever soften.
Even so, there is a catch once you look closely at how this funding mix intersects with...
There's only one way to know the right time to buy, sell or hold Pan Pacific International Holdings. Head to Simply Wall St's company report for the latest analysis of Pan Pacific International Holdings's Fair Value.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pan Pacific International Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Pan Pacific International Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pan Pacific International Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Pan Pacific International Holdings?
If the Pan Pacific International Holdings update has you thinking more broadly about where consumer strength and balance sheet quality might intersect, the next step is to widen your watchlist. The Simply Wall St Screener can help you filter for traits that match your own tolerance for risk, income needs, and quality thresholds so you are not relying on a single story.
- Prefer resilient businesses with measured risk? Filter for companies that show stronger fundamentals and steadier profiles through the 22 resilient stocks with low risk scores.
- Want higher income potential? Target stocks that currently offer more substantial payout rates by running through the 29 dividend fortresses.
- Looking for quality that is still under the radar? Search for financially sound opportunities that have yet to gain wider attention using the 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com