
Martin Marietta Materials (MLM) Could Be 18% Undervalued As Earnings Near
Martin Marietta Materials (MLM) has scheduled its third quarter earnings call for November 4, 2026, with results for the September quarter set to be released before the market opens that morning.
At a share price of $517.67, Martin Marietta Materials has seen short term momentum pick up, with a 1 day share price return of 1.70% and a 7 day move of 5.38%. This comes even as the 90 day share price return declined 7.49% and the year to date share price return fell 18.41%, while the 5 year total shareholder return of 35.61% points to a much stronger long haul record than the recent pullback suggests.
Scan for other construction and infrastructure plays that show similar earnings catalysts and shifting sentiment with our hand picked list of solid balance sheet and fundamentals (26 results).
After a sharp bounce in the past week but a weaker run over the year, Martin Marietta Materials now sits at a crossroads. The key question is whether the current valuation still offers enough potential upside to justify the risks from here.
Most Popular Narrative: 18% Undervalued
In the most followed narrative, Martin Marietta Materials appears undervalued, with a fair value estimate of $633.92 compared with the latest close at $517.67. That gap is based on a detailed set of assumptions about acquisitions, infrastructure demand and long-term mix shift in the business.
The portfolio shift away from cement and ready mix toward higher margin aggregates and specialties, including the completed Quikrete asset exchange, the New Frontier Materials bolt on and the combination with Lhoist North America that adds over 2 billion tons of limestone reserves, is expected to increase the mix of upstream materials with structurally higher margins and free cash flow conversion, which can support earnings quality and cash generation.
See why 11 investors see Martin Marietta Materials as 18% undervalued.
Result: Fair Value of $633.92 (UNDERVALUED)
Still, elevated diesel and energy costs, together with any stumble on integrating Quikrete, New Frontier and Lhoist North America, could quickly challenge that 18% undervalued narrative.
Find out about the key risks to this Martin Marietta Materials narrative.
Another View: What Multiples Say About Martin Marietta Materials
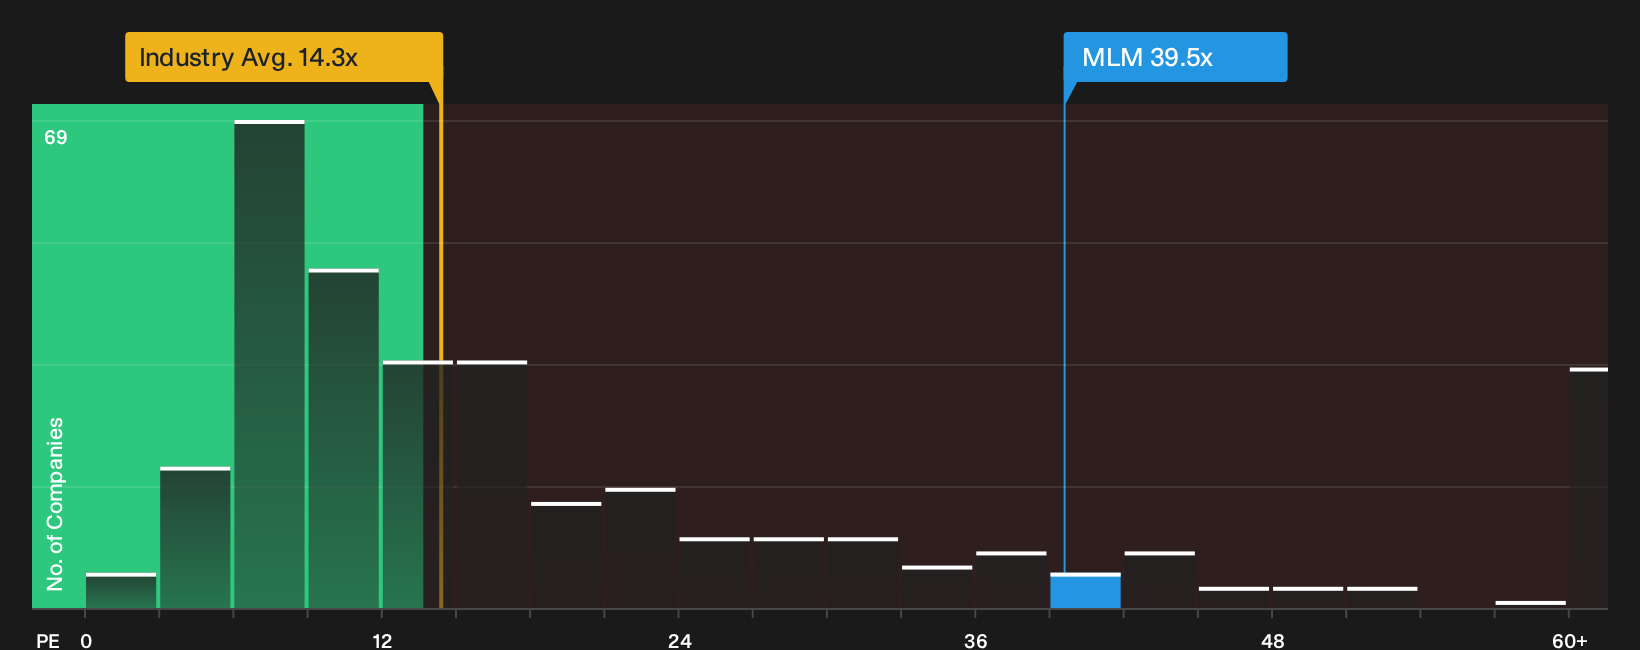
While the most popular Martin Marietta Materials narrative points to an 18% discount to fair value, the market price tells a different story when using earnings multiples. The current P/E of 39.5x sits well above the peer average of 18.5x and the Basic Materials industry at 14.3x.
The fair ratio for Martin Marietta Materials is 22.9x, far below where the shares trade today. That gap signals meaningful valuation risk if sentiment cools or earnings miss expectations, so the question is which lens you trust more when weighing the stock from here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split between risks and rewards around Martin Marietta Materials feels finely balanced, treat that as your cue to inspect the evidence and then move quickly to your own judgment with 2 key rewards and 2 important warning signs.
Looking for more Martin Marietta Materials level ideas?
Do not stop with Martin Marietta Materials alone. Broaden your watchlist now so you catch strong setups before they move out of reach.
- Target resilient performers that aim to protect your capital first by scanning a 30 resilient stocks with low risk scores tailored to lower risk profiles.
- Hunt for compelling value opportunities by running a 29 high quality undervalued stocks that highlights companies with solid fundamentals and prices that may lag their underlying strength.
- Focus on staying power and quality by zeroing in on a 20 high quality undiscovered gems that filters for strong finances before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com