
How Positive Cancer Trial Data At Summit Therapeutics (SMMT) Has Changed Its Investment Story
- Summit Therapeutics reported positive Phase III overall survival data for ivonescimab in advanced biliary tract cancer and agreed with ECOG-ACRIN to run a new U.S. registration-enabling Phase II/III trial against current immunotherapy standards.
- The combination of late-stage success signals in biliary tract cancer and added U.S. trial activity increases Summit Therapeutics' execution demands, trial costs, and future commercialization planning needs around ivonescimab.
- We will look at how Summit Therapeutics' investment narrative is shaped by Phase III biliary data and the new ECOG trial.
Summit Therapeutics Investment Narrative Recap
To own Summit Therapeutics, you need to believe ivonescimab can convert an extensive late stage program into regulatory approvals and, over time, meaningful use in several solid tumors. The key near term focus still sits on regulatory outcomes and execution across at least 15 Phase III trials. The recent biliary tract cancer data and ECOG partnership sharpen that focus but do not change the basic dependency on ivonescimab.
The biggest near term catalyst remains progress on registrational filings and any clarity from regulators on overall survival expectations. The largest risk is unchanged. Summit is loss making with no current product revenue and heavy R&D plus commercialization spending, so any delay, weaker outcome or safety concern in a major ivonescimab program would amplify cash burn and potential dilution.
The ECOG-ACRIN EA2251 collaboration for biliary tract cancer is the most relevant fresh data point. It anchors ivonescimab directly against U.S. checkpoint standards like pembrolizumab and durvalumab in first line disease, with overall survival as the primary endpoint. For you, that creates a very clear readout on how the drug performs where immunotherapy is already embedded in care.
This study also raises the operational bar for Summit Therapeutics. Running a U.S. registration enabling Phase II/III on top of HARMONi GI1 means more trial complexity, higher costs and a greater need to coordinate with partners such as Akeso and cooperative groups. Success would support the broader ivonescimab thesis, while any underperformance here would feed directly into the central efficacy and market size risk.
Summit Therapeutics' consensus story assumes revenue reaches US$1.2b and earnings come to US$197.7m by 2029, which implies a very large step up from zero revenue today and an earnings swing of about US$1.1b from the current loss of US$856.1m.
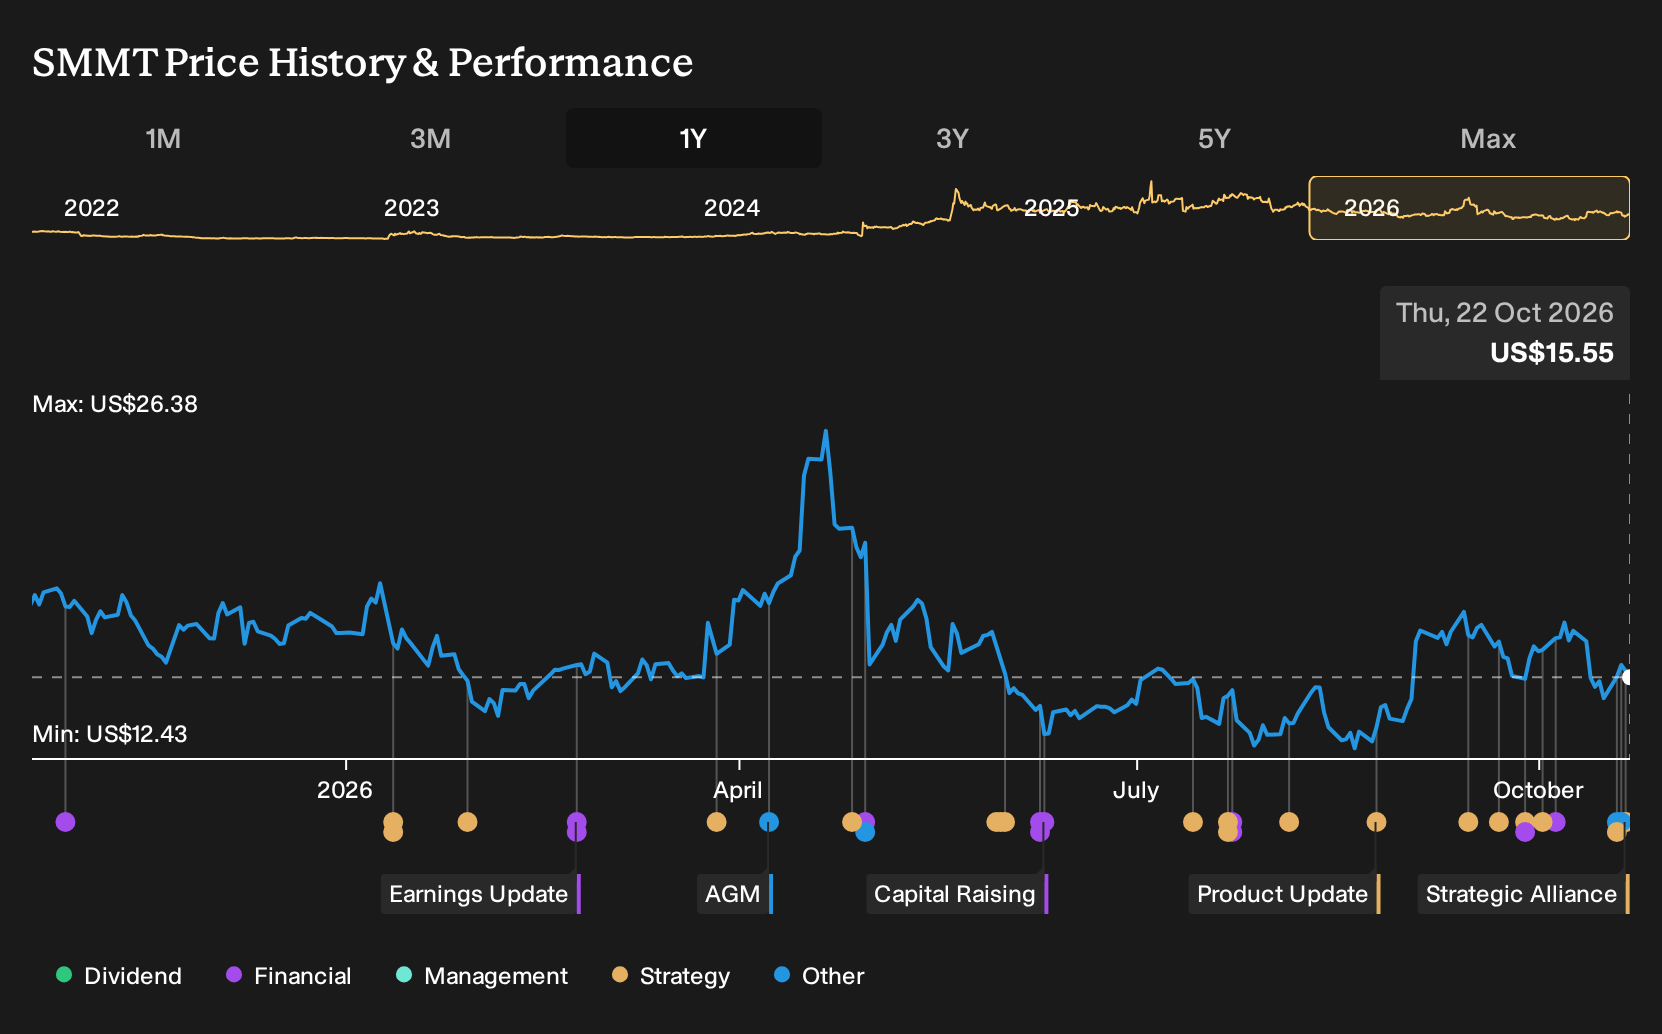
Uncover why Summit Therapeutics' fair value indicates a 93% potential upside to its current price before enthusiasm around the discount starts to fade.
Exploring Other Perspectives
Some of the lowest analysts focus on dilution risk rather than trial success. They point to Summit Therapeutics proposing to double authorized shares and had been modeling only about US$16.8 million of revenue and US$2.9 million of earnings by 2029. That is far below consensus and shows how sharply views could shift as the new ECOG biliary trial gets factored in.
Explore 4 other Summit Therapeutics fair value estimates, including one that suggests there could be as much as 23% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Summit Therapeutics research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Summit Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Summit Therapeutics' overall financial health at a glance.
Looking for more investment ideas beyond Summit Therapeutics?
If you want to put Summit Therapeutics in context, it helps to line it up against other opportunities that fit clear financial or risk filters. The Simply Wall St Screener lets you move from one story to a full watchlist built around the traits you care about most.
- For investors who care most about capital preservation, start with resilient businesses screened using 30 resilient stocks with low risk scores that aim to keep downside risk in check.
- If balance sheet strength is non negotiable for you, line up companies with a list of solid balance sheet and fundamentals (26 results) and compare how their financial footing stacks up against Summit Therapeutics.
- When you want fundamentals and pricing to work in your favor, look across a 29 high quality undervalued stocks and see which stocks currently match the kind of risk reward trade off you prefer.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com