
Reliability Rating Might Change The Case For Investing In FuelCell Energy Stock (FCEL)
- FuelCell Energy recently appointed John Dansby as Senior Vice President, Scale Up Manufacturing, and reported a 34.4% annual revenue increase over two years, along with improving profitability and free cash flow metrics.
- The company’s fuel cell block system earned a 99.873% PJM reliability rating, which supports its push into capacity markets and on-site power for data center demand.
- We will now explore how FuelCell Energy’s strong PJM reliability accreditation could reshape its broader investment narrative for long-term investors.
Scan the wider clean power space by lining up FuelCell Energy beside hand-picked peers in the 42 power grid technology and infrastructure stocks that are also targeting reliable, data center ready electricity.
FuelCell Energy Investment Narrative Recap
To own FuelCell Energy, you need to believe the business can turn high reliability and technology into scale, while working down sizeable losses and cash burn. The near term story leans heavily on cost cuts and tighter execution. The new manufacturing hire matters here, but the key catalyst still sits in winning and delivering projects tied to dependable power.
The biggest risk has not changed. FuelCell Energy remains unprofitable with a US$29.1 million quarterly loss and depends on new partnerships, policy support and successful commercialization of newer platforms. If cost reductions and scale up efforts underperform, the path toward financial self sufficiency becomes harder and dilution or higher risk funding stays on the table.
The appointment of John Dansby as Senior Vice President, Scale Up Manufacturing lines up most directly with those cost and capacity catalysts. He is tasked with expanding Torrington to 500 MW of annual capability and designing systems that support growth beyond that level. For an investor, that role sits right at the intersection of manufacturing efficiency, delivery risk and margin progress.
This hiring decision lands while FuelCell Energy is pushing for a 15% cut in operating expenses, ramping partnerships such as Diversified Energy for data centers and trying to commercialize solid oxide and carbon capture offerings. Execution in Dansby’s remit could support throughput, quality and downtime performance. Weak execution would amplify existing risks around project delivery, profitability and funding needs.
FuelCell Energy Forecasts and Valuation Anchors
Analysts building long range models for FuelCell Energy are working off some punchy numbers. The consensus view ties the story to an assumed 64.9% yearly increase in revenue over the next three years, with revenue projected to reach US$690.6 million by 2029. Those same models point to a shift from current earnings of a US$178.3 million loss to forecast earnings of US$77.6 million in 2029, which implies an earnings swing of roughly US$255.9 million.
FuelCell Energy's narrative projects US$690.6 million revenue and US$77.6 million earnings by 2029. This requires 64.9% yearly revenue growth and an earnings increase of about US$255.9 million from current earnings of a US$178.3 million loss.
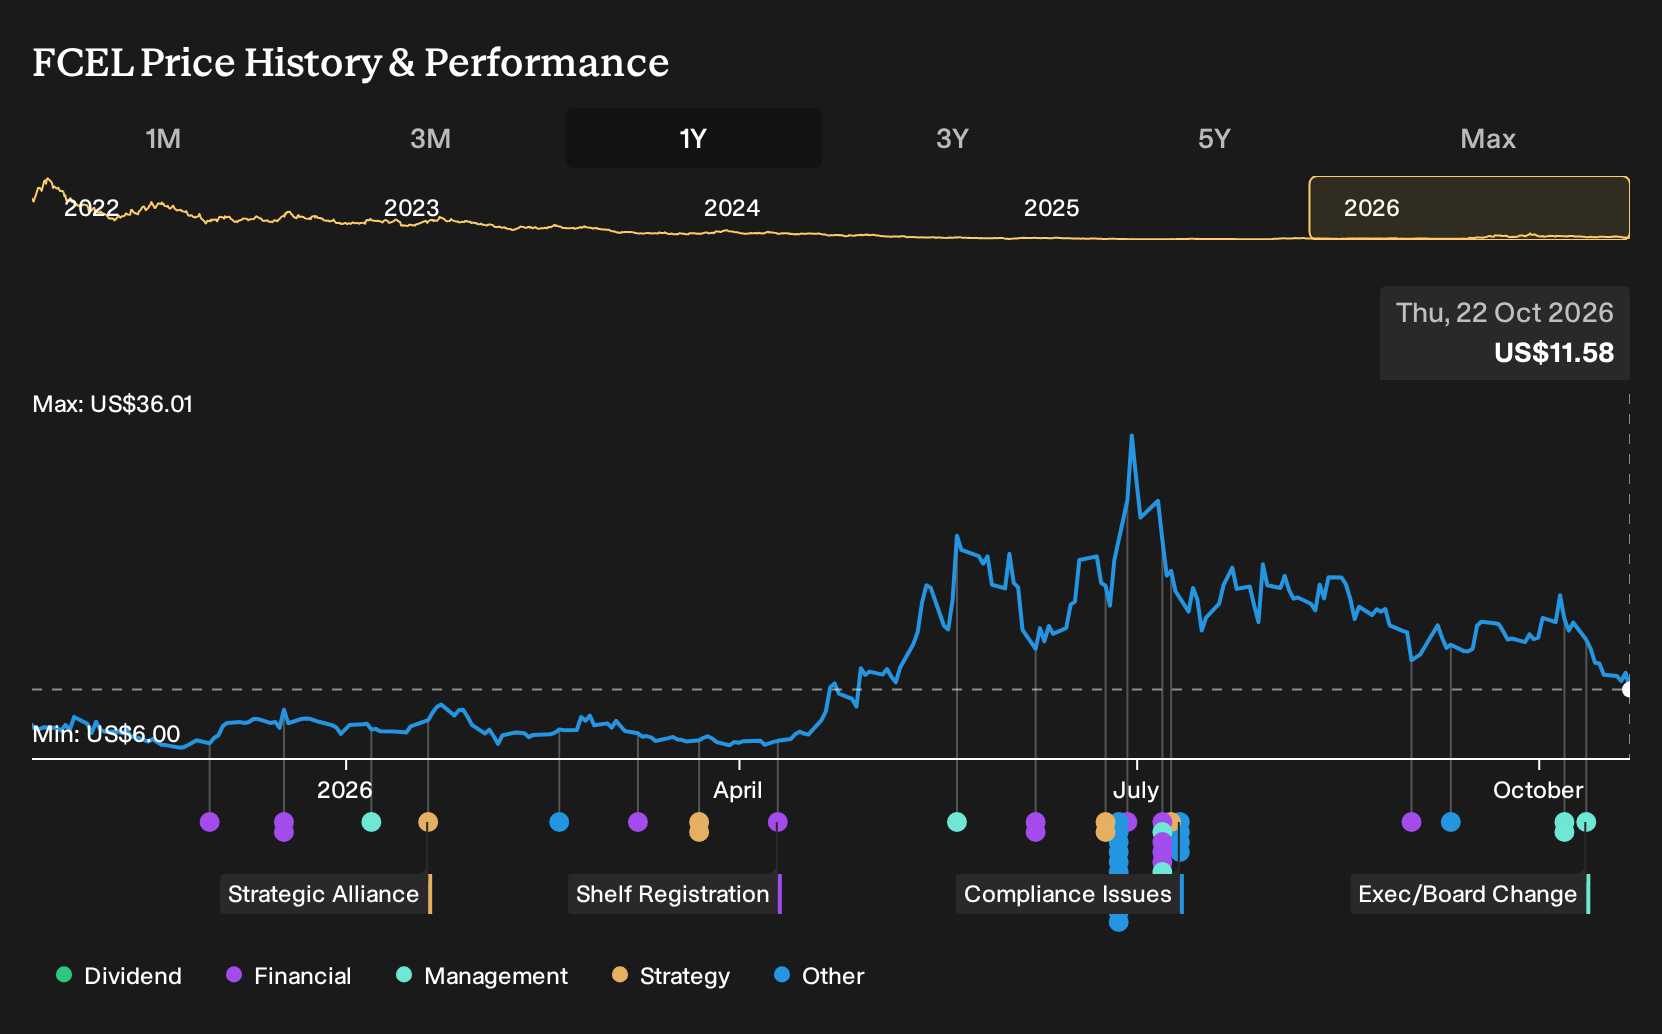
Uncover why FuelCell Energy's fair value indicates a 77% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Bearish analysts focus on a different risk. They worry FuelCell Energy ramps Torrington capacity faster than profitable demand appears, so they model revenue at about US$456.9 million and earnings of US$51.4 million by 2029. That is far below consensus. Given Dansby’s hire and the PJM result, some of these views may evolve.
Explore 4 other FuelCell Energy fair value estimates, including one that suggests as much as 12% downside from the current price.
Decide For Yourself
Don’t just follow the ticker. Dig into the data and build a conviction that’s truly your own.
- A great starting point for your FuelCell Energy research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for FuelCell Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FuelCell Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond FuelCell Energy?
Once you have a view on FuelCell Energy, it can help to compare it with other opportunities that fit different goals, from value hunting to income or balance sheet strength. Use the Simply Wall St Screener to build that wider watchlist and keep your portfolio options open.
- For investors hunting for shares that look cheap relative to their quality, compare FuelCell Energy with a wider value hunting list using the 29 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you than rapid growth, weigh FuelCell Energy against companies in our 30 resilient stocks with low risk scores that score well on resilience.
- Income focused readers who care about yield alongside fundamentals can cross check FuelCell Energy with a group of high payout candidates curated in the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com