
What Excelerate Energy Doubters Got Wrong
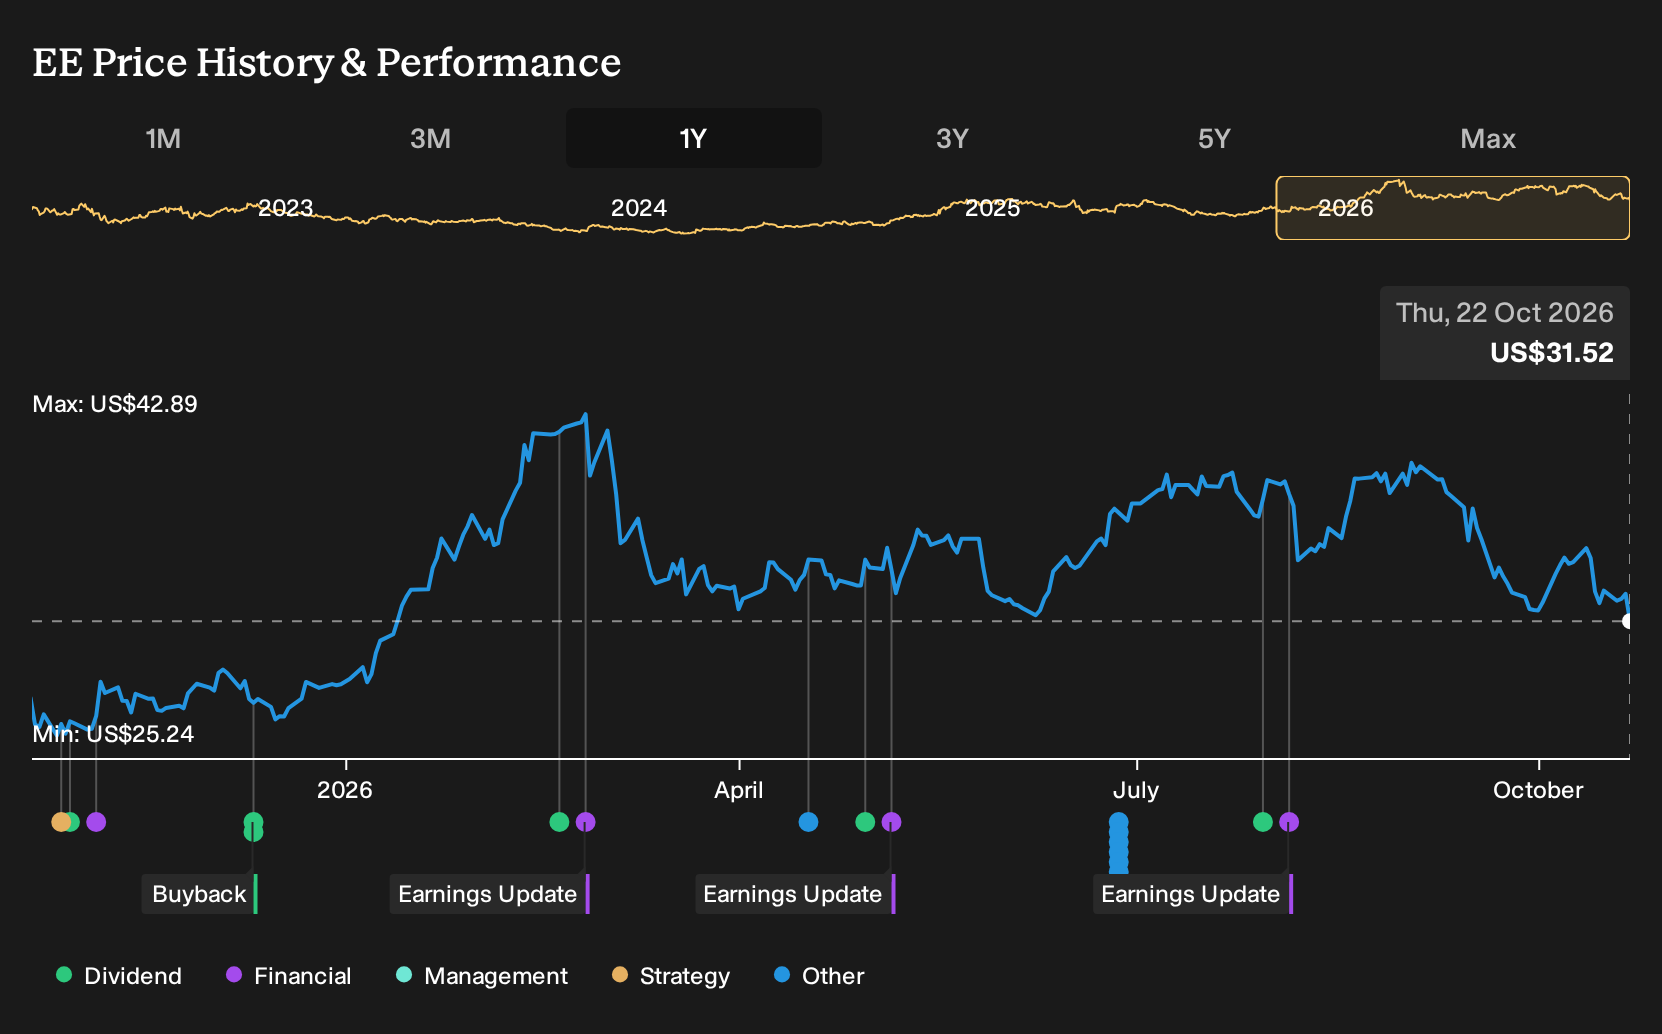
Excelerate Energy’s latest move to convert the Methane Patricia Camila into a new FSRU, with delivery targeted for 2028, sharpened the story around its expanding LNG fleet. For Excelerate Energy shareholders, the return over the past year was 23.9%, including dividends. If you had been weighing a purchase back on 22 October 2025, what did you need to believe about Caribbean projects and capital hungry LNG assets to feel comfortable stepping in?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Excelerate Energy has already moved. See which of 29 high quality undervalued stocks still trade below our estimates.
The Argument Excelerate Energy Investors Were Really Having
The shares cost US$25.84 at the start of the period, and anyone looking at Excelerate Energy then had to choose which story felt more realistic.
On the optimistic side, the bullish Caribbean LNG Expansion narrative put Fair Value at US$33.55, 30% above the start price. That view leaned on more than 90% of adjusted EBITDA sitting in long term take or pay contracts, plus further LNG demand from fuel switching and new FSRUs.
The more cautious Global LNG Headwinds narrative set Fair Value at US$23, 11% below the start price. This camp focused on decarbonization policy, faster renewable adoption, and the risk that heavy Caribbean capex of US$200 million to US$400 million by 2030 could leave LNG assets underused.
What The Results Changed For The Excelerate Energy Debate
Excelerate Energy’s Q2 2026 numbers gave the bullish case fresh support. Revenue was US$329.3 million and net income was US$12.1 million, compared with US$204.6 million and US$4.7 million a year earlier, and net margin moved from 2.3% to 3.7%. That progress sat alongside ongoing Iraq delays and subscale economics, so the evidence cut both ways rather than closing the argument.
The key assumption investors needed to keep testing was whether LNG infrastructure could turn heavy capex into steadily improving profitability. For a similar stock, you would watch net income and net margin alongside each project update, and check whether new vessels and contracts appear in those figures within a year or two.
What Excelerate Energy's Price Assumes Today
Excelerate Energy now trades at US$31.52, with this bullish Narrative arguing that Fair Value sits above that level. The focus has shifted to control of scarce FSRU capacity, integrated LNG to power projects, and the Jamaica hub as the key planks of the thesis.
For a buyer today, the question is whether Excelerate Energy can keep executing large integrated projects while holding net leverage near current levels so contracted LNG infrastructure earnings keep compounding.
"The main factor that has to go right is continued execution on integrated projects such as Iraq and Methane Patricia Camila, along with keeping net leverage near current levels so that both growth capex and rising dividends can be funded. The thesis on Excelerate Energy has been reviewed and reaffirmed, with the updated view placing more weight on contracted FSRU capacity, a clearer project pipeline, and the current balance sheet position as key drivers for the narrative."
One Narrative disagrees with today's price. → See where this Narrative says Excelerate Energy should trade
One Step Beyond Excelerate Energy
Excelerate Energy asks you to think about who funds the terminals. A nearby question lurks in the background. Who collects a slice of production without running the projects at all?
In oil and gas, one business model focuses on owning the ground, not the rigs. It holds mineral and royalty interests while others drill and complete wells.
Operators decide where to explore, how fast to develop and what to spend. The royalty holder waits for volumes to show up, then receives its contracted share.
Excelerate Energy shows what heavy infrastructure can earn when it is well contracted. This other model shows what resource rights can earn when somebody else supplies almost all the capital.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 23% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com