
8% Undervalued? ChemoMetec (CPSE:CHEMM) After Its Recent Rebound
ChemoMetec (CPSE:CHEMM) drew fresh attention after its recent share move, with the stock up about 13% over the past month and roughly 44% in the past 3 months.
Set against that rebound, ChemoMetec’s share price return is still down about 13% year to date, while the 1-year total shareholder return has fallen roughly 16%. Even so, the 3-year total shareholder return is up around 128%, which hints at earlier strong momentum that has cooled recently.
Track ChemoMetec’s rebound and compare it with other hand-picked quality opportunities by screening for 195 high quality undervalued stocks that pair healthier balance sheets with solid cash generation.
ChemoMetec has a track record of selling specialised cell analysis gear and still posts rising revenue and net income. Yet the share price only recently bounced after a tougher stretch. After that swing, is this now a strong business at a stretched price or a reasonable entry on renewed interest?
Most Popular Narrative: 8% Undervalued
ChemoMetec’s most followed valuation narrative points to a fair value of about DKK638 per share, compared with the last close at DKK585.5. That gap rests on a view that the current price does not fully reflect the company’s growth projects and product pipeline.
Investment of around DKK 120 million in product development for fiscal 2026 to 2027, focused on automation, sample management and XM Octopus fleet management software, can build higher value system and software revenue streams that may support EBITDA margins over time.
See why 1 investors see ChemoMetec as 8% undervalued.
Result: Fair Value of DKK638.33 (UNDERVALUED)
Still, the ChemoMetec story depends heavily on XM automation and NC-200 replacements translating into ongoing consumables usage, while higher R&D and growth spending could pressure free cash flow if returns are delayed.
Find out about the key risks to this ChemoMetec narrative.
Another View: ChemoMetec’s Rich Earnings Multiple
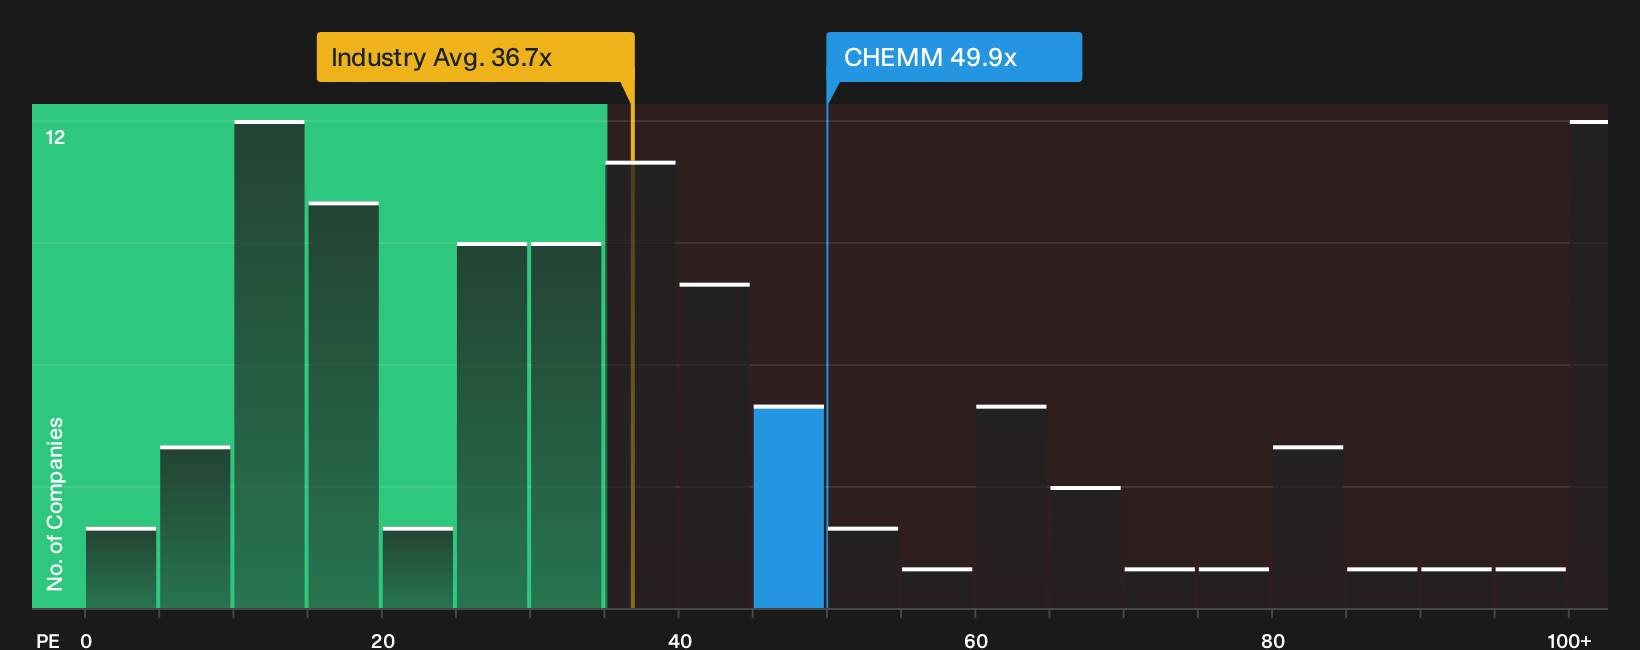
The popular story frames ChemoMetec as about 8% undervalued around DKK585.5 per share. On a simple earnings yardstick, the picture is very different. The stock trades on a P/E of 49.9x, compared with 24.8x for peers, while the fair ratio sits at 20x.
That gap means investors are already paying more than double the peer average and well above the fair ratio the market could move towards, which raises clear valuation risk if expectations cool or sector sentiment fades. The question is whether the quality of ChemoMetec’s growth and returns justifies staying that far ahead of both peers and the fair ratio.
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on ChemoMetec’s valuation story so far. If you want to move fast and form your own view, start by weighing the 2 key rewards and 2 important warning signs
Looking for more ChemoMetec-sized investment ideas?
If you stop with ChemoMetec, you risk missing other opportunities that fit your style, so use the screener to pressure test and broaden your watchlist.
- Target income first and pick from reliable payers by scanning our hand picked group of 226 dividend fortresses that aim to keep distributions front and center.
- Hunt for quality at a discount by filtering for 615 high quality undiscovered gems where strong fundamentals may not yet be fully reflected in current prices.
- Prioritize resilience and protect your downside by focusing on 222 resilient stocks with low risk scores that score well on balance sheet strength and volatility control.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com