
Is Deere (DE) Fully Priced Following Its Farm Cycle Bottom Call?
Deere (DE) is back in focus after management described 2026 as the bottom of the farm equipment cycle, with a measured recovery expected rather than a sharp rebound in 2027.
Deere’s recent comment on the farm cycle comes after a mixed stretch in the share price, with the stock down 8.46% over the past month but still carrying a 37.88% year to date share price return and a 96.44% five year total shareholder return. This suggests that long term holders have been rewarded even as near term momentum cools.
Capture the full farm cycle story around Deere by comparing it with a hand picked 29 high quality undervalued stocks that may be better positioned for the next phase.Deere appears to be a strong franchise with global reach and solid profitability. After a sharp year-to-date move and with a potential farm cycle low in sight, investors may wish to consider whether the current price still offers sufficient value for that level of quality.
Most Popular Narrative: 6.5% Undervalued
Deere is priced at $643.62 against a widely followed fair value estimate of $688.44, which frames the stock as modestly undervalued while still pricing in solid execution on its core themes.
Expansion of Deere’s digital ecosystem, with more than 520 million engaged acres, nearly 1.2 million connected machines and over 450,000 monthly active users in John Deere Operations Center, builds on the prior focus on software and data services and points to a growing base for recurring revenue and potentially higher earnings from digital tools layered on the installed equipment fleet.
See why 123 investors see Deere as 7% undervalued.
Result: Fair Value of $688.44 (UNDERVALUED)
Still, the Deere narrative can be challenged if tariff costs stay elevated or if a deeper, longer farm downturn keeps big ticket equipment demand under pressure.
Find out about the key risks to this Deere narrative.
Another View: Deere On Earnings Multiples
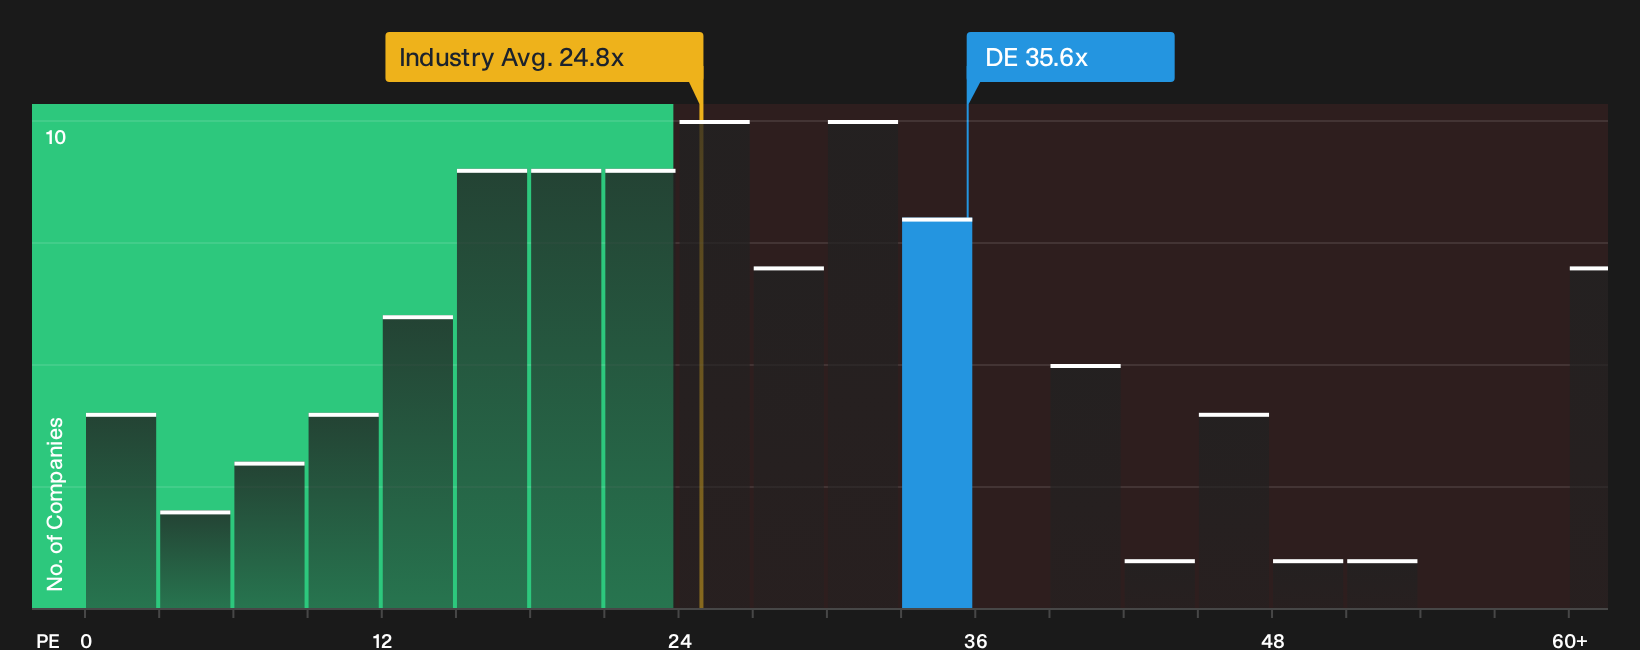
The first lens paints Deere as modestly undervalued, yet the current P/E of 35.6x tells a tougher story. That figure is well above both the US Machinery industry at 24.8x and Deere’s own fair ratio of 37.5x, which the market could drift toward over time.
If sentiment cools or growth expectations reset, the gap between today’s rich P/E and sector norms could matter more than the 15.5% discount to fair value suggests for anyone buying at current levels.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Deere’s outlook can feel messy, so move quickly to test the numbers yourself, weighing both the risks and upside that investors are flagging through 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Deere?
If Deere’s mixed signals leave you wanting a few extra options, it makes sense to widen your search with a structured set of stock ideas.
Use the Simply Wall St Screener to quickly pressure test different themes, then line them up against Deere so you are not relying on just one story.
- Target resilient higher-yield opportunities by scanning a curated set of income ideas through 6 dividend fortresses.
- Surface robust balance sheets by checking the list of solid balance sheet and fundamentals (26 results) before committing fresh capital to any single ticker.
- Hunt for under-the-radar potential by reviewing the 20 high quality undiscovered gems that might not yet be crowded trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com