
Why PNC Financial Services Group (PNC) Is Back In The Spotlight
PNC Financial Services Group (PNC) has just put fresh numbers on the table, with its latest quarterly update showing revenue in line with expectations and a stronger tangible book value outcome than markets anticipated.
Recent trading has been choppy for PNC Financial Services Group, with the share price down about 10% over the past 90 days, even after a 4.9% gain across the last week and a 1.2% move higher in the latest session to US$225.53.
That short term weakness contrasts with a much stronger picture for patient holders, with total shareholder return of 28% over one year and about 120% over three years, suggesting momentum has generally been building as dividends and price gains compound.
Fresh earnings, a stronger tangible book value figure and the recent decision to issue US$1.5b of senior notes while redeeming older higher coupon debt help explain why sentiment has improved in the days around this quarterly update, as investors reassess both growth potential and perceived risk in PNC Financial Services Group.
Capitalize on the renewed interest in PNC Financial Services Group by scanning a hand picked set of banks with resilient earnings and balance sheets through the list of solid balance sheet and fundamentals (26 results).Bulls point to PNC Financial Services Group’s faster reported revenue growth and tangible book beat, while bears highlight choppy trading and credit charge offs. Which story does the current valuation ultimately reflect next?
Most Popular Narrative: 15% Undervalued
PNC Financial Services Group closed at $225.53, while the most followed narrative pegs fair value closer to $263.71. This frames the current debate around how much of the long term plan is already reflected in the price.
PNC Financial Services Group expects its multi year AI and automation program, which targets about 40 points of operating leverage from 2025 to 2030 on top of earlier gains and focuses on roughly 171 opportunities and US$1.4b of addressable spend, to further support net margins and earnings.
Record technology investment of about US$3.5b a year, with tech spend planned to grow 10% and roughly one fifth of the increase tied to AI projects, is intended to keep expenses controlled relative to revenue and underpin operating leverage and profit growth.
See why 50 investors see PNC Financial Services Group as 14% undervalued.
Result: Fair Value of $263.71 (UNDERVALUED)
Still, the narrative around PNC Financial Services Group can change quickly if fee-based lines soften or if rising charge offs start to pressure earnings quality.
Find out about the key risks to this PNC Financial Services Group narrative.
Another Angle On PNC Financial Services Group’s Valuation
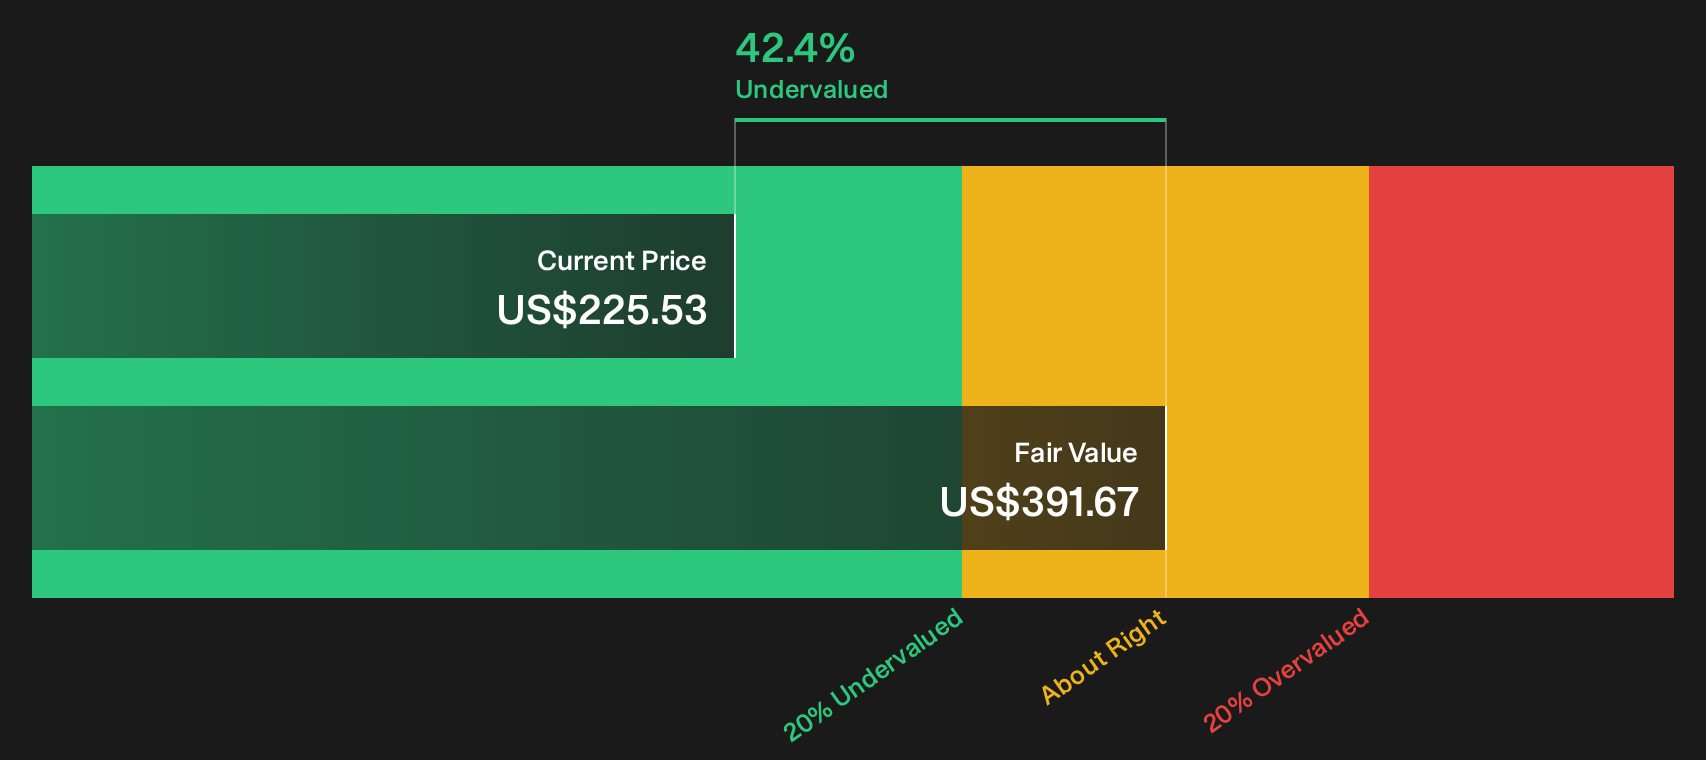
On one hand, PNC Financial Services Group looks inexpensive against some fair value estimates, with the stock at a 42.4% discount to an SWS DCF figure of $391.67. On the other, that DCF rests on long range cash flow assumptions that can shift quickly when bank earnings drivers change.
Our DCF model treats those future cash flows as the anchor, so any change in revenue trends, margins or required returns can move the output a long way in either direction. The open question for you is which signal carries more weight: the current price on screen, or the cash flow story reflected in that $391.67 figure.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
The bullish and cautious takes on PNC Financial Services Group are both on the table, so move quickly, test the data, and decide where you land. To see which positives investors are focused on right now, start with the 4 key rewards.
Looking for more investment ideas beyond PNC Financial Services Group?
Do not stop with one bank. Cast a wider net across high quality businesses so you keep fresh options on the radar instead of reacting late.
- Target resilient compounding by scanning a curated pool of businesses trading below intrinsic value through the 29 high quality undervalued stocks.
- Prioritise sleep at night income by reviewing companies offering strong yields and solid payout histories using the 6 dividend fortresses.
- Strengthen your downside protection by focusing on companies with robust finances and dependable fundamentals through the list of solid balance sheet and fundamentals (26 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com