
ATOSS Software Stock In Focus After Earnings Beat And Higher Margin Target
- ATOSS Software reported third quarter 2026 revenue of €52.57 million and net income of €14.4 million, with earnings per share from continuing operations of €0.91. The company also issued updated guidance that points to a higher operating margin target supported by AI driven efficiency gains.
- The leadership reshuffle, with CEO Andreas Obereder set to move to the supervisory board and weaker on premise licence demand pulling full year revenue expectations toward the lower end of the range, increases the emphasis on cloud, AI and internal productivity as key levers for the business model.
- The following sections explore how ATOSS Software's higher operating margin target could reshape the existing investment narrative around cloud and AI driven workforce management.
Compare how ATOSS Software’s AI focused efficiency story stacks up against other potential candidates by scanning the 39 profitable AI stocks that aren't just burning cash that pair real earnings power with automation tailwinds.
ATOSS Software Investment Narrative Recap
To hold ATOSS Software, you need to believe that cloud based workforce management with embedded AI can support durable earnings power, even if licence demand stays patchy. The raised operating margin target built on AI driven efficiency puts execution squarely in focus. The near term catalyst is whether AI tooling and internal productivity actually sustain this higher profitability.
The biggest near term risk is that weaker on premise licence appetite spills over into slower new cloud contracts or softer migrations, especially in more cautious manufacturing and SMB segments. If pipeline conversion or ARR expansion disappoints, the higher margin ambition could meet a flatter revenue base.
The updated guidance that points to an operating margin of about 37% is the announcement that really matters alongside the latest quarterly figures. ATOSS Software is relying on AI enabled productivity and a largely stable headcount to do more with the same cost base. That directly connects to the thesis around operating leverage.
Higher profitability targets can act as a support for sentiment if revenue trends sit at the lower end of management ranges. At the same time, the expectations for execution are now higher. Any stumble in AI adoption, internal tooling, or salesforce productivity would not only pressure margins, it would also weaken one of the clearest catalysts in the story.
ATOSS Software Consensus Expectations And AI Assumptions
Analysts linking the ATOSS Software AI story to the numbers are effectively asking you to judge whether the current efficiency push can support a glide path to larger earnings on a steadier cloud base. Their models bake in both a specific pace of expansion and a slight squeeze in profitability, which gives you a concrete yardstick to compare against your own expectations for the roll out of AI tools and the mix shift toward subscriptions.
Current forecasts point to revenue increasing by 13.5% a year on average over the next three years, with profit margins moving from 25.6% today to 24.9% in the same timeframe. The margin compression they build in leaves less room for error on AI productivity gains, because the earnings outcome relies more heavily on scaling revenue than on a rising margin profile.
On the earnings line, the consensus view looks for profit to reach €72.9 million by about 2029 compared with €51.2 million today. That implies an increase of roughly €21.7 million in annual earnings, which is a meaningful step up that now needs to be squared with the updated margin ambitions tied to AI enabled efficiencies and a largely stable headcount.
ATOSS Software's narrative projects €292.7 million revenue and €72.9 million earnings by 2029. This requires 13.5% yearly revenue growth and about €21.7 million earnings increase from €51.2 million today.
The same analyst framework links those profit expectations to a P/E of 32.0x on 2029 earnings, compared with 30.5x today and 18.1x for the wider GB Software industry. For anyone assessing the stock, the key question becomes whether AI driven automation and a higher mix of recurring subscription income justify paying a richer multiple than the sector, while also accepting only modestly lower margin assumptions than today.
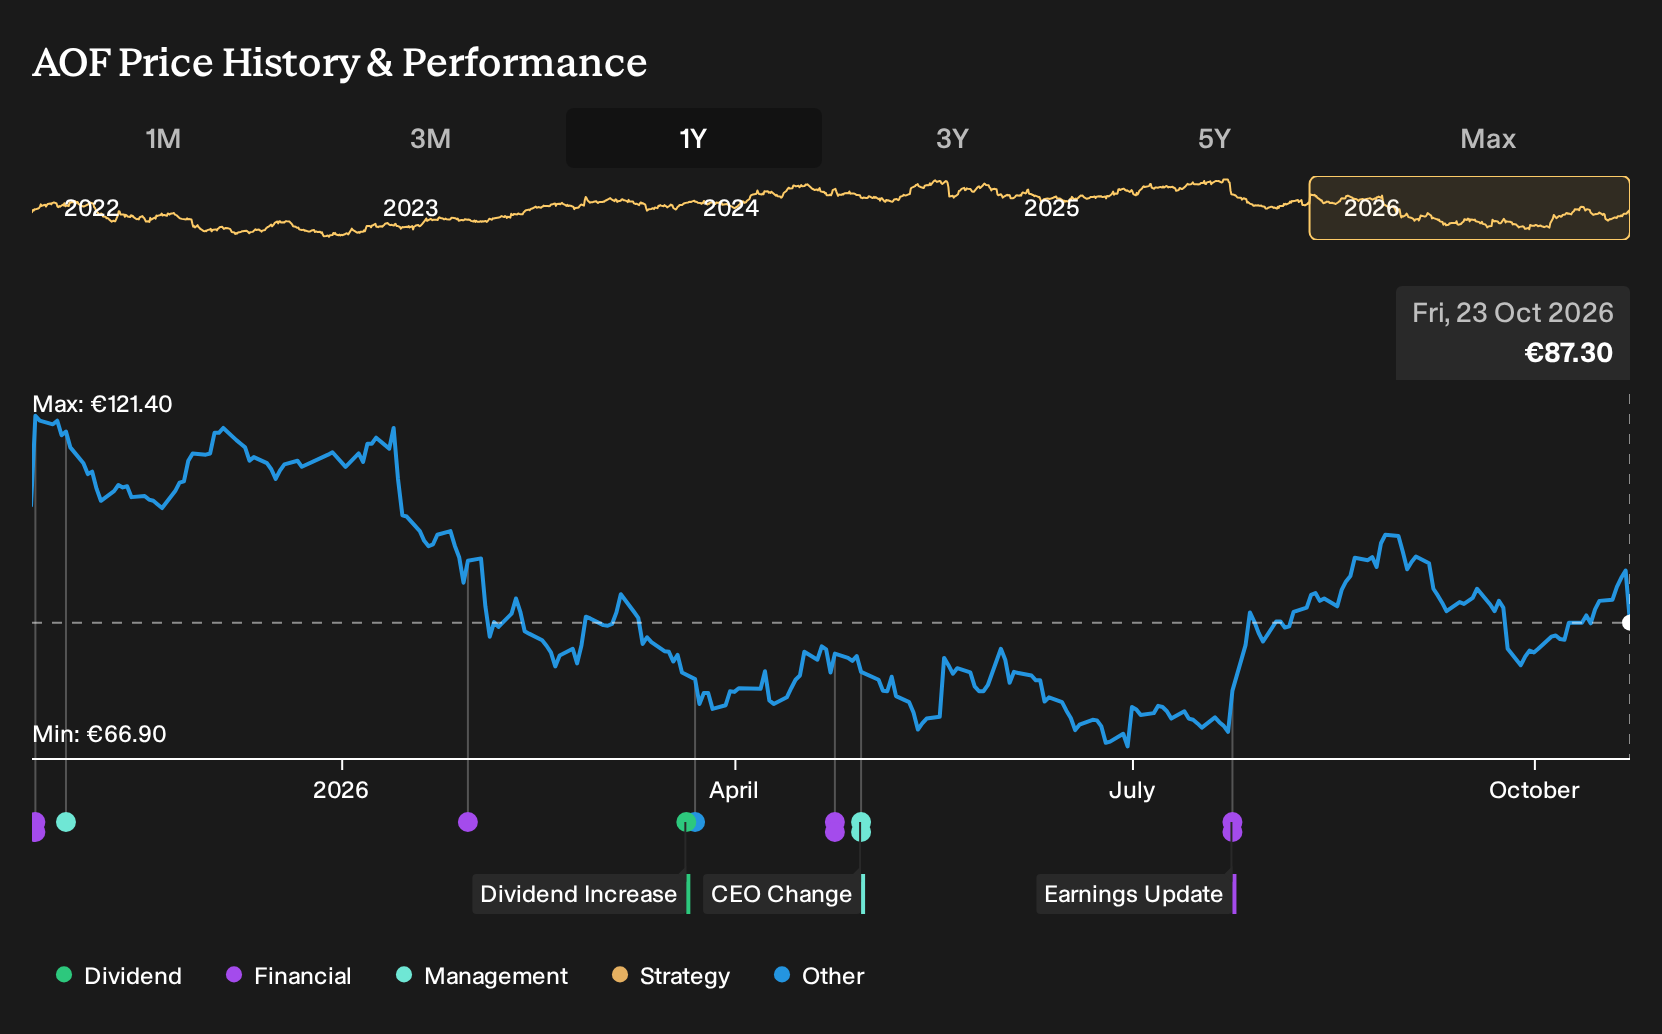
Revenue forecasts of €292.7 million and expected earnings of €72.9 million by 2029 also underpin a consensus price target of €123.38 per share, set against a current price of €98.2. The spread between bullish and cautious analyst targets, from €157.0 down to €91.0, underlines how differently market participants are weighing the upside from AI powered productivity against the risk that slower licence demand and more hesitant SMB customers limit the benefit of those tools.
Uncover why ATOSS Software's fair value indicates a 41% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Cloud momentum is the big swing factor in the more upbeat ATOSS Software narrative. The most optimistic analysts were already pencilling in €302.8 million revenue and €76.3 million earnings by 2029, with a P/E of 38.8x, before this earnings beat and higher margin target, which may push some views even further while others stay cautious.
Explore 2 other ATOSS Software fair value estimates, including one that suggests as much as 43% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ATOSS Software research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for ATOSS Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ATOSS Software's overall financial health at a glance.
Looking For More Investment Ideas Beyond ATOSS Software?
Once you have a handle on ATOSS Software, it often helps to widen the lens and compare it with other opportunities that match your risk tolerance and return goals. The Simply Wall St Screener can surface a range of stocks that align with different priorities, from balance sheet strength to potential mispricing.
- If capital preservation sits high on your list, start with a set of 221 resilient stocks with low risk scores that can help anchor a more cautious portfolio.
- For investors hunting for mispriced opportunities, focus on companies flagged as 201 high quality undervalued stocks based on their fundamentals and current market pricing.
- If you want sturdier financial footing alongside earnings power, filter for stocks in the list of solid balance sheet and fundamentals (205 results) to see which businesses pair resilience with quality metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com