
Bentley Systems Shares Slid Even Though Profit Rose
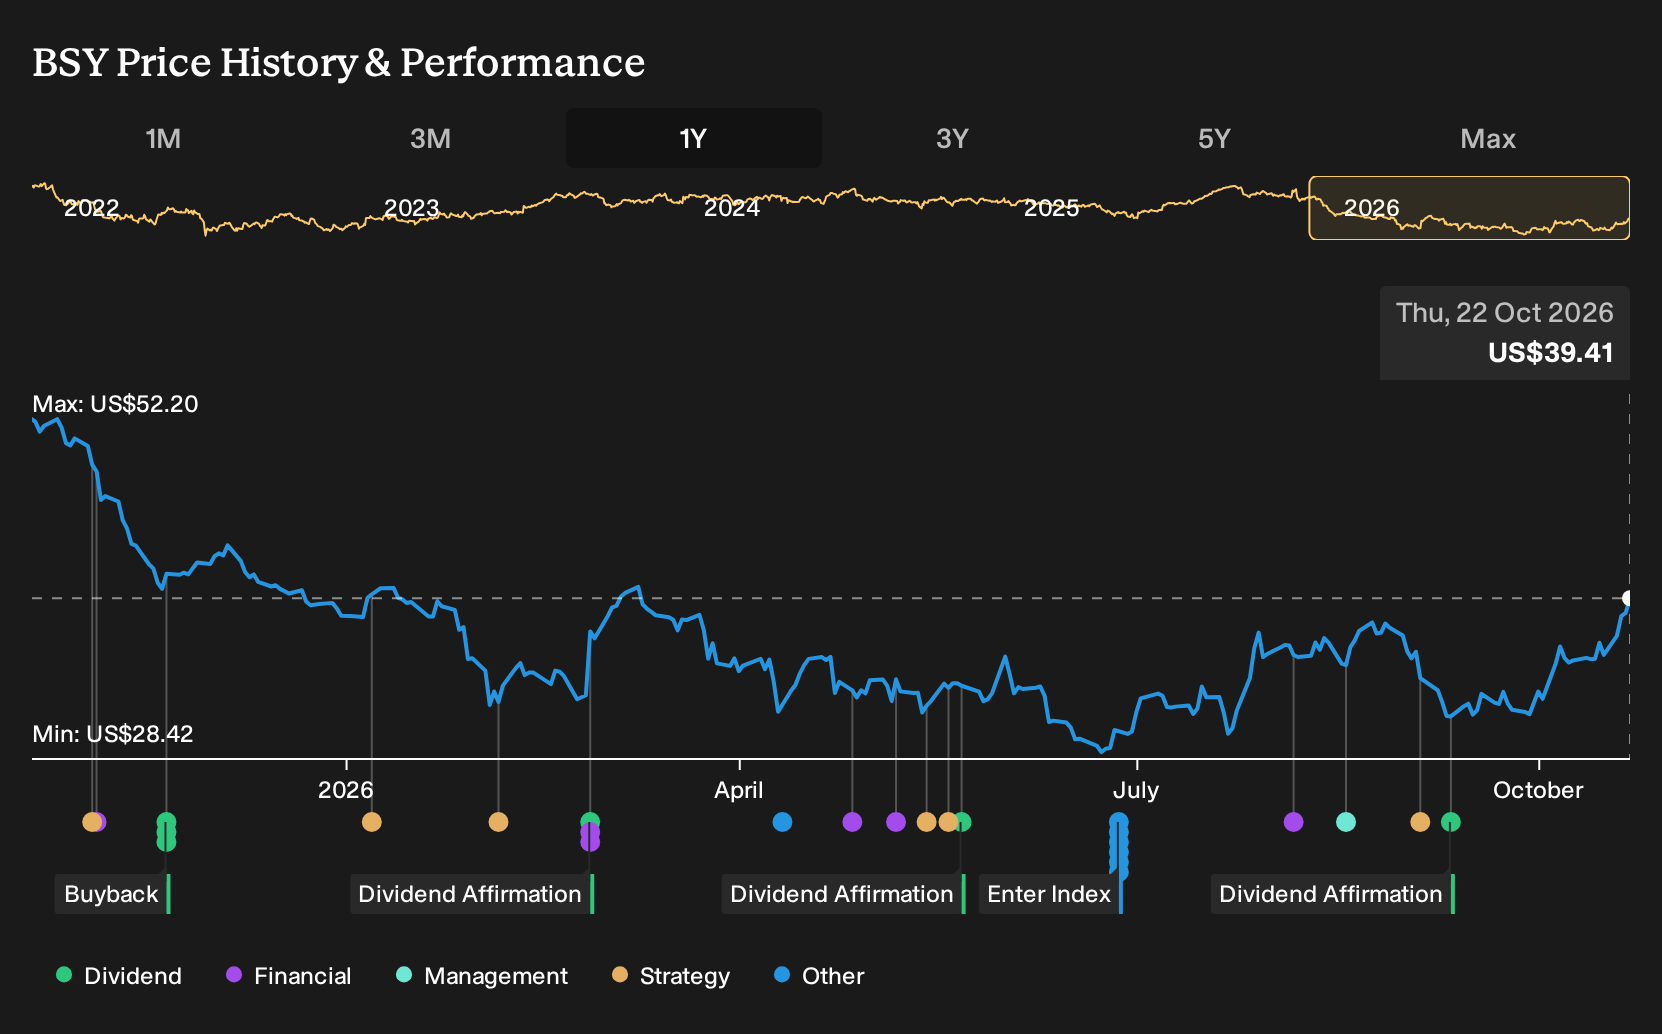
If you had decided on 22 October 2025 to skip Bentley Systems despite upbeat talk about infrastructure and AI driven software, the next twelve months would have felt very different from holders’ experience. For Bentley Systems shareholders, the loss over the past year was 22.6%, including dividends. With that in mind, which assumptions and early warnings in those October 2025 reports deserved closer attention before committing capital?
This theme extends beyond Bentley Systems. See which of 55 AI infrastructure stocks may still merit a closer look.
The Two Stories Bentley Systems Investors Had To Weigh
The shares cost US$52.01 at the start of the period, and investors in Bentley Systems were choosing between two sharply different stories about what that price implied.
The bullish view argued that global infrastructure spending and digital transformation would keep expanding the market. It pointed to a Fair Value of US$59.08, a rough estimate of what the stock might be worth if revenue rose 9.7% a year and margins reached 23.6%.
The bearish side flagged fiscal pressure and open-source rivals as threats. It anchored on a Fair Value of US$43.38 and highlighted the risk that rising compliance and cybersecurity costs could squeeze profitability.
What The Results Changed For The Bentley Systems Thesis
Bentley Systems reported Q2 2026 revenue of US$410.7 million and net income of US$78.6 million, higher in absolute terms than Q2 2025. Net margin edged down from 19.4% to 19.1%, so the profitability part of the bullish story was not fully confirmed. The evidence cut both ways for investors weighing strong growth assumptions against future margin expansion.
The hinge assumption here was that rising scale would lift profitability. When you assess another software group making that claim, track whether revenue and net income grow faster than the reported net margin. Treat any margin drift as a signal to revisit the upside case.
What Bentley Systems' Lower Price Asks You To Believe
Bentley Systems now trades at US$39.41, well below where holders started one year ago after a 22.6% loss over the past year. The selected Narrative’s Fair Value sits above the current price and leans on stronger recurring economics than the market seems to be pricing in.
The pitch is that higher quality ARR, helped by AI heavy workflows and asset based subscriptions, will matter more than the recent share-price slide. For that higher figure to be reached, a buyer today would have to assume Asset Analytics and resources software genuinely mature into a durable second growth engine.
"Asset based subscriptions are already above a $50m run rate, and resources contribute over 20% of sector attributable ARR as the fastest growing sector. The numbers imply that the share price treats Bentley as a slower growing, fully mature software company, even though ARR, burdened free cash flow of $426m, net debt leverage at 1.9x, and ongoing dividends and buybacks together point to a business that the bullish narrative views as undervalued."
One Narrative disagrees with today's price. → See where this Narrative says Bentley Systems should trade
Looking Past Bentley Systems
Once you map Bentley Systems against its peers, a different angle appears. Big infrastructure software still leans on broader productivity and cloud stacks.
Many enterprise buyers want design tools that plug into their everyday workflow. They also look for AI features that sit inside documents, email and collaboration hubs.
Another large vendor is trying to be that common layer. It supplies the cloud backbone and the office software where those AI agents now sit.
If that approach works, the battle is not just about engineering tools. It is also about who controls the screens your users already watch all day.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 15% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com