
Is Prada (SEHK:1913) Undervalued After 9 Month Sales Grew 12%?
Prada (SEHK:1913) moved into focus after its nine month 2026 sales and trading call, where management reported net revenues up 12% and highlighted strong retail momentum in the Americas.
Prada’s latest trading update has landed after a mixed year in the market, with the share price at HK$38.8 and short term moves fairly muted. However, a year to date share price return down 13.2% and a 1 year total shareholder return down 17.95% signal fading momentum despite the recent sales strength.
Scan luxury peers showing stronger price momentum than Prada and filter for resilient balance sheets with the hand picked 221 resilient stocks with low risk scores that may better match your risk profile.
Prada is posting 12% revenue growth while the share price has drifted lower this year. Is more of the valuation upside still in front of investors, or has most of it already been reflected?
Most Popular Narrative: 20% Undervalued
Prada’s most followed narrative points to a fair value of about HK$48.21 versus the latest HK$38.8 close, which implies investors are weighing long term brand and margin drivers against recent share price weakness.
Prada's ongoing investment in new product collections, broadening price points and enhancing personalization (e.g. make-to-measure, bespoke in flagship stores), positions the group to capture growth from both affluent core clients and younger, aspirational demographics globally, supporting long-term revenue and gross margin expansion.
See why 7 investors see Prada as 20% undervalued.
Result: Fair Value of HK$48.21 (UNDERVALUED)
Still, the Prada narrative depends on affluent tourism remaining supportive and on higher marketing and digital spending eventually paying off. This outcome could disappoint if demand softens.
Find out about the key risks to this Prada narrative.
Another View: Prada’s Richer Market Multiple
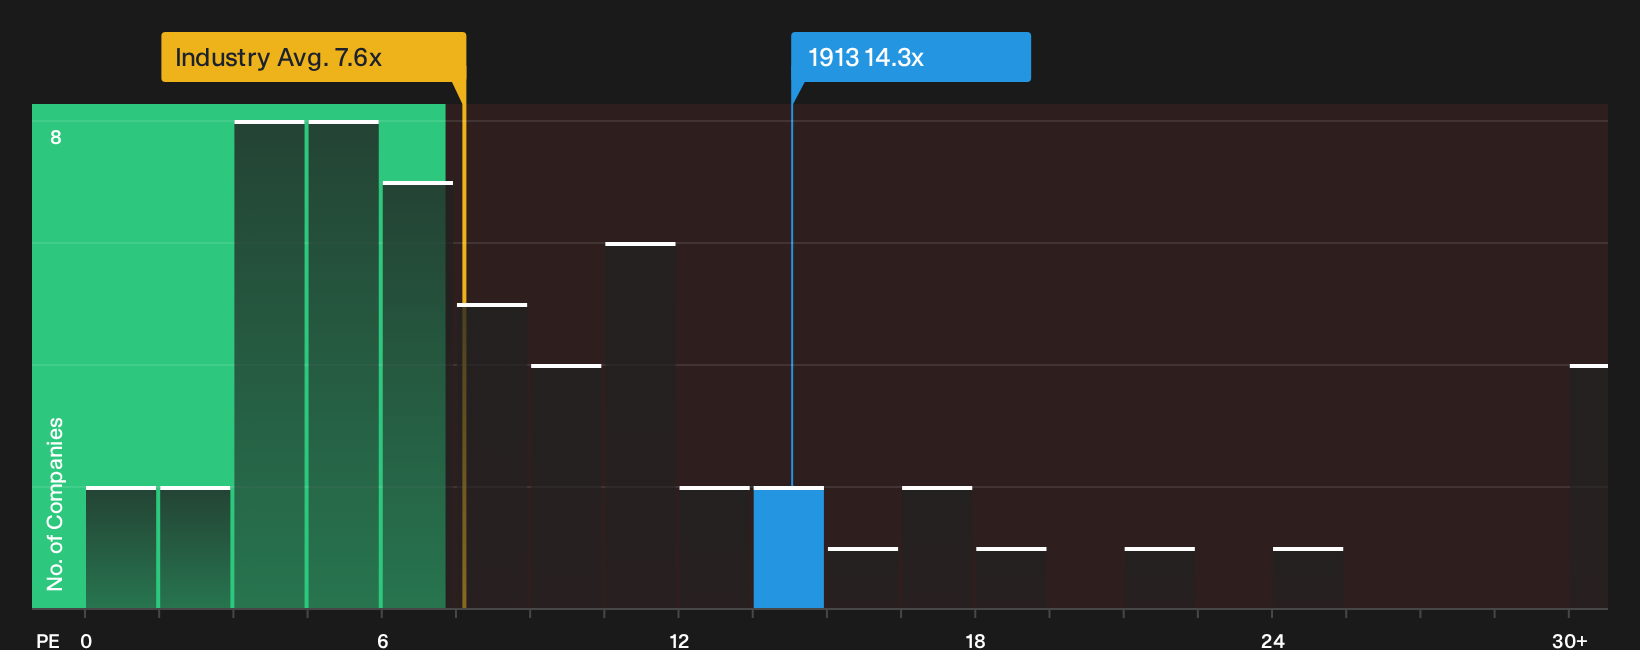
The SWS DCF model points to a fair value of HK$56.05, which sits above both the HK$48.21 narrative estimate and the current HK$38.8 price. Yet the market is already paying a P/E of 14.3x for Prada compared with 7.6x for the Hong Kong luxury sector and a fair ratio of 9.5x. Is that premium signaling quality that the model underestimates, or just extra valuation risk if sentiment cools?
For a closer look at how this P/E gap could close over time, and what that might mean for holders weighing upside against downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Prada’s valuation can feel confusing, so move quickly from headline opinions to hard numbers and pressure test the upside and downside for yourself with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Prada?
If Prada’s mixed signals leave you wanting a broader watchlist, you can use a few focused stock screens tailored to different priorities.
- Target potential mispricing by reviewing companies flagged as 201 high quality undervalued stocks that pair current market prices with solid underlying fundamentals.
- Strengthen the income side of your portfolio by scanning 226 dividend fortresses that offer higher yields while still passing quality checks.
- Sleep easier through volatility by focusing on a list of solid balance sheet and fundamentals (205 results) that can handle shocks without heavy refinancing pressure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com