
Curbline Properties (CURB) Could Be 15% Undervalued Following Q3 Results And Raised FFO Guidance
Curbline Properties (CURB) just posted third quarter results that combined higher sales with softer earnings, then trimmed full year net income guidance while still pointing to stronger operating FFO and ongoing acquisition driven expansion.
The earnings update landed alongside a sharp shift in sentiment, with Curbline Properties’ 1 day share price return of 7.25% lifting the stock to $28.86 and leaving the year to date share price return at 24.77%, even after a 90 day share price decline of 8.56%. The 1 year total shareholder return of 22.32% suggests recent momentum has picked up again as investors weigh stronger operating FFO guidance, heavier acquisition activity and a lower net income outlook.
Scan how Curbline Properties compares with other acquisition driven real estate plays by checking our hand picked list of list of solid balance sheet and fundamentals (26 results).After a 7.25% jump to $28.86 on the back of mixed guidance, the real question around Curbline Properties is simple. Does that move already reflect the acquisition push and higher operating FFO, or is patience on a better entry price still your edge?
Most Popular Narrative: 15% Undervalued
Curbline Properties closed at $28.86, while the most followed narrative pegs fair value at $33.94. This creates a valuation gap that hinges on how far the acquisition engine can run.
Underlevered balance sheet with net debt to EBITDA below 1 times and over $250 million of cash on hand enables Curbline to fund roughly $750 million of annual investments at attractive cap rates, creating meaningful acquisition driven FFO per share growth with limited financing risk.
See why 1 investors see Curbline Properties as 15% undervalued.
Result: Fair Value of $33.94 (UNDERVALUED)
Still, the bullish story on Curbline Properties relies heavily on acquisition yields remaining attractive and on shorter leases not backfiring if tenant demand cools.
Find out about the key risks to this Curbline Properties narrative.
Another View On Curbline Properties
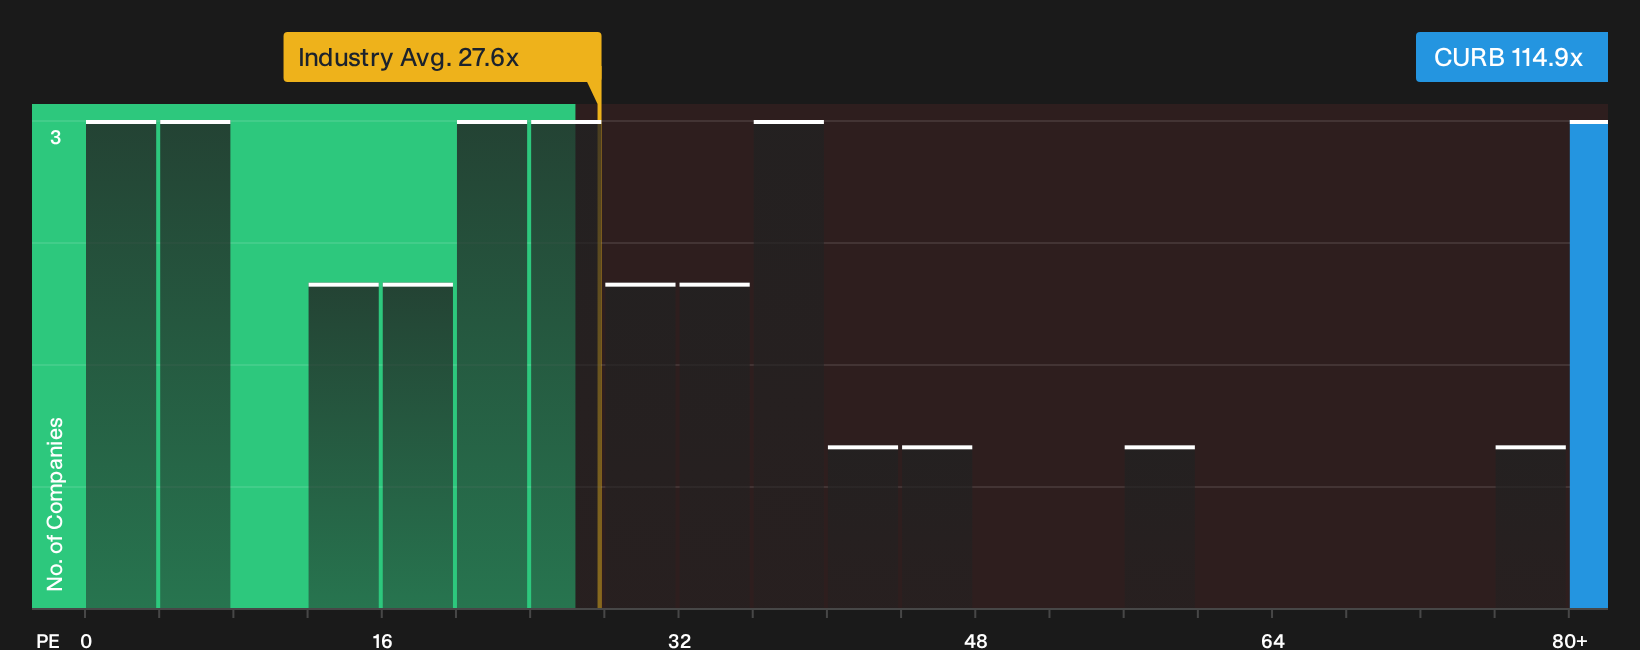
The story shifts when the focus moves from the SWS DCF model to what the market is actually paying for Curbline Properties today. The stock trades on a P/E of 114.9x compared with 26.6x for the US Retail REITs group and 70.4x for direct peers, while the fair ratio is 40.1x. That gap points to meaningful valuation risk if sentiment cools before fundamentals catch up.
For investors who want to stress test that premium against hard numbers rather than headlines, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Curbline Properties is split, and that is exactly when doing your own homework matters most. Move quickly and weigh both the upside and the caution flags in 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Curbline Properties?
Do not stop your research with Curbline Properties. Use the Simply Wall Street Screener to find additional ideas that fit your own risk and return priorities.
- Target potential mispricings by scanning a curated group of quality companies that appear inexpensive based on their numbers through 29 high quality undervalued stocks.
- Strengthen the income side of your portfolio by focusing on businesses built around dependable payouts using the 6 dividend fortresses.
- Prioritize protecting your downside by filtering for robust finances and resilience in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com